Unlock Our Free Investment Insights

Investing in the New Trump Economy


Trish Regan is one of America’s most recognized financial journalists and digital media hosts. An award-winning reporter, author, television personality, and speaker, Trish is a leading economic and political thought leader who helps viewers to better understand the most critical issues facing the economy and American business today. With extraordinary access to newsmakers and industry sources, as well as a knack for anticipating opportunities and risks in investing, Trish leverages her knowledge of how the mainstream media works to enable subscribers to best understand the information moving markets.
Trish is the Co-Founder and Executive Editor of 76research. She is also the founder, owner, and host of the daily livestreamed Trish Regan Show with more than 80 million views per month. Prior to founding 76research with longtime friend Rob Hordon, Trish anchored some of the most highly rated financial programs at America’s most noted financial networks including CNBC, Bloomberg, and most recently, Fox Business News.
Throughout her career, Trish has interviewed numerous heads of state, including multiple U.S. Presidents, foreign leaders, Fortune 500 CEOs and other institutional, charitable, and government leaders.
Trish credits her start in journalism to her fifth grade position as school correspondent for her local New Hampshire newspaper. But, while Trish showed an early interest in reporting and writing, it wasn’t until years later that she chose to make journalism her career. In fact, she originally intended to pursue a career in finance and worked as an analyst in emerging debt markets at Goldman Sachs while a student at Columbia University. Fluent in Spanish, Trish focused primarily on Latin American sovereign debt markets including Argentina, Mexico, Venezuela, and Brazil, but when Bloomberg Television offered her an opportunity to work as a correspondent, she made the jump into financial media.
Beginning at Bloomberg in 2000, Trish was on the front lines as the dot-com bubble burst. She covered its aftermath from Silicon Valley and San Francisco as a correspondent at MarketWatch before moving back to New York to work as a correspondent for CBS News. In 2006, Trish returned to her financial roots as an anchor on CNBC’s top-rated daily markets program The Call where she reported on the 2008 financial crisis in real time. While an anchor at CNBC, Trish also reported business news for NBC's Nightly News and The Today Show. In addition, she produced and hosted the two most highly rated documentaries in CNBC's history – Marijuana Inc and Marijuana USA, which investigated a massive and fast-developing underground industry. Trish predicted that industry would soon become mainstream in her book Joint Ventures: Inside America's Almost Legal Marijuana Industry, published by Wiley & Co. in 2010.
In 2011, Trish went back to Bloomberg Television to anchor the network's afternoon market close coverage as host of Street Smart with Trish Regan. While at Bloomberg, Trish was the network's main political anchor for all political television coverage of the 2012 election, including both the Republican and Democrat conventions and the election itself. From 2013 through 2016, Trish also worked as a front-page economic columnist for USA Today, writing on the biggest trends in business, markets and the economy.
In 2015, Trish left Bloomberg Television to join Fox News and Fox Business as the anchor of her new program The Intelligence Report with Trish Regan during FBN’s market hours. She would later move to an evening program and become the only woman in cable TV at that time to host a primetime show. Trish Regan Primetime grew 8pm ratings to a level never before seen at Fox Business.
While at Fox, Trish Regan also anchored two Republican Presidential debates – making history as part of the first all-woman team, with colleague Sandra Smith, to anchor a Presidential debate. She also appeared as an economic and markets contributor to all Fox News programming and was also a guest anchor on Cavuto, Fox and Friends, The Five, and primetime programming. In addition, Trish anchored all primetime coverage of the 2016 Democrat and Republican conventions for Fox Business and was a co-host alongside Neil Cavuto, Maria Bartiromo, Lou Dobbs and Stuart Varney for the network's main political events. Trish left Fox in 2020 and began work on the creation of her own digital media enterprise which debuted in August 2020. Her focus now is her own program and 76research, although she still appears regularly on other platforms both in cable news and in digital media.
Trish graduated with honors from Phillips Exeter Academy before going on to study opera at New England Conservatory and graduate cum laude with a degree in history from Columbia University. While at Exeter, Trish was the first-place winner of the Harvard Musical Association’s Competition for Excellence in Music, becoming the first singer to win the top prize since the organization was founded in 1837. She later studied opera and German at The American Institute for Musical Studies in Graz, Austria. Her operatic singing skills enabled her to represent her home state as Miss New Hampshire in The Miss America Pageant, where she won the talent competition and the first B. Wayne Award for the contestant with the most promise in the performing arts.
Trish's journalism awards have included multiple Emmy nominations for her documentary and investigative reporting. Trish was also recognized with a George Polk nomination for her long-form reporting covering the aftermath of Hurricane Katrina with a team from CNBC. While at MarketWatch in San Francisco, Trish was named SF’s Society for Professional Journalists most promising broadcast journalist.
Trish Regan was born and raised in New Hampshire. She now makes her home outside New York City with her husband and three young children.
A successful fund manager and stock picker, Rob Hordon has extensive experience investing across asset classes, sectors, geographies and strategies. With consistent emphasis on ways to preserve and grow assets and manage risk, Rob has offered guidance to thousands of financial advisors and wealth management professionals in the United States and abroad over the course of a multi-decade Wall Street career.

Rob’s professional investment career began in the late 1990s as an associate in the Equity Research department of Credit Suisse First Boston, where he covered wireless telecommunications stocks at the dawn of the mobile phone era. As a recent college graduate, Rob had a front row seat at one of the epicenters of the tech bubble. He witnessed for the first time the stock market’s potential to deliver immense value creation through innovation but also its characteristic tendency towards excess.
Rob went on to obtain his MBA from Columbia Business School, where he focused on security analysis and through his course work learned from some of the top investment practitioners in the country. Upon graduation from Columbia, he took an analyst role in the Risk Arbitrage department of a firm then called Arnhold and S. Bleichroeder Advisers, which would later be renamed First Eagle Investment Management.

For approximately seven years, Rob worked as a member of a small team that ran a hedge fund strategy focused on identifying mispriced long-short opportunities among companies involved in merger and acquisition activity. Just prior to the 2008 financial crisis, he transitioned over to First Eagle’s Global Value team under the auspices of the legendary international investor Jean-Marie Eveillard.

As an analyst on the team, Rob was responsible for initiating and covering several billion dollars of public equity investments across a wide range of industry sectors and countries. This move also reunited him with renowned Columbia Business School economist and author Bruce Greenwald, who had recently joined as Director of Research. As colleagues and mentors, Bruce and Jean-Marie would become the two most formative influences on Rob's investment career.
In 2011, Rob proposed and worked with the team to develop a new multi-asset investment strategy built around the same long-term value-oriented investment philosophy pioneered by Jean-Marie. As co-portfolio manager of the First Eagle Global Income Builder Fund, Rob was directly responsible for over a billion dollars of assets under management with a particular focus on dividend-paying stocks and credit instruments. Rob and his partner later re-created and managed this strategy at a London-based boutique investment firm, J O Hambro Capital Management, beginning in 2017.
In 2023, Rob teamed up with his longtime friend Trish Regan to form 76research, where he is Co-Founder and Chief Investment Strategist. This entrepreneurial venture merges his passion for investing, research and writing with his desire to help others benefit from the long-term wealth creation potential of the stock market.

The son of an economics professor and elementary school teacher, Rob is a proud husband and father of three whose interests include history, philosophy, sailing and world travel. He was born in New York City and grew up in northern New Jersey, where he attended local public schools.
Rob Hordon is a Chartered Financial Analyst. In addition to his MBA from Columbia Business School, he received his Bachelor’s degree in Politics from Princeton University and was awarded a Certificate in Political Theory. His senior thesis, entitled Justice without Truth: Contingency in American Moral Thought, explores how the philosophical tradition of American Pragmatism offers a roadmap out of the moral and political abyss of postmodern relativism.
Investing in the New Trump Economy
Enter Your Email to Access this Content
Trish Regan and Rob Hordon — Co-Founders, 76research
The American economy is undergoing a profound transformation.
President Trump's return to the White House has brought major changes to U.S. trade policy, taxation, regulation, energy policy and America's relationships with the rest of the world.
At the same time, extraordinary advances in AI and other emerging technologies are creating investment opportunities that may ultimately prove far more important than the day-to-day political headlines.
For investors, the combination presents enormous opportunities—but also various risks.
At 76research, our mission is to help individual investors navigate these changes with the kind of independent, institutional-quality research that has traditionally been available primarily to Wall Street professionals.
We believe the United States remains exceptionally well positioned for long-term economic growth. American companies dominate many of the world's most important industries, especially technology, while innovation continues to create entirely new markets.
But successful investing requires more than an optimistic outlook. It requires understanding how economic and political developments affect individual businesses—and identifying attractive investments before their full potential is reflected in stock prices.
Our research combines macroeconomic and geopolitical analysis with detailed company research and disciplined portfolio construction.
Below, we examine one of the most important issues currently facing investors: the conflict with Iran, its impact on energy prices, and why we believe the economic pressure on Tehran could ultimately lead to a more favorable investment environment.
Iran Is Running Out of Financial Oxygen—Will Oil Prices Finally Break?
October 1, 2026
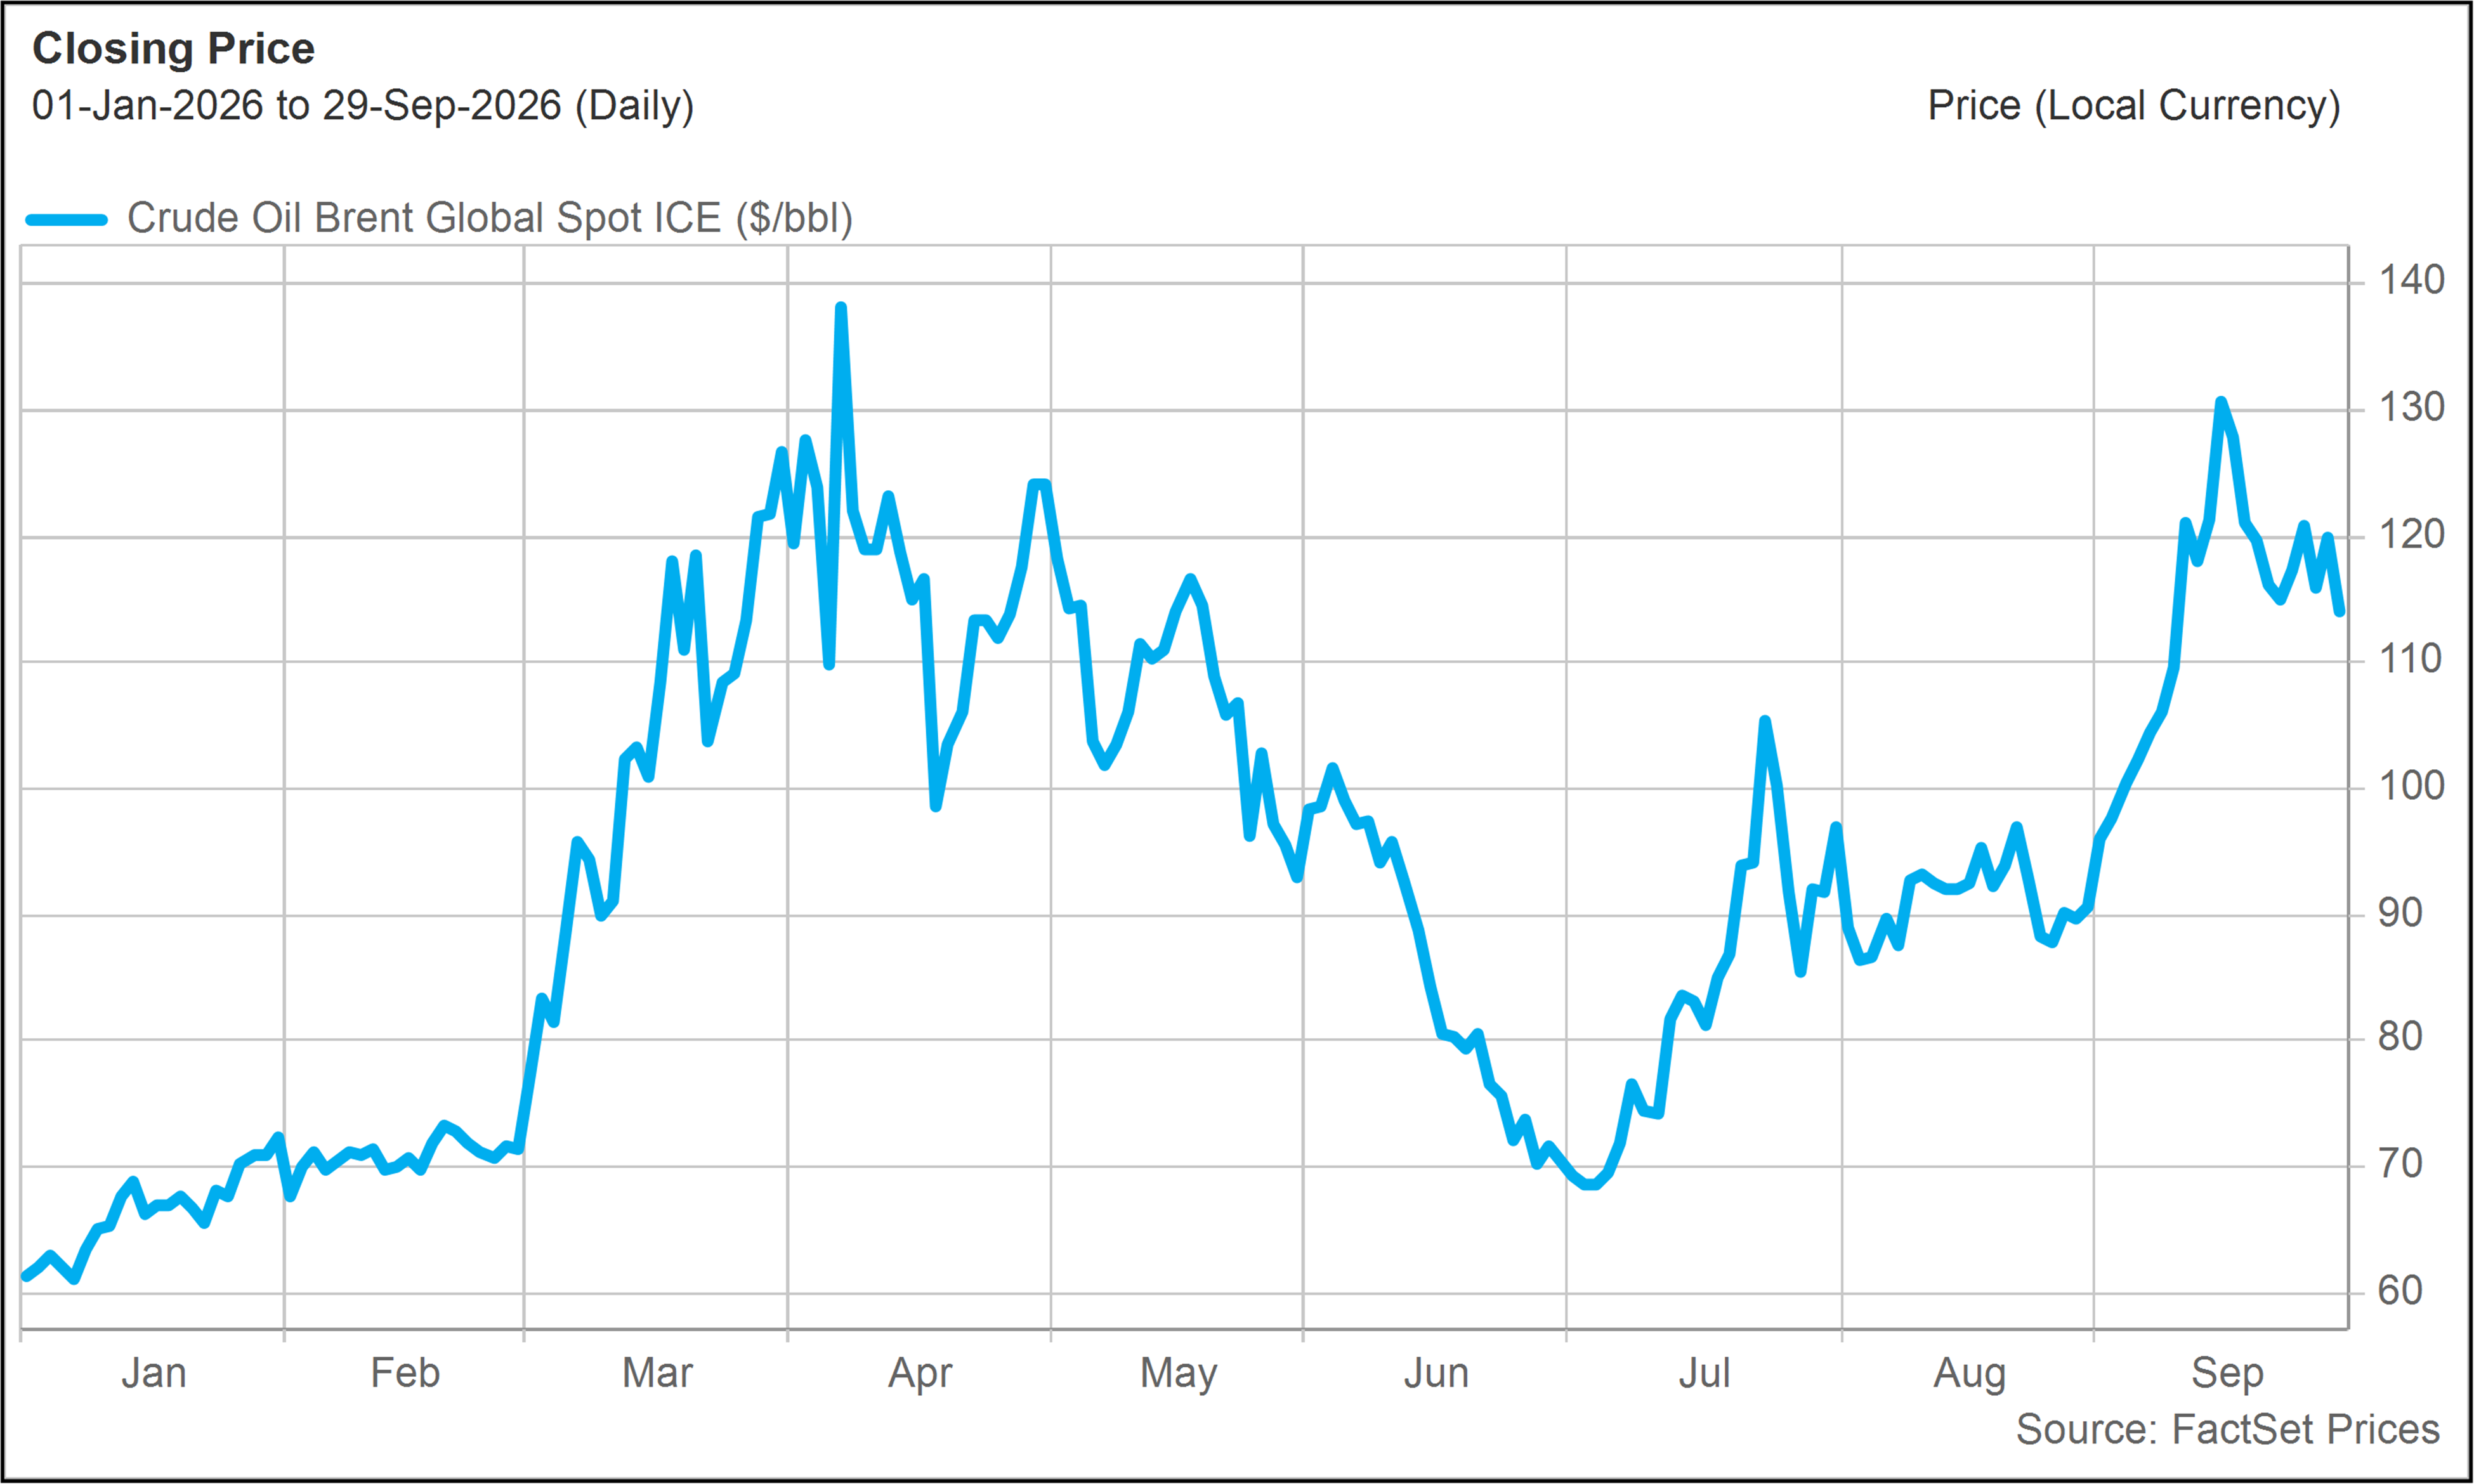
With midterm elections on the horizon and the Federal Reserve now hiking interest rates, the price of crude oil may be the single most important variable shaping both the economic and political outlook.
If oil remains elevated, it threatens to keep inflation sticky, push long-term bond yields even higher, and force the Fed to increase already high interest rates.
At the same time, high energy prices appear to be the biggest political vulnerability facing Republicans heading into November. Gasoline prices are now roughly 50% higher than before the Iran war began, infuriating many.
As painful as today's oil prices are for investors and consumers alike, we see good reasons to remain optimistic that relief will eventually come.
In fact, the very forces that helped drive oil prices higher may ultimately help bring them back down.
Whether that happens in time to materially change the political landscape before November remains to be seen. That said, investors should be careful not to let frustration over a delayed outcome turn into pessimism about the eventual one.
Angry voters
The American voting public is clearly losing patience with high oil prices.
Prediction markets recently pointed to Democrats taking control of the House of Representatives with near-certainty. They also leaned toward a Democratic majority in the Senate, although much less decisively.
The disruption to oil markets has clearly lasted longer than the administration—and most observers—expected when the military operation against Iran began in February.
Public disappointment is therefore not surprising, especially after hopes for a near-term resolution faded when the ceasefire collapsed over the summer.
The cost of living problem
James Carville, former campaign adviser to Bill Clinton, is credited with coining the expression, "It's the economy, stupid." The very blunt point he was making is that voters care about economic conditions more than anything else.
While Carville's maxim likely remains true in the current environment, the voting public today is hyper-focused on one specific economic concern—affordability.
Inflation has clearly moderated, but after several years of high inflation rates way above recent historical trends, Americans still have sticker shock.
Although cost of living concerns seem to dominate, it is worth noting that many other economic metrics are in fact quite positive.
Since Trump took office and Republicans swept into power nearly two years ago, we have seen a rising stock market along with a relatively low unemployment rate. The S&P 500 has returned more than 35% in less than two years since Trump was elected, which should help Republicans with the investor class.
More good economic data came in at the beginning of October.
Second-quarter GDP growth was revised up to 2.2%, from 1.5%. The Core Personal Consumption Expenditures (PCE) price index—the inflation metric closely watched by Fed officials—came in lighter than expected at 3.0%.
But every consumer still feels the burden of higher prices.
The stock market's success is also not terribly meaningful to the broader population, especially younger voters with minimal savings. Most estimates suggest 40% of the population has no exposure to the stock market at all.
And with respect to energy prices in particular, high prices at the pump and high home heating bills hit rural voters particularly hard.
Whereas urban voters tend to be reliably Democrat-leaning regardless of economic circumstances, rural and suburban districts are more prone to flip from one election to the next.
These voters tend to drive more miles, drive trucks and other heavy vehicles, live in single-family homes rather than apartments, and spend a greater portion of their household income on energy-related expenses.
This means high energy prices have the potential to register a disproportionate impact on election dynamics. Voters in the specific states most at risk for Republican losses in Congress—Michigan, Texas, Ohio, Maine, North Carolina—spend a lot of time in their vehicles.
The good news is that there are growing reasons to believe the pressure could finally begin to ease.
As frustrating as the Iran conflict has been, the physical oil market is adapting—and the economic pressure on Tehran is intensifying.
Despite higher oil prices, the U.S. economy has performed remarkably well this year, supported by strong GDP growth and healthy corporate earnings. The AI boom has, in effect, overwhelmed much of the drag from higher energy costs and the secondary impact of monetary policy.
A sustained decline in oil prices could now turn that headwind into a tailwind—removing what has arguably become the biggest obstacle facing both the economy and the stock market.
The storm before the calm?
As President Trump has noted, the impact of high oil prices on the midterm election is not lost on Iran's current leadership.
Trump has made clear his view that the Iranians are deliberately stalling on peace talks in order to keep oil prices high and prevent Republicans from preserving their control over Congress.
The Islamic Revolutionary Guard Corps (IRGC) helped validate Trump's thesis in late September when it took the extraordinary step of releasing a 25-page letter addressed directly to the American public, criticizing U.S. policy toward Iran.
Within this memo, the IRGC makes many bold claims, including the idea that "the U.S. economy is on the precipice of collapse" thanks to Trump's actions toward Iran.
The memo clearly demonstrates Tehran's understanding that expensive energy creates economic and political problems in Washington. It also displays Iran's preference for a scenario in which Trump is hobbled by a Democrat-controlled Congress.
The Iranians may be overestimating the fragility of the American economy, but they are correct in their assessment that the lack of diplomatic progress is keeping spot oil prices high. They also correctly identify the political significance of depriving Trump of a foreign policy win prior to midterms.
As diplomacy stalls, warfare across multiple fronts continues. This includes the U.S. taking actions to prevent the flow of Iranian oil into world markets. China and other customers are now forced to buy oil from other countries, sending prices higher.
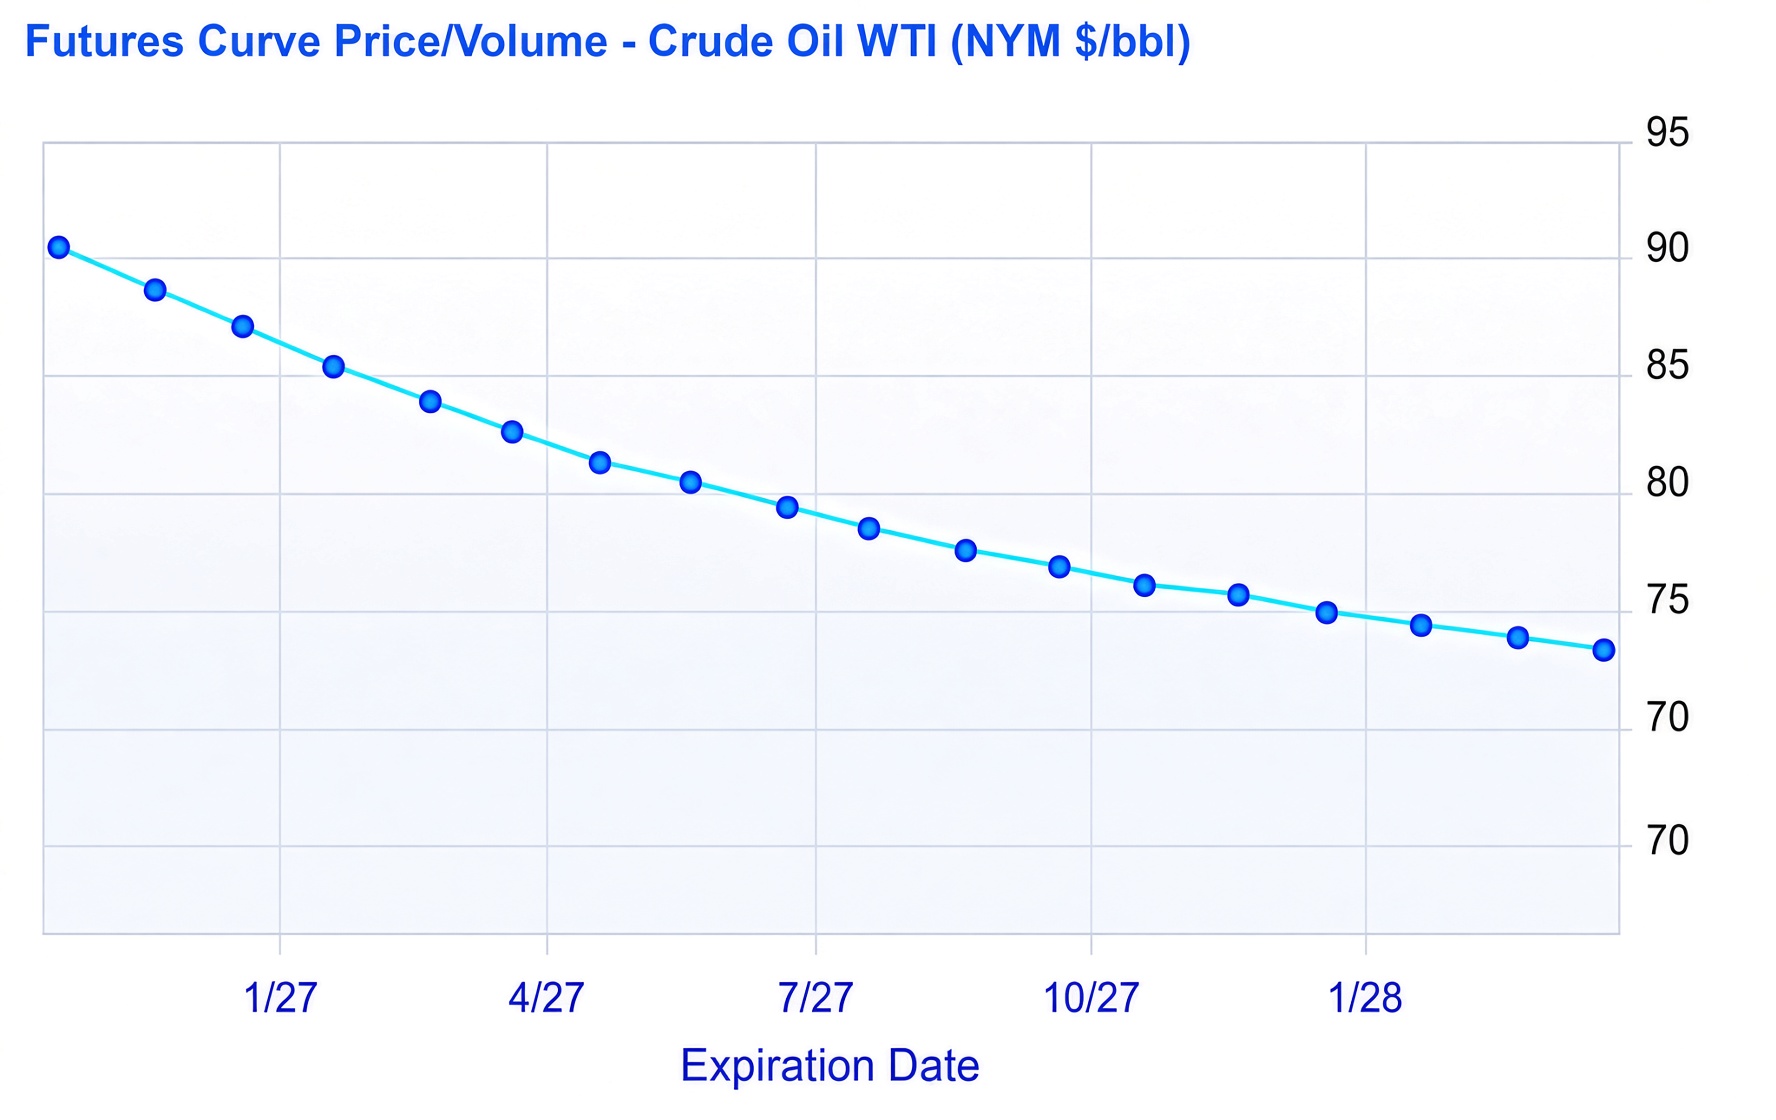
But currently elevated oil prices are masking some significant positive developments, which help explain why oil futures markets continue to signal significantly lower oil prices over the next year or two.
More oil gets through
The precise numbers vary considerably from week to week, but recent estimates suggest Persian Gulf oil exports have recovered substantially from their postwar lows.
Goldman Sachs recently estimated Gulf exports at roughly 23 million barrels per day, close to their 2025 average, while JPMorgan estimated recent flows at close to 90% of normal prewar levels.
Saudi Arabia has also increased the use of alternative infrastructure that can move oil toward the Red Sea rather than relying entirely on the Strait of Hormuz.
As Trish discussed recently on her podcast, oil is increasingly moving even though the conflict itself remains unresolved. But while Saudi Arabia, the UAE and other Gulf producers are finding ways to get more oil onto the world market, Iran is not.
Iran of course has enormous petroleum resources. But barrels sitting underground, in storage tanks or stranded aboard tankers do not pay for imported medicine, machinery, electronics, industrial components or food.
Iran ultimately has to transform those barrels into purchasing power that the rest of the world will accept.
No dollars, no economy
This is where the U.S. dollar's status as the reserve currency of the world plays a critical role.
Despite years of efforts by Iran, China, Russia and others to reduce their reliance on the dollar, the international financial system remains overwhelmingly dollar-centric.
Global banks need access to dollars. Commodity traders demand to be paid in dollars. Shipping companies, insurers and international suppliers need access to financial institutions operating within the U.S.-led financial system.
Iran for the most part no longer has this access. U.S. sanctions have forced Tehran to develop complicated workarounds.
One of the most important involves China.
Iran can sell oil to China and effectively convert the proceeds into trade credits that can then be used to purchase Chinese goods. Such arrangements allow Iran to acquire imported products without conducting a conventional dollar-denominated transaction.
The ongoing U.S. naval blockade attacks the first link in that chain.
If Iran cannot deliver its oil, it cannot generate those credits. And if it cannot generate the credits, possessing billions of barrels of oil does little good.
Even Iranian officials have acknowledged the problem. Iran has complained that money generated through foreign trade can become trapped abroad, leaving Tehran unable to freely use those funds elsewhere.
Running out of financial oxygen
It has been just over a month since the Department of Treasury launched Operation Economic Outcast.
Treasury Secretary Scott Bessent described that launch as an "Economic D-Day" against Iran, with the objective of severing the financial and commercial networks that allow Iran to sell oil, move money, evade sanctions, procure weapons, and maintain relationships with third-country banks and intermediaries.
Bessent is essentially the architect and public face of the economic campaign. As Treasury Secretary, he is directing the use of Treasury's sanctions and financial-enforcement machinery to map Iran's networks, sanction facilitators, pressure foreign banks and governments, and threaten secondary sanctions against entities that continue doing business with Iran.
Treasury has explicitly warned that institutions helping Iran evade sanctions can be cut off from the U.S. financial system.
Our objective is to sever every economic lifeline that sustains this tyrannical regime until Tehran stands alone…. Treasury has mapped every node, every facilitator, and every network that Iran has used to smuggle oil and evade sanctions. Beginning today, the actions of Treasury and other agencies will tighten the noose and block every potential source of revenue that funds the IRGC and the Iranian regime. - Scott Bessent (8/24/2026)
Recent comments from Bessent suggest Operation Economic Outcast is working. He estimated that there are "only fifteen million more barrels of Iranian oil on the water."
Iran has so far not been completely cut off from international commerce because it entered the blockade with oil that had already left the country—cargoes sitting aboard tankers or otherwise positioned outside the effective reach of the embargo.
Those barrels could still be delivered, particularly to China, allowing Tehran to generate at least some trade credits and keep imported goods flowing. But that is a finite inventory.
As Bessent noted, Iran could soon make its final deliveries of those existing cargoes to China. Once that oil is exhausted, Iran will have a much harder time replacing it so long as the blockade prevents new barrels from leaving the country.
A deal may be getting closer
The latest diplomatic developments are particularly interesting in this context.
Iran recently proposed a seven-day confidence-building arrangement that could reopen the Strait of Hormuz and restore more normal maritime passage if certain conditions were met.
President Trump rejected the initial proposal. But the diplomacy did not stop.
The Iranian Foreign Minister has reportedly now received formal U.S. feedback on the plan through Qatari mediators. According to reports, discussions are increasingly focused on the sequencing of various steps—who does what first—rather than simply whether negotiations should occur at all.
Throughout this whole ordeal, Iran's most valuable bargaining chip has been its ability to disrupt traffic through the Strait of Hormuz. Now that its ability to actually stop traffic is rapidly declining, Tehran appears to be negotiating over the circumstances under which that rapidly depreciating leverage could be surrendered.
Something eventually has to give
There are still plenty of reasons oil could remain expensive. Negotiations could collapse. Iran could escalate. Shipping infrastructure could again come under attack.
But the physical oil market is adapting. Gulf exports are recovering, alternative transportation routes are being used more aggressively, and the economic pressure on Tehran continues to build.
Since February, Iran has managed to impose significant costs on the rest of the world by disrupting the Strait of Hormuz. Increasingly, however, Iran is paying an even heavier price itself.
With access to foreign goods, hard currency and export revenues steadily tightening, Iran is in fact the country facing the most acute economic strain, contrary to the message to American voters.
It is possible the regime can hold out through the midterms. But the longer the confrontation continues, the more difficult its position becomes.
Something eventually has to give. And when it does, oil prices have the potential to fall sharply with it.
Investing for the Opportunities Ahead
The Iran situation illustrates an important principle that guides our investment approach at 76research.
Geopolitical uncertainty can create major short-term market disruptions, but it can also produce exceptional long-term investment opportunities.
Rather than attempt to predict every political development or market fluctuation, we focus on identifying companies that can prosper across a range of economic environments.
We are particularly optimistic about the long-term prospects of the American economy.
The United States remains the global leader in artificial intelligence, advanced computing, financial innovation and many other strategically important industries. At the same time, efforts to strengthen domestic manufacturing, expand energy production and modernize infrastructure could create investment opportunities across a much broader range of businesses.
We also believe investors should be mindful of valuation, inflation, interest rates and the growing concentration of major stock market indexes in a relatively small number of technology companies.
Even when the overall market outlook is favorable, not every investment is equally attractive.
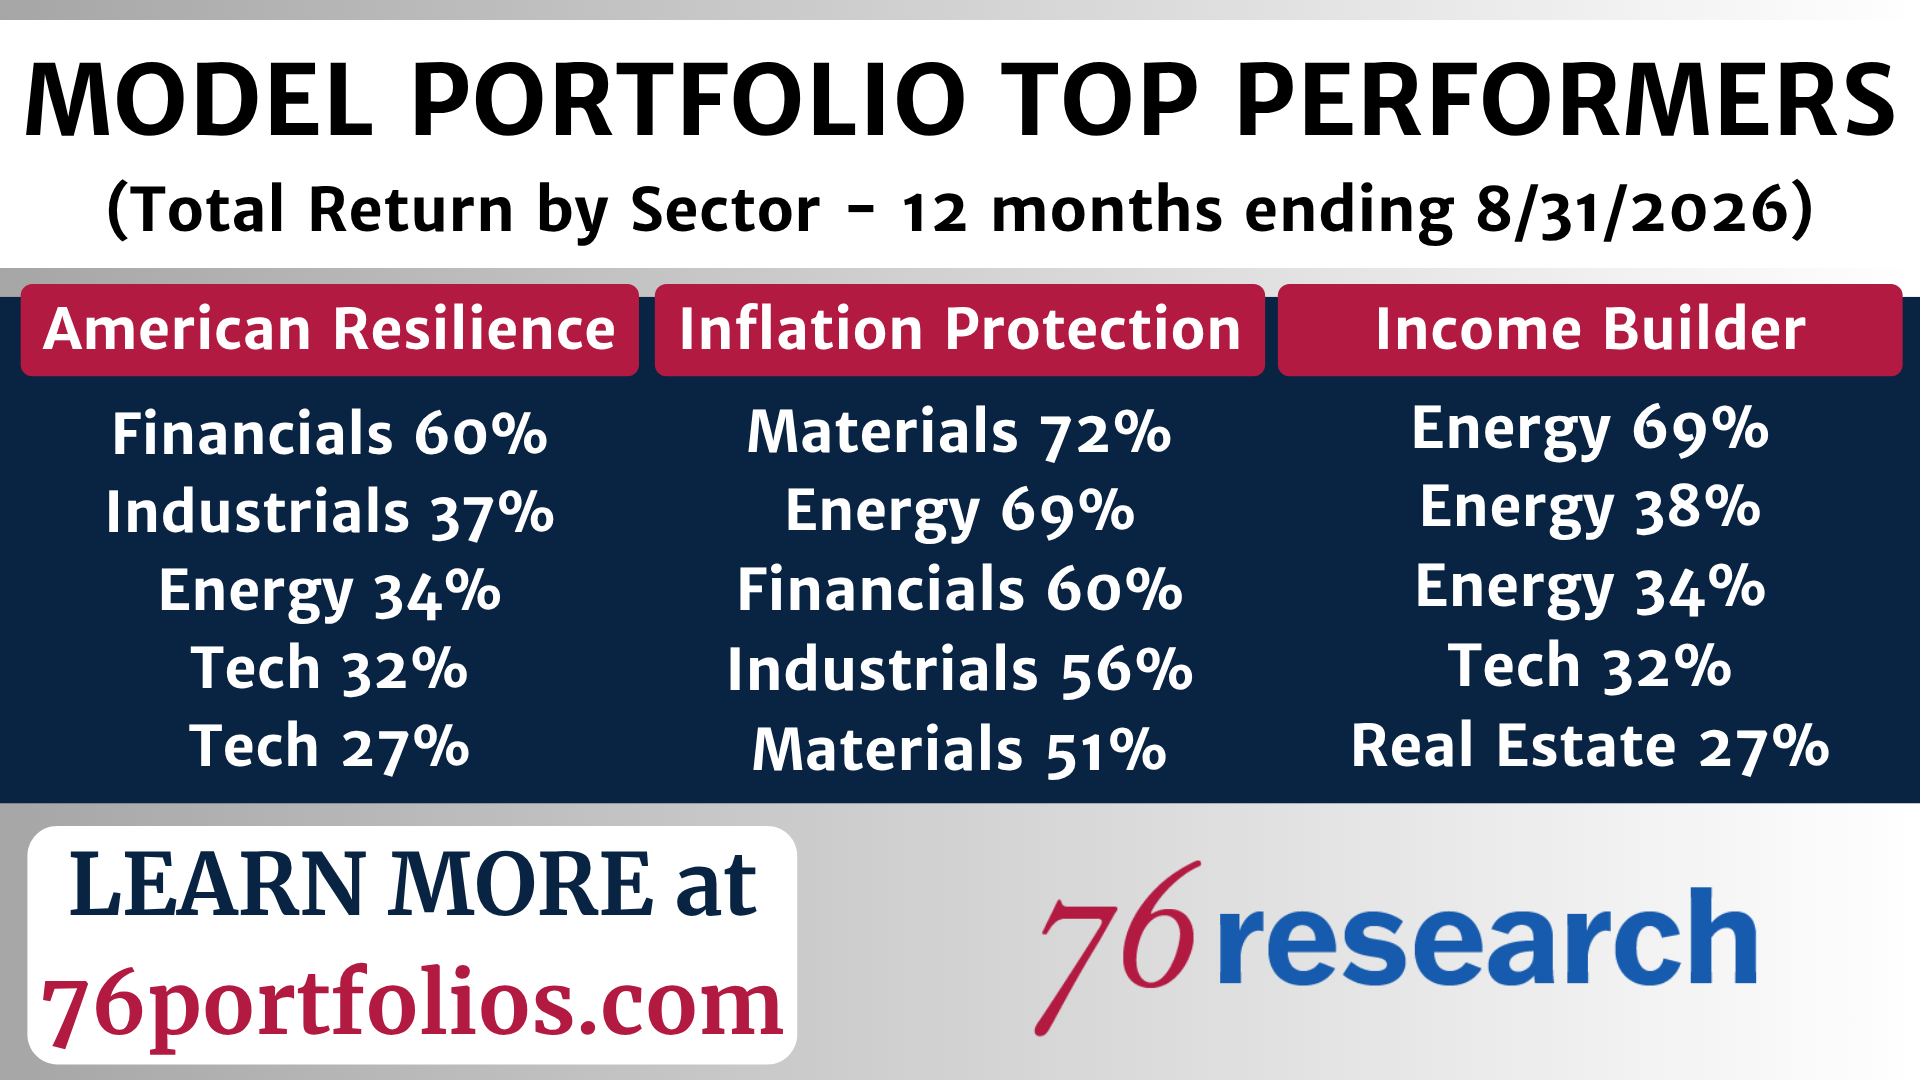
This is why we have developed three actively managed Model Portfolios, each designed to address a different set of investment objectives.
Our Model Portfolios
Our flagship growth-oriented portfolio focuses on high-quality businesses positioned to benefit from America's long-term competitive advantages. These include opportunities tied to artificial intelligence, industrial technology, domestic investment and other secular growth trends.
A portfolio designed to help investors maintain purchasing power over time, with exposure to companies and real assets that we believe are positioned to perform well in an environment of persistent inflationary pressures and monetary debasement.
A portfolio focused on generating attractive investment income while maintaining the potential for long-term capital appreciation. We seek opportunities across dividend-paying stocks, real estate, infrastructure and other income-producing securities.
Each portfolio provides specific investment recommendations, ongoing research, and regular updates explaining how changing market conditions affect our investment outlook.
Learn more about our Model Portfolios at 76portfolios.com.