The stock market does not quite know how to feel about the overwhelming success of Democrats in Tuesday’s midterm elections.
On Tuesday evening, futures markets dipped after the results came in, particularly the tech-heavy NASDAQ Composite, which fell around 2%.
Then on Wednesday, the stock market rallied sharply. The S&P 500 gained 1.6%, while the NASDAQ advanced 1.4%.
But Thursday brought a stunning reversal.
The NASDAQ plunged 5.5%, the S&P fell 4.4%, and the Philadelphia Semiconductor Index fell 12.3%. Shares of NVIDIA (NVDA) declined approximately 9%, while many other companies associated with the AI boom suffered significant losses.
As we explained in the 76report, which we released just before the market opened on Thursday (The Midterm Shock: What Comes Next for Markets), investors at first appeared to welcome the prospect of political gridlock in Washington.
They also liked what the election meant for the trajectory of oil.
To a large extent, the midterms were seen as a referendum on the Iran war, which is unpopular because of its impact on oil prices. Investors are now optimistic about a potentially accelerated resolution to the conflict.
But AI-related stocks have faced a number of headwinds in recent weeks, including lingering questions about their aggressive plans for capital expenditures (see The Great Free Cash Flow Debate, which we published on October 30, 2026).
Investors now have another reason to worry: the possibility that the midterm elections will translate into political restrictions that derail the AI infrastructure boom.
We appreciate these concerns. The hostile rhetoric coming from many politicians is alarming.
But we also believe the political headwinds are manageable and even present some silver linings, especially in the context of free cash flow questions.
While there is potential for credit market distress in some corners, the tech sector in general is well-capitalized. Credit markets today have barely responded to the equity market volatility.
AI infrastructure cap ex has been a critical growth driver for the American economy. By some estimates, it has accounted for about half of all GDP growth in recent periods.
A potential slowdown might not only improve the already strong financial profile of the large hyperscalers (because they will be spending less), it could set the stage for rate cuts and easier monetary policy that would likely offset any credit-related pressures.
We believe long-term investors should view the current volatility opportunistically. The focus should be on players with strong balance sheets and in-place assets that may actually become more valuable if political forces curtail capacity expansion.
Trouble in Texas
One of the most surprising developments Tuesday night was the defeat of Republican Governor Greg Abbott in Texas, who was strongly favored in prediction markets, notwithstanding the challenges facing the Republican Senate candidate Ken Paxton.
His Democratic opponent, Gina Hinojosa, campaigned on imposing a moratorium on new data center approvals until stronger protections are established for local communities.
This is potentially significant because Texas has emerged as the epicenter of America's AI infrastructure boom.
With abundant energy resources, inexpensive land, and a historically favorable business environment, the state accounts for approximately 25% of planned US data center capacity.
The election outcome therefore introduces considerable uncertainty surrounding billions of dollars in anticipated investments.
But the backlash is not limited to Texas—or to Democrats.
In fact, Abbott himself had already ordered a temporary halt to new data center permits while state agencies evaluate their electricity and water requirements.
And across the country, voters in dozens of communities approved restrictions on data center development Tuesday.
The pros and cons of AI
The underlying concerns about AI data centers are understandable, although in our assessment, often overstated.
Residents often worry about rising electricity bills, water consumption, environmental consequences, and the potential for AI to eliminate jobs. Interest groups associated with the so-called “doomer” movement have fueled this anxiety.
Opposition to AI infrastructure has become a bipartisan political issue. Yet the AI industry has arguably done a poor job countering its critics in the public relations battle.
For example, data center developers are increasingly investing in dedicated power generation and infrastructure, potentially expanding electricity supplies rather than simply competing with residents for existing capacity.
Additional generation and better utilization of the electrical grid often reduces electricity costs for consumers.
Concerns about water consumption also tend to be exaggerated. Modern closed-loop cooling systems continuously recycle water, much like the cooling system in a car engine, dramatically reducing consumption. Some facilities use less water than a typical golf course.
It is worth noting that campaign rhetoric is not the same as enforceable regulation.
Texas in particular has a decentralized regulatory structure, with commissioners serving staggered terms. The incoming governor cannot simply replace the regulatory apparatus overnight. Major new legislation would require cooperation from the Republican-controlled state Senate.
Political resistance could slow construction, but an outright shutdown of the industry's expansion would be much more difficult to accomplish.
There are also powerful countervailing forces.
Maintaining American technological leadership over China is a national security priority, creating substantial incentives for policymakers to accommodate AI development.
There is also the reality that data centers create significant economic growth and often high-paying jobs. If one state or county wants to restrict growth, another one might not. The United States encompasses more than 3.5 million square miles of land.
Supply and demand dynamics
There is another important distinction that investors should recognize. Restrictions on the supply of AI computing capacity do not reduce the underlying demand for intelligence.
If businesses and consumers continue discovering valuable applications for AI, the economic incentives to expand computing capacity will remain enormous.
Projects can potentially be relocated, alternative electricity arrangements developed, and additional costs absorbed.
But even where restrictions genuinely constrain new supply, the resulting scarcity could increase the economic value of existing infrastructure.
Companies with operational data centers, secured electricity supplies, and substantial installed computing capacity may actually become more valuable.
Political restrictions could therefore create winners as well as losers, even within the AI industry itself.
The free cash flow paradox
Just last week, we examined growing investor concerns that the hyperscalers were spending too aggressively on AI infrastructure.
Companies like Microsoft (MSFT), Alphabet (GOOGL), Amazon (AMZN), and Meta Platforms (META) are committing extraordinary sums to data centers and computing equipment.
While earnings continue growing, this massive spending has put considerable pressure on free cash flow.
It is somewhat ironic that investors are now worried that politicians may prevent these companies from spending so much.
But what if slowing the AI infrastructure buildout actually improves the financial position of the hyperscalers?
If regulatory obstacles force companies to postpone planned investments, their near-term capital expenditures could decline.
All else equal, that would mean higher free cash flow.
And much of the infrastructure that might be delayed was not expected to generate meaningful revenue immediately anyway.
This is especially relevant for companies like META, whose existing advertising operations generate enormous cash flows and may be relatively insulated from delays in future data center construction.
There is even the possibility that external constraints could impose some useful capital discipline, preventing companies from overbuilding and allowing demand to catch up with existing capacity.
A slowdown in AI capital spending is not necessarily bad news for the companies making those investments, which are being judged as much on free cash flow burn as earnings growth.
It may, however, be considerably more problematic for the companies supplying the equipment, electricity, and construction services, although many of these companies report an inability to meet current levels of demand anyway.
In the near-term, we do not expect projects that have already been authorized and are underway to encounter significant restrictions. The concern is more around new project authorizations in the years ahead.
What comes next?
We do not dismiss the political threat to AI. Regulatory obstacles could slow the buildout, raise costs, and reduce the returns available to some participants.
The implications could be particularly challenging for highly leveraged infrastructure developers and companies dependent on an uninterrupted expansion of capital spending.
But the demand for intelligence has not suddenly disappeared because Democrats were elected. And there are powerful economic and national security incentives to ensure that the United States continues advancing its AI capabilities.
AI data centers have become controversial for various reasons, but do Democrats really want to be the party that extinguished America’s most important driver of economic growth?
Some Democrats may relish that opportunity, but it remains to be seen how much support voters will ultimately give them. And we witnessed on Tuesday just how sensitive the American public is to policies that hurt them economically.
The AI revolution can remain extraordinarily successful even if the pace of infrastructure investment slows—and even if some companies earn disappointing returns along the way.
For investors, the crucial distinction is between the long-term economic potential of AI and the profitability of individual companies participating in the boom.
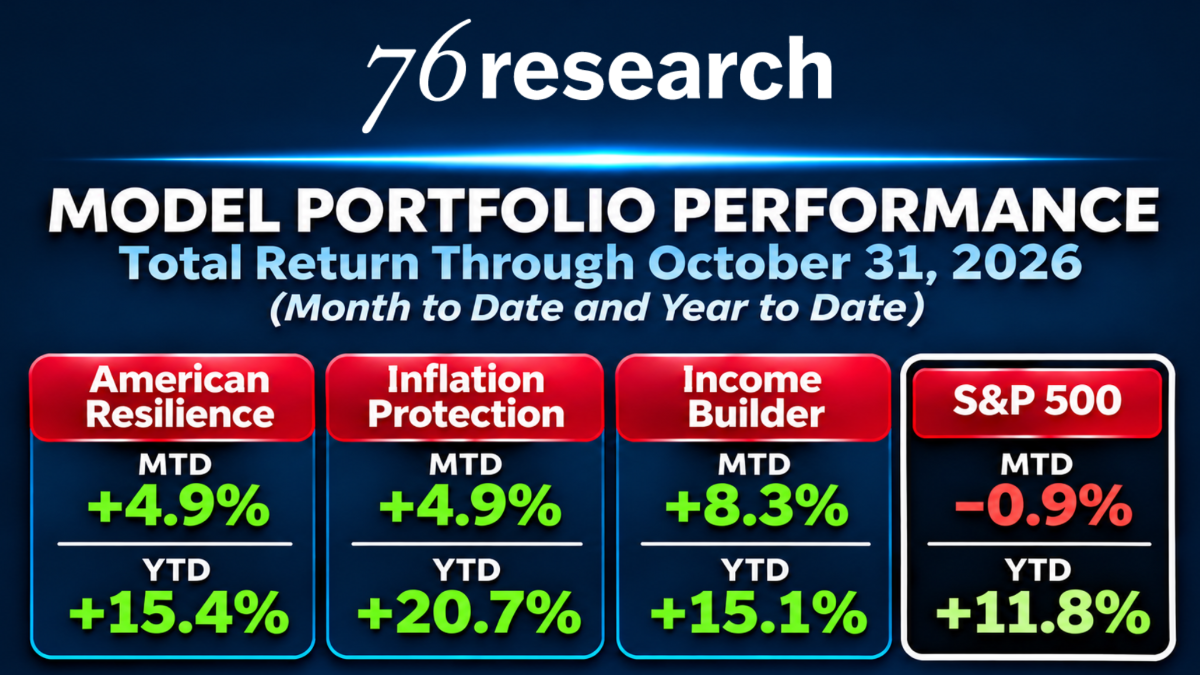
We recommend investors selectively take advantage of current volatility to increase exposure to businesses that are likely to emerge as long-term winners in this technological revolution, including the AI-oriented holdings we have discussed in our Model Portfolio research.