| Income Builder Model Portfolio |
|
| Monthly Portfolio Review: October 2026Publication date: November 2, 2026 |
|
| | | Current portfolio holdings |
|
|
| | FOR SUBSCRIBER USE ONLY. DO NOT FORWARD OR SHARE. |
|
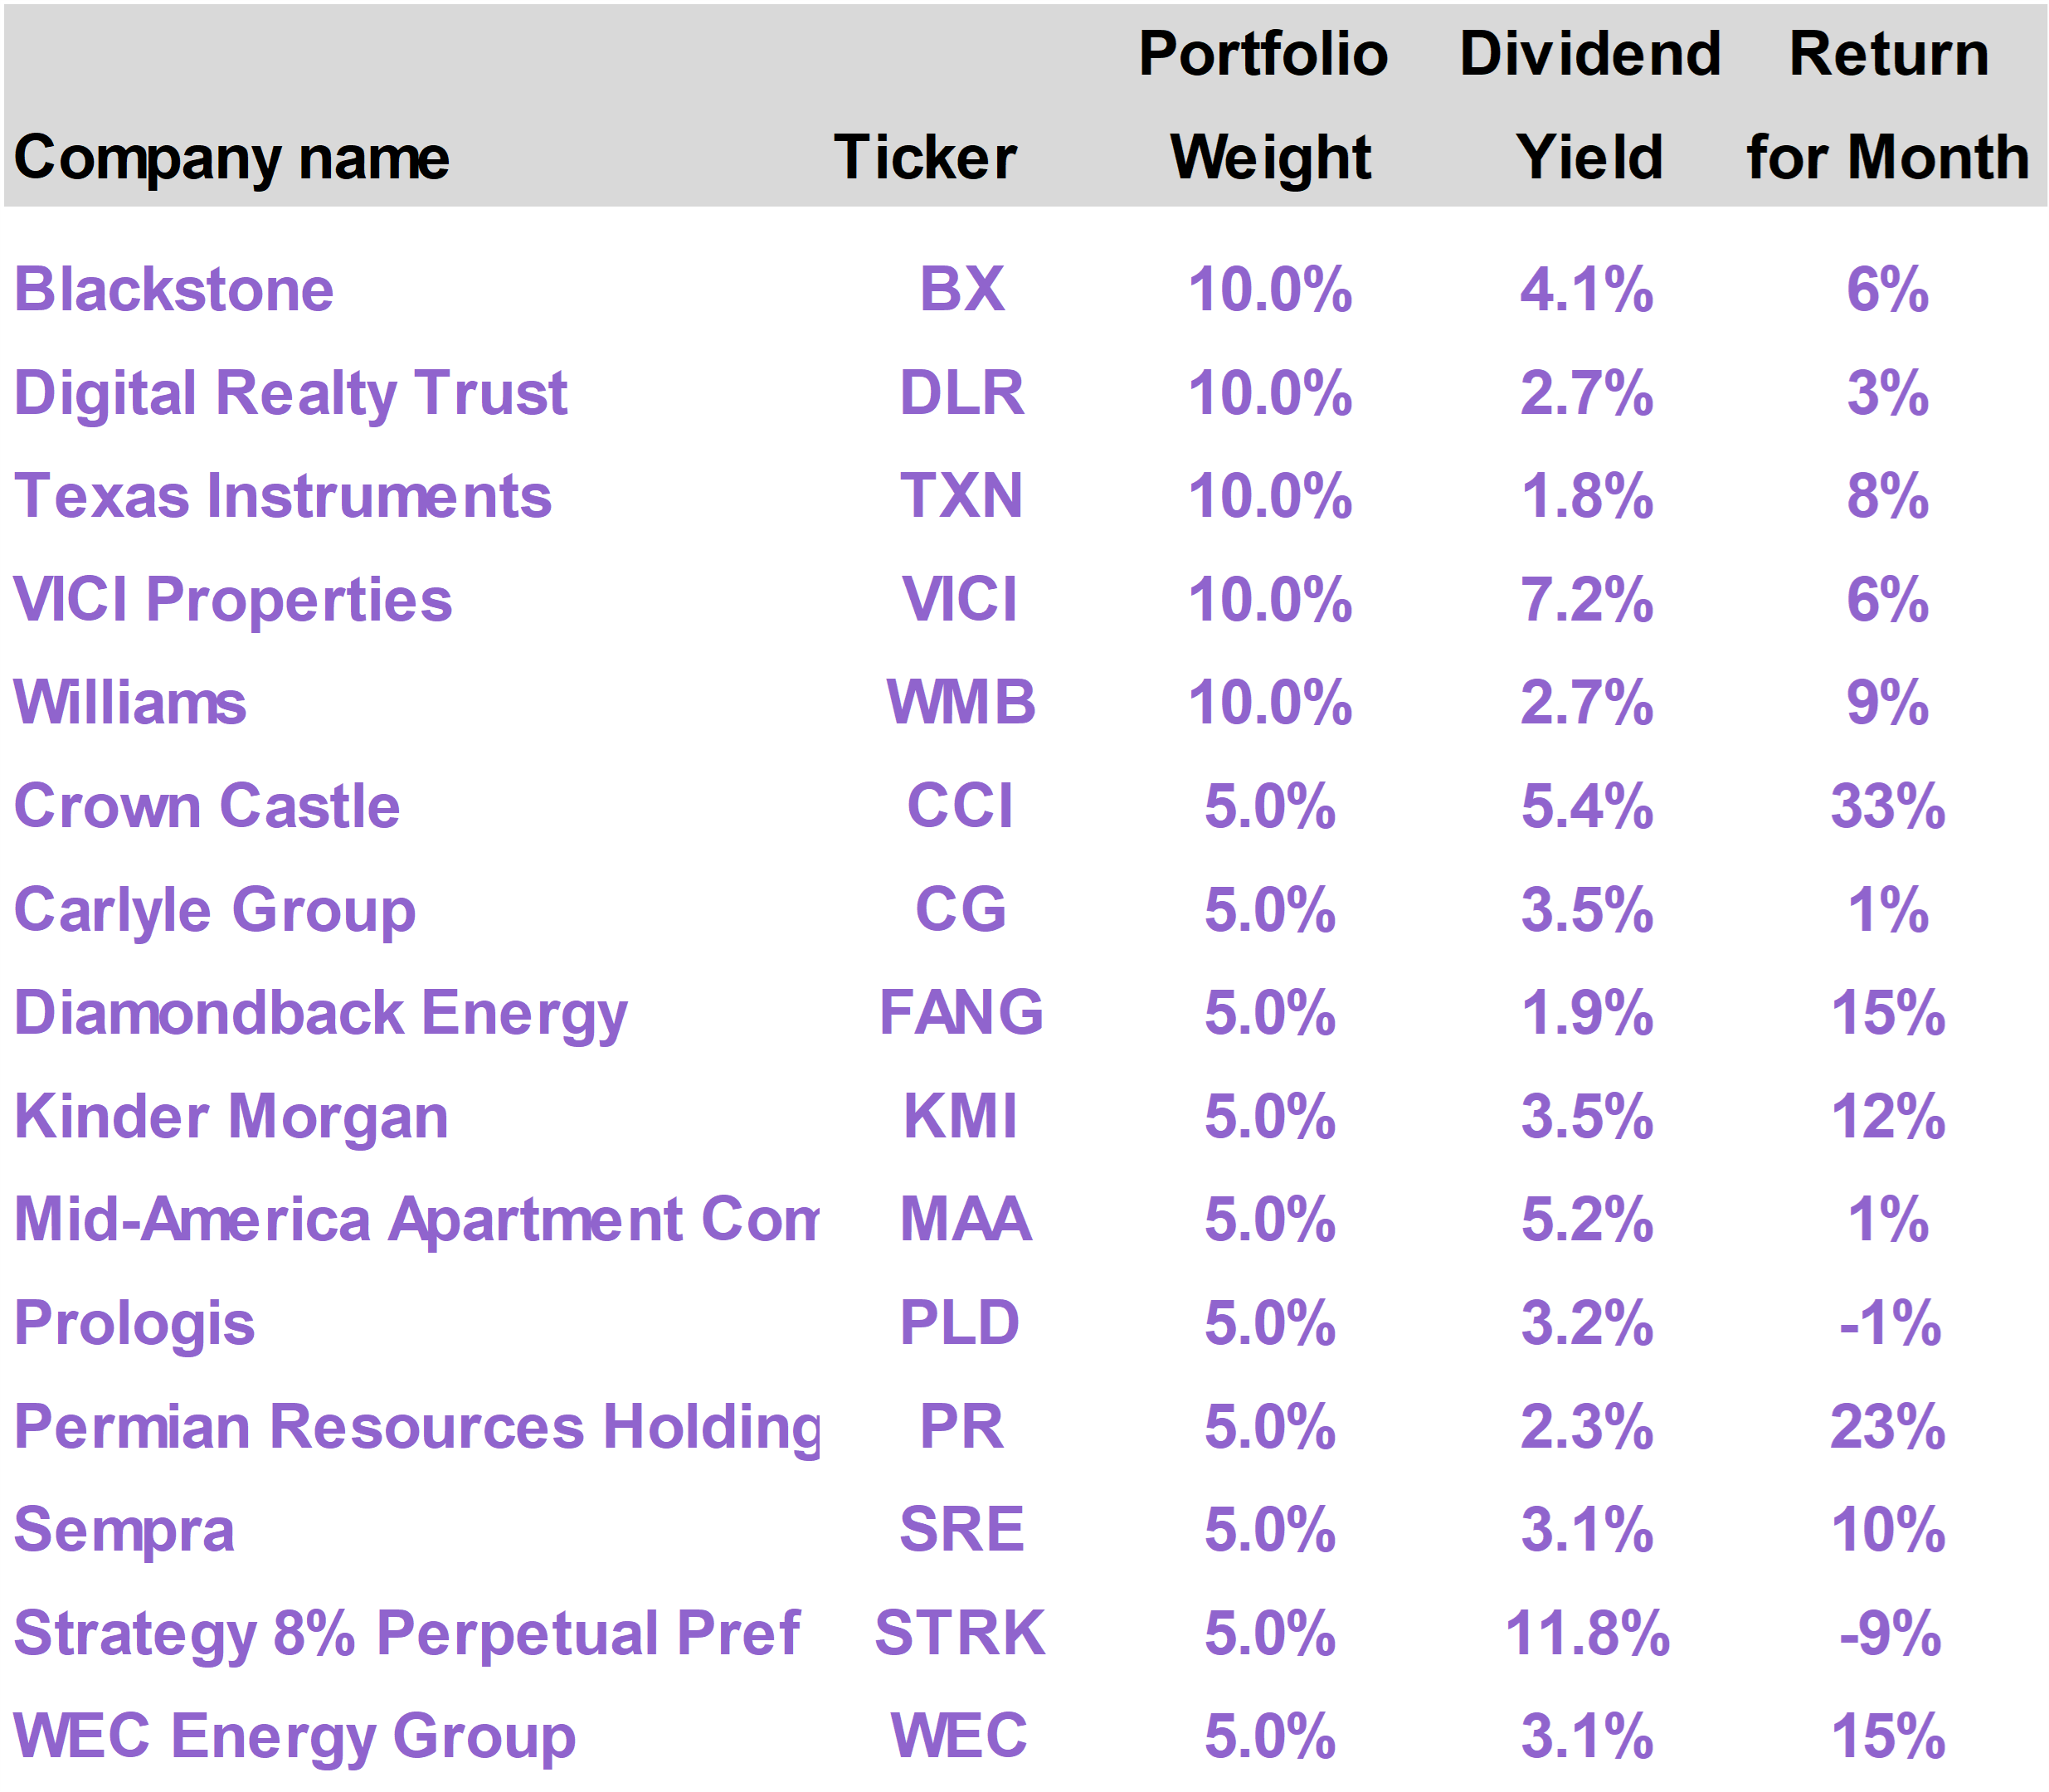
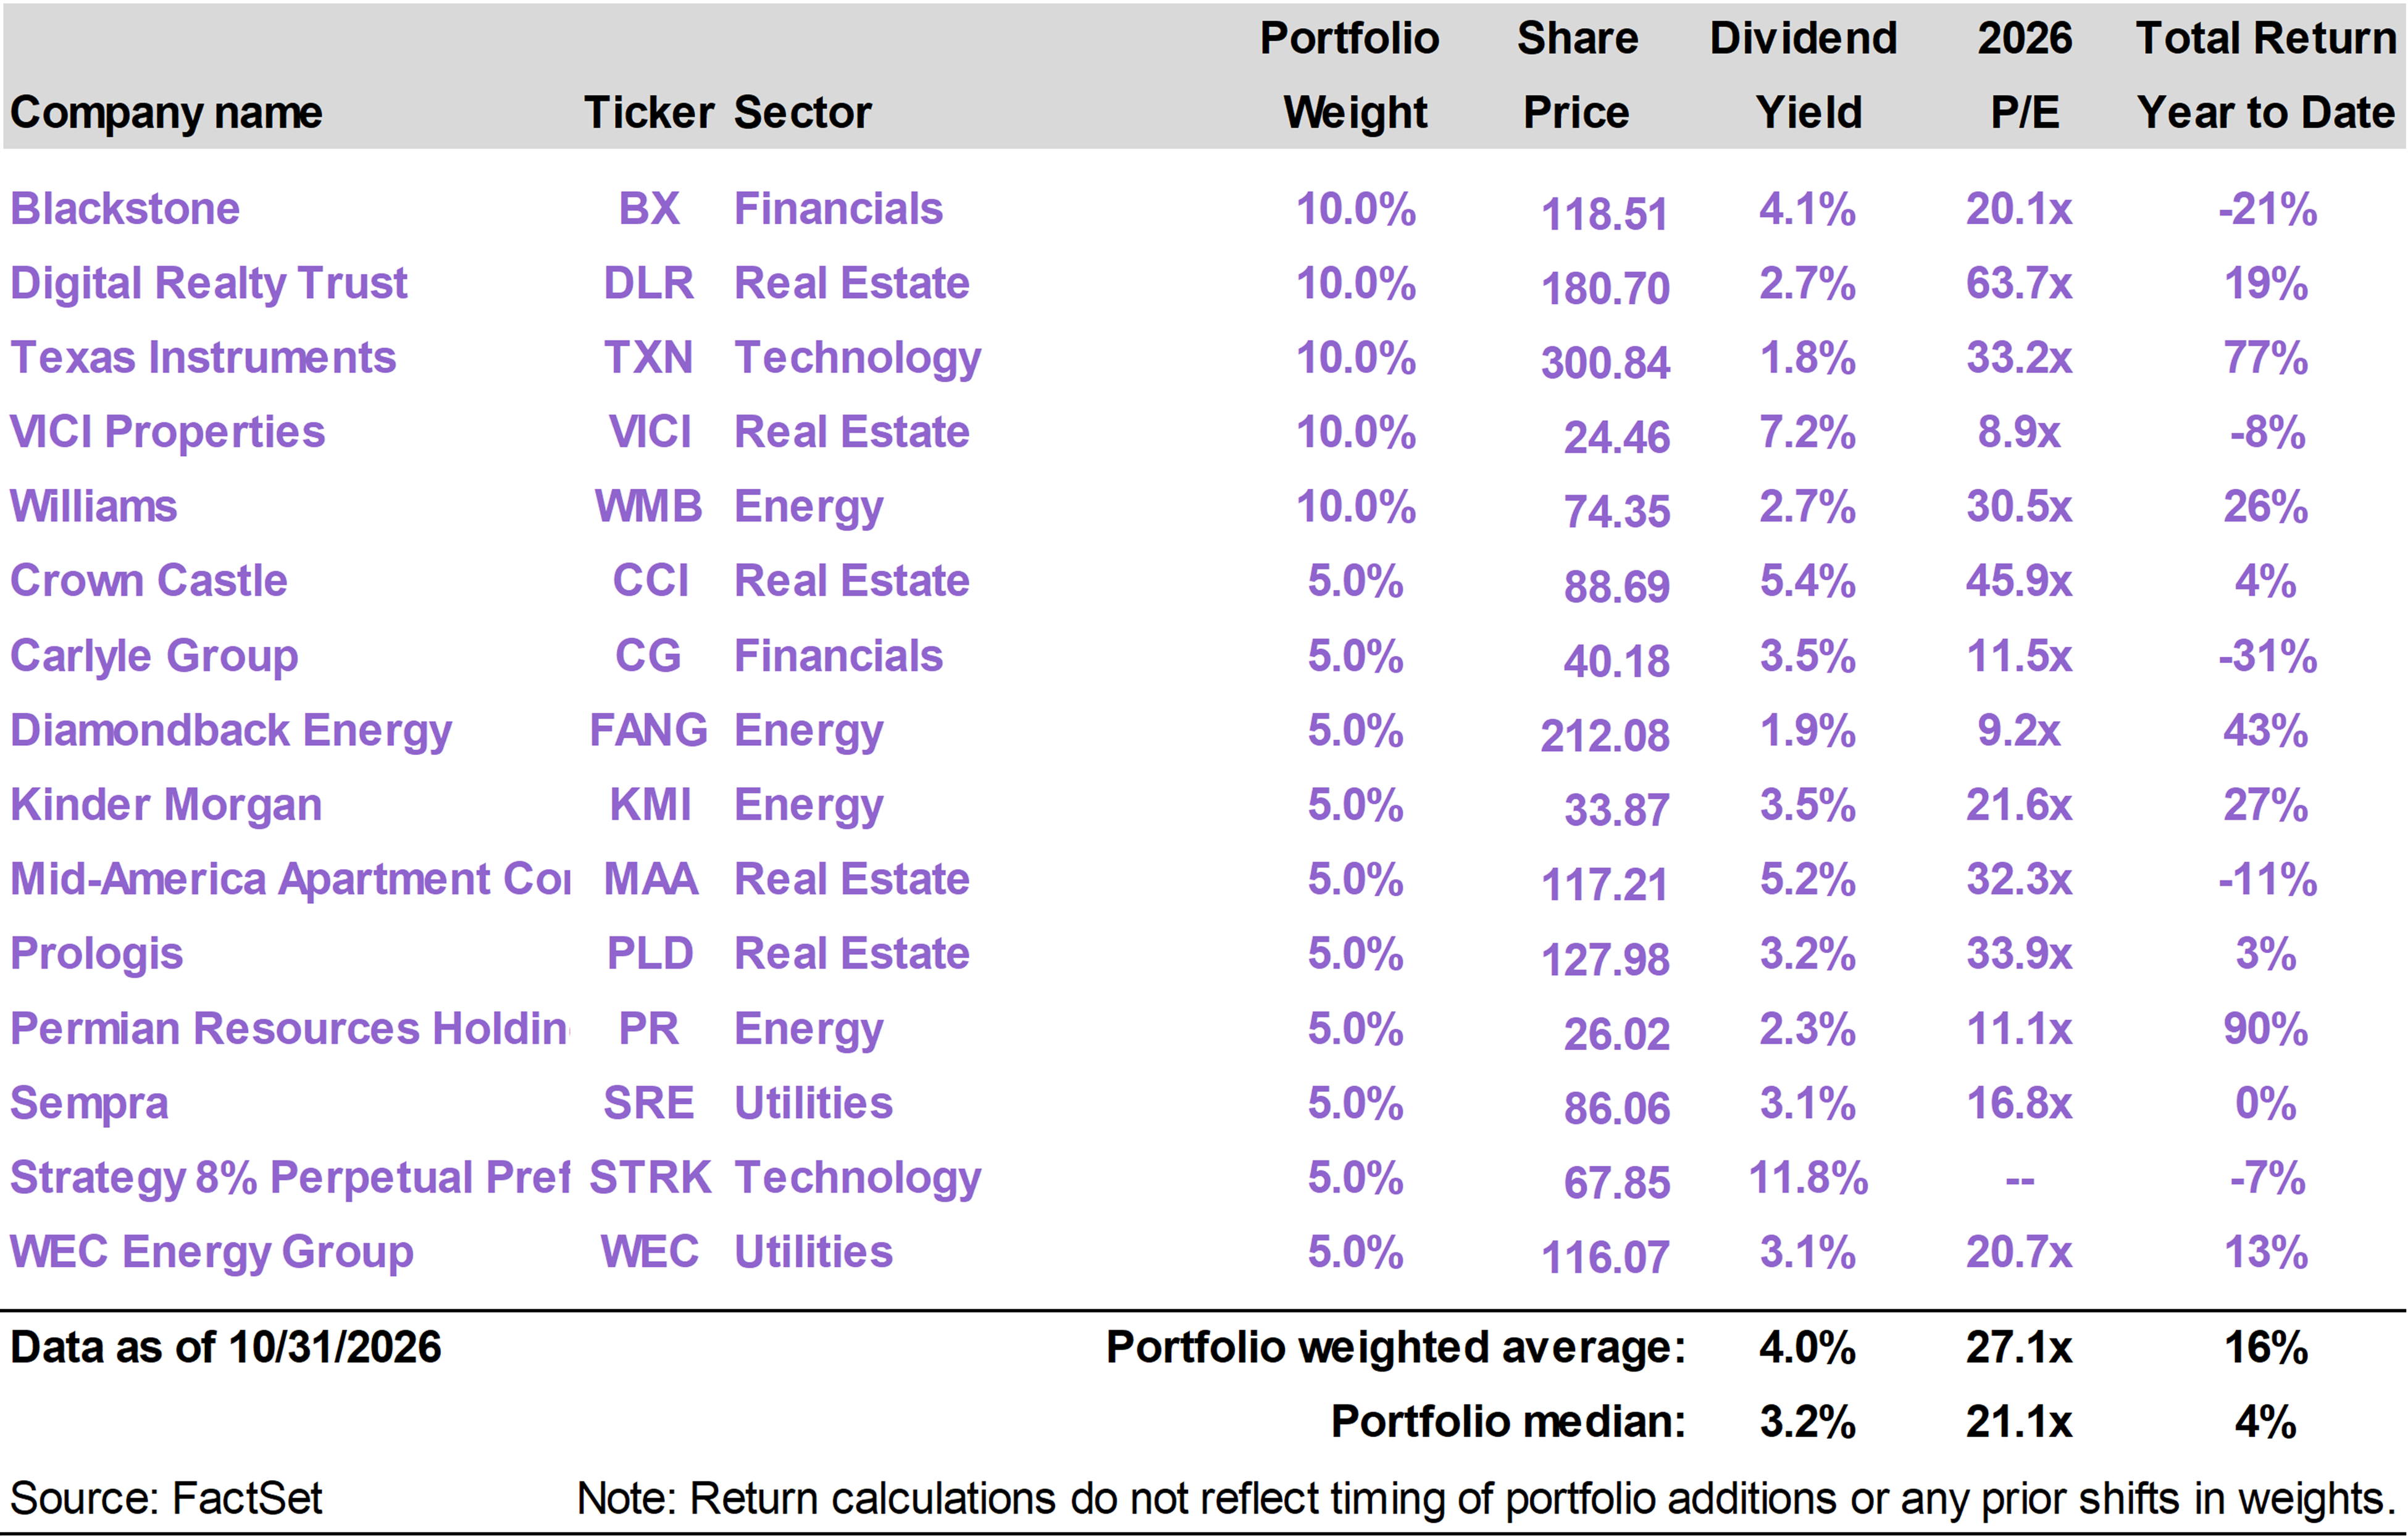
| | | October brought a sharp recovery in income-oriented stocks, as long-term interest rates retreated and investors rotated away from the AI trade. The S&P 500 declined 0.9%, while the NASDAQ Composite fell 5.3%, pressured by declining free cash flow in the Technology sector. Utilities, Real Estate, and Energy stocks performed particularly well, supported by falling bond yields and elevated oil prices. The Income Builder portfolio substantially outperformed in October, delivering an 8.3% total return. On a year to date basis, the portfolio's total return is 15.1%, versus 11.8% for the S&P 500. Crown Castle (CCI) led the portfolio with a 33% gain, benefiting from the potential for new business from SpaceX (SPCX). Strategy 8% Perpetual Preferred (STRK) gave back its September gains amid renewed weakness in Bitcoin, but we are encouraged by the transition to daily dividends, which shareholders have approved. We are constructive on the outlook for the portfolio, particularly as lower long-term interest rates could support further valuation recovery. We remain focused on delivering an attractive combination of current income, long-term growth potential, and diversification across economic outcomes.
|
|
| | |
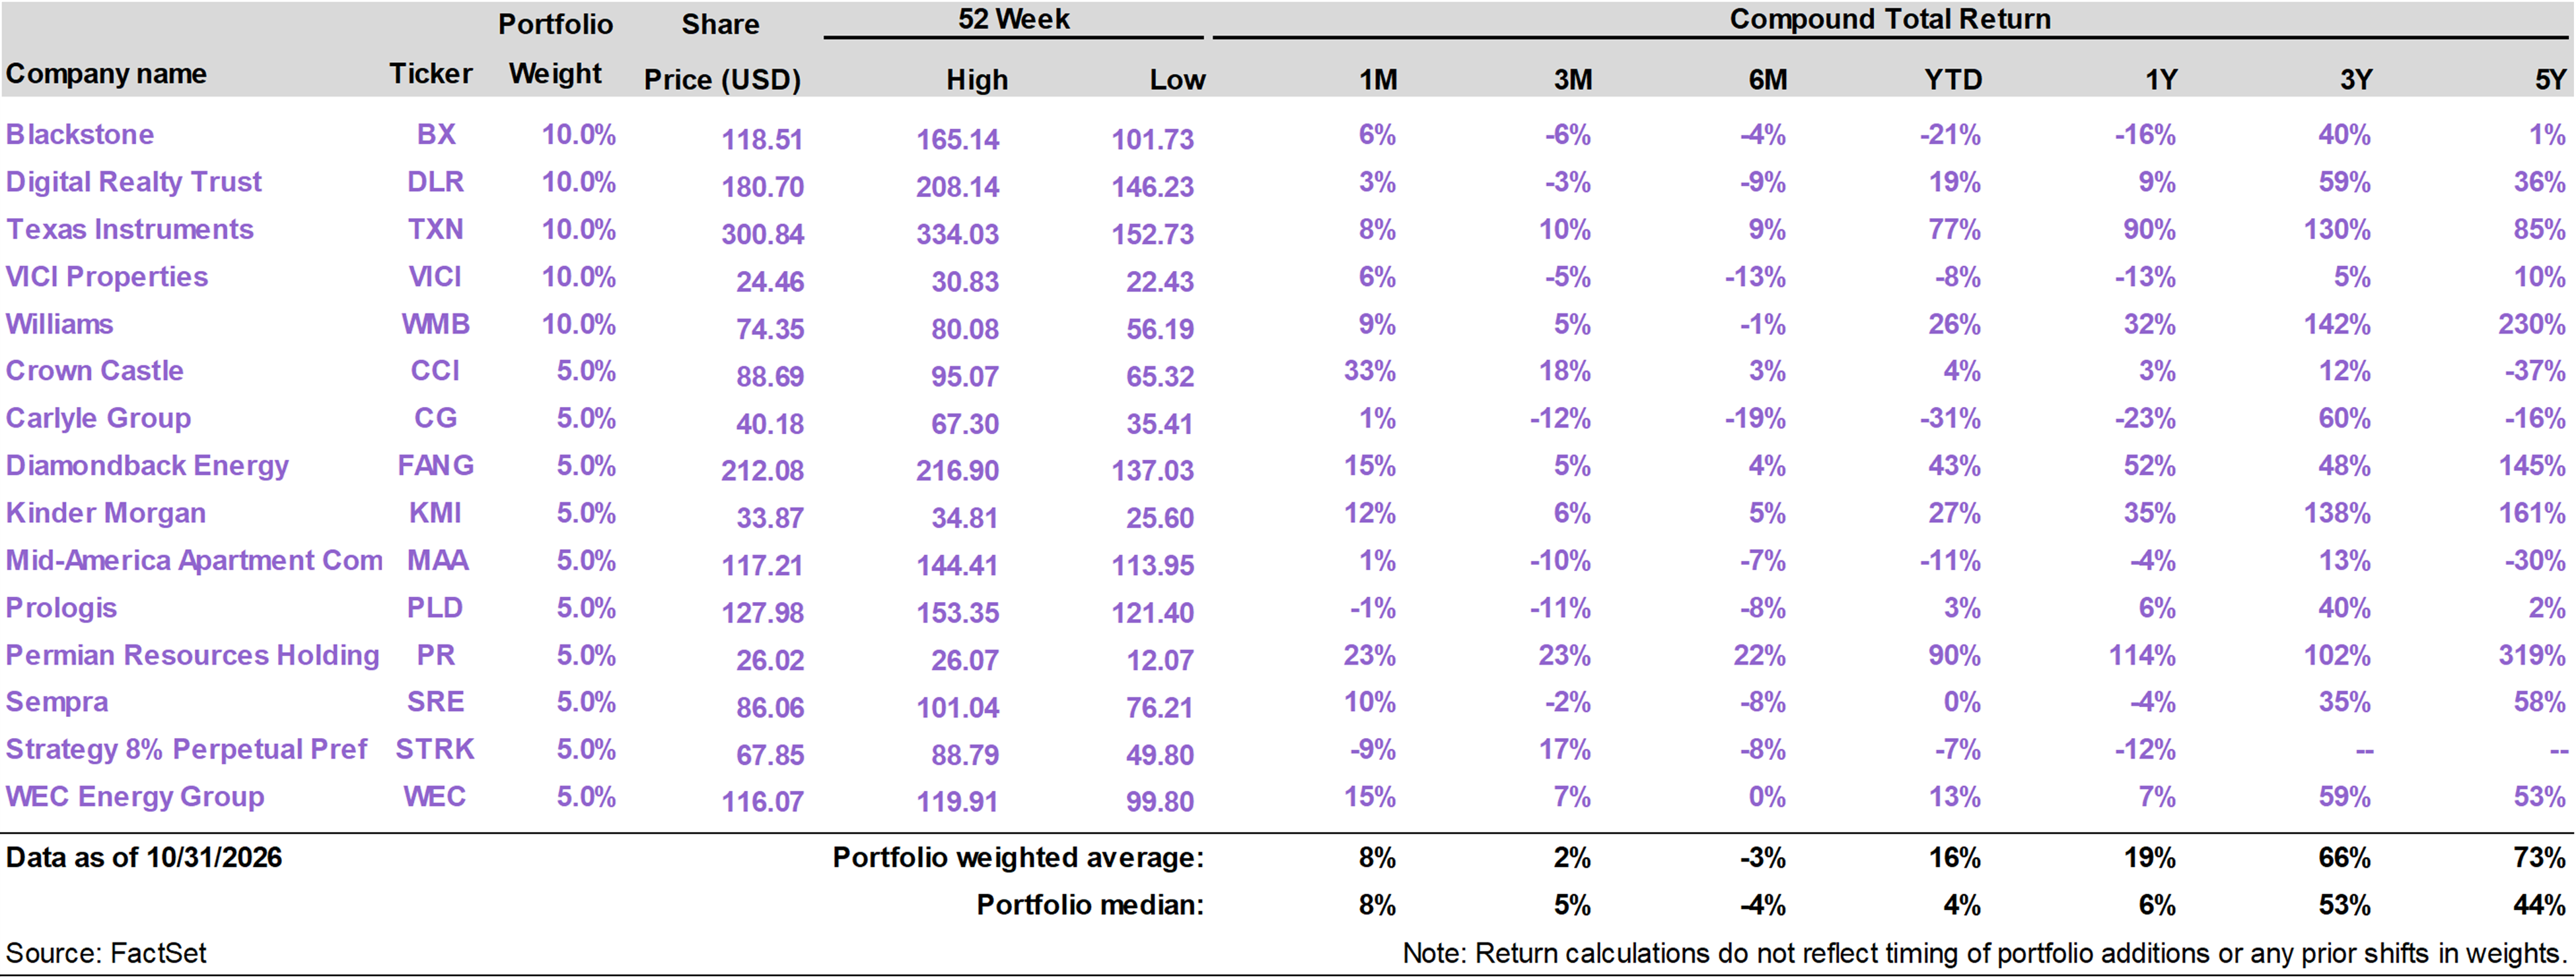
The Income Builder portfolio generated a total return of 8.3% in October, versus the S&P 500 Index return of -0.9%. On a year to date basis through the end of the month, the portfolio has returned 15.1%, versus the 11.8% return of the S&P 500.
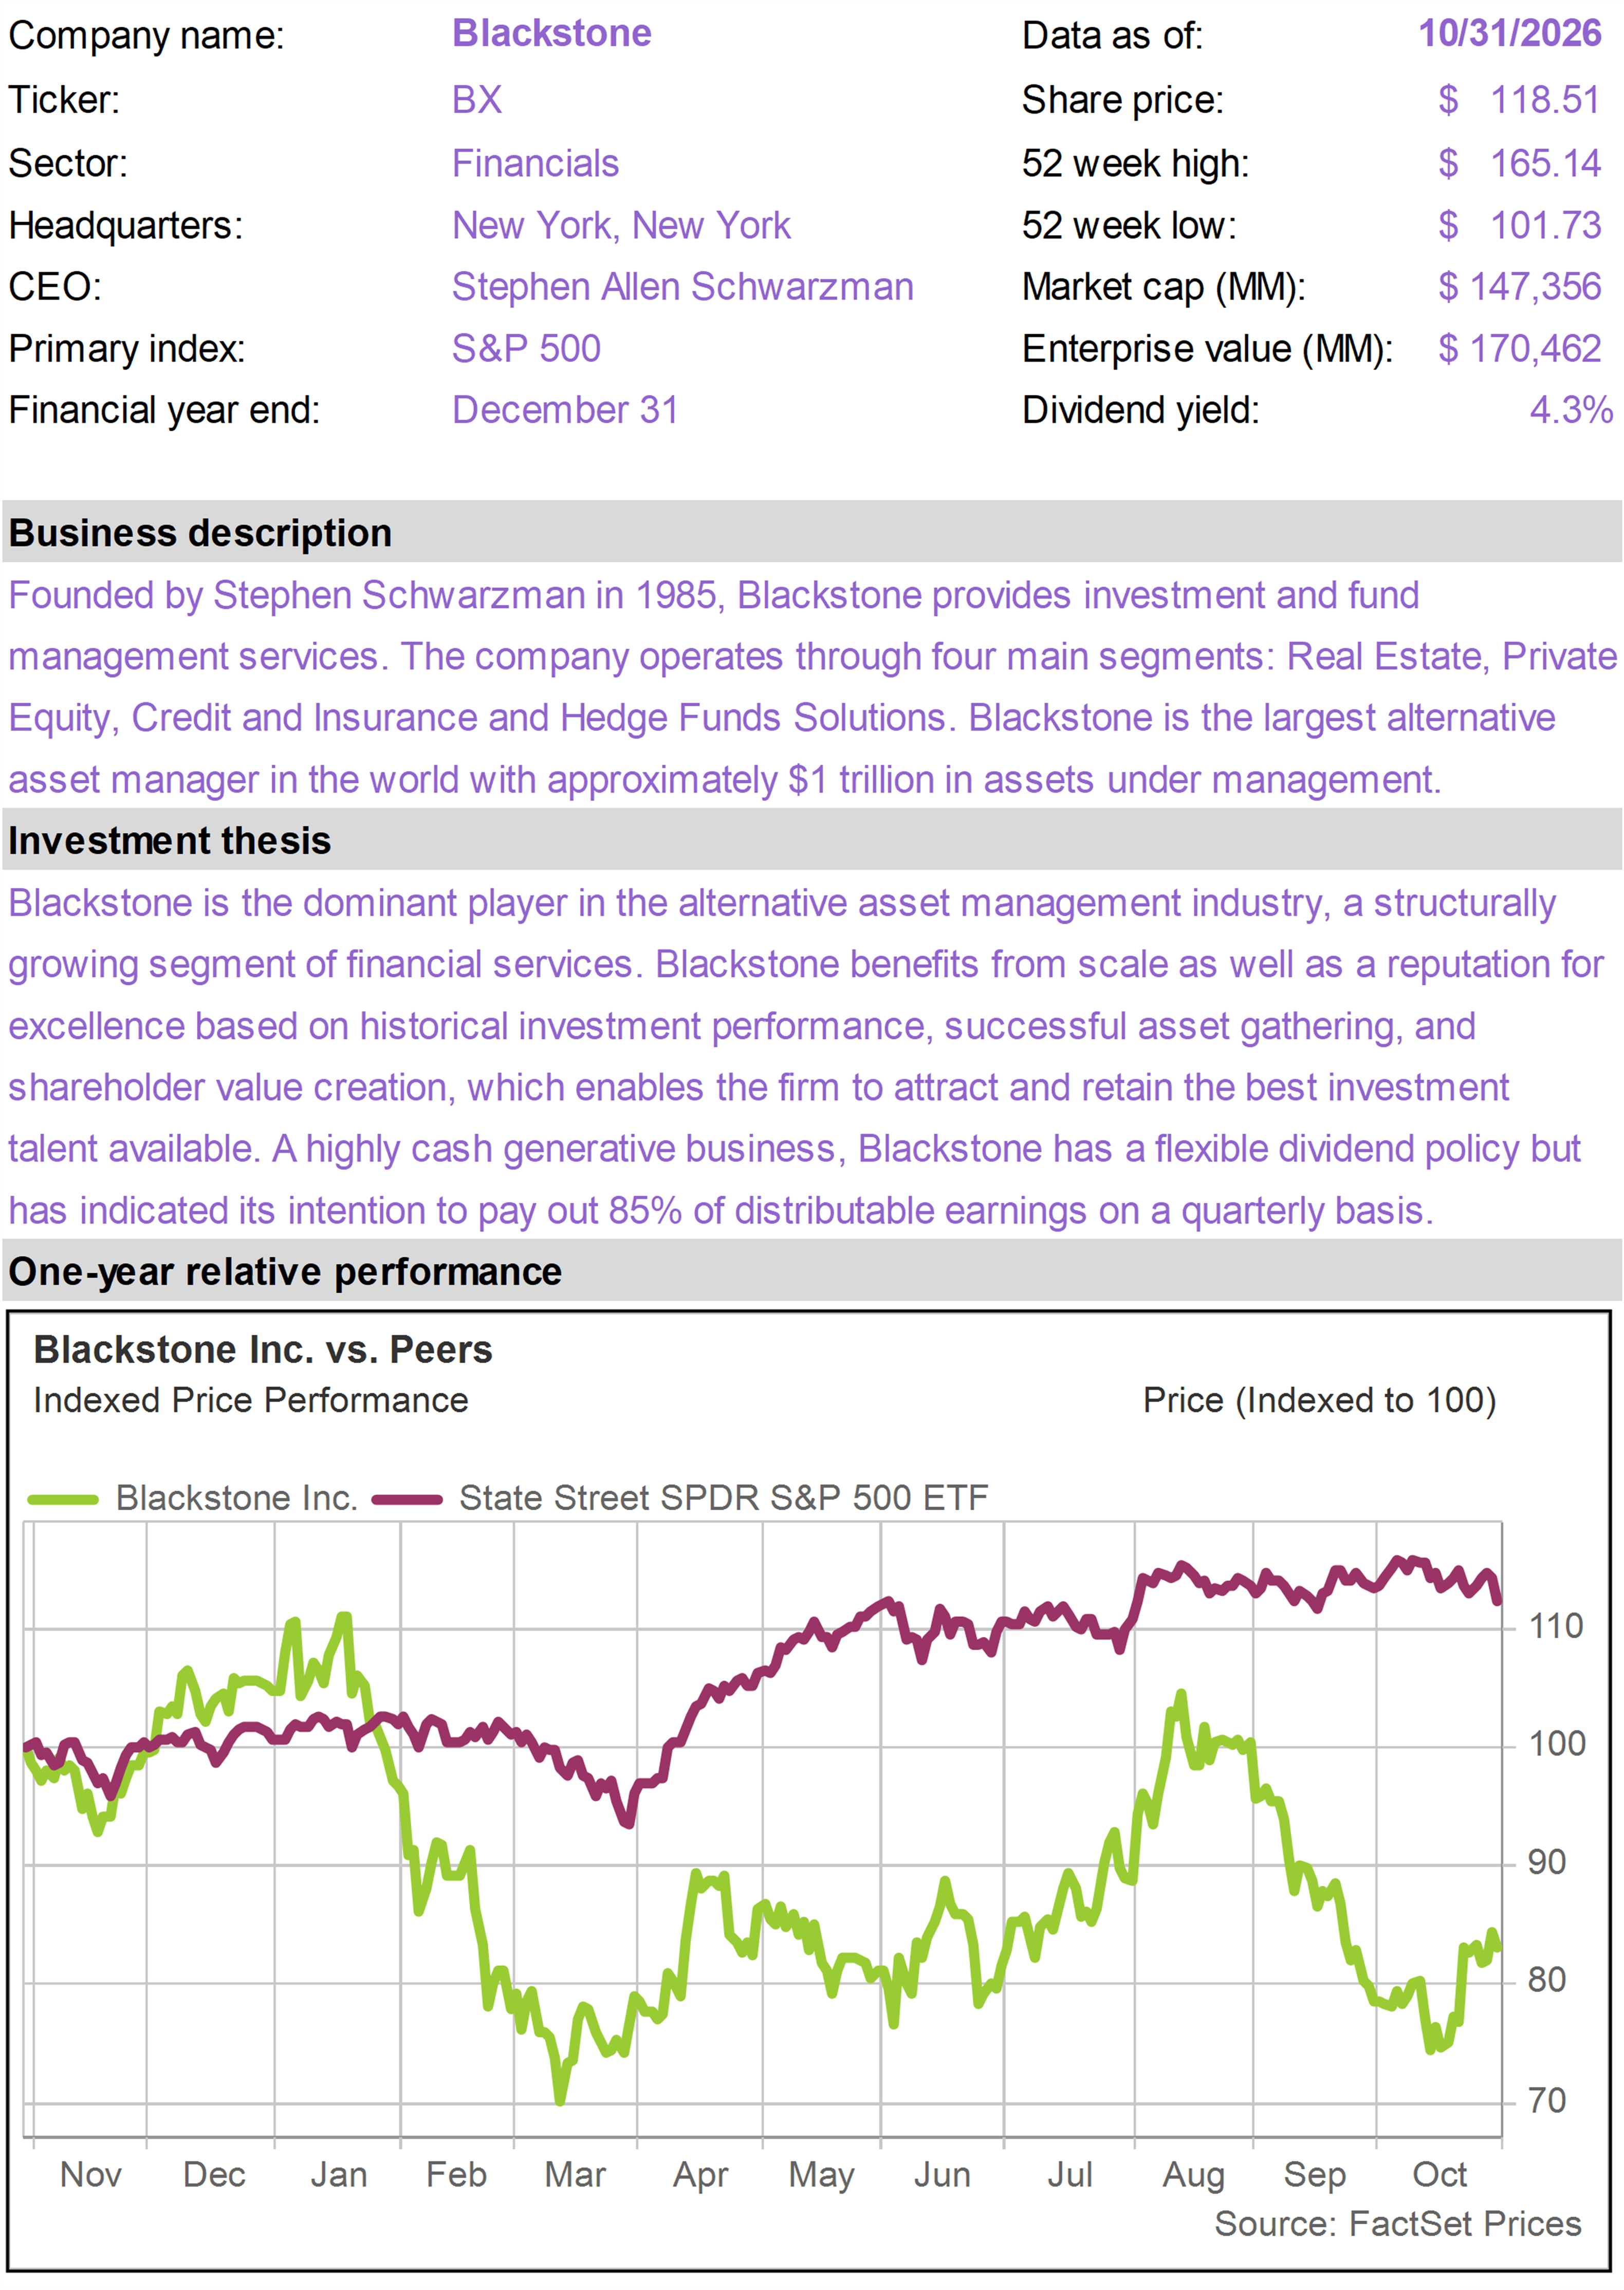
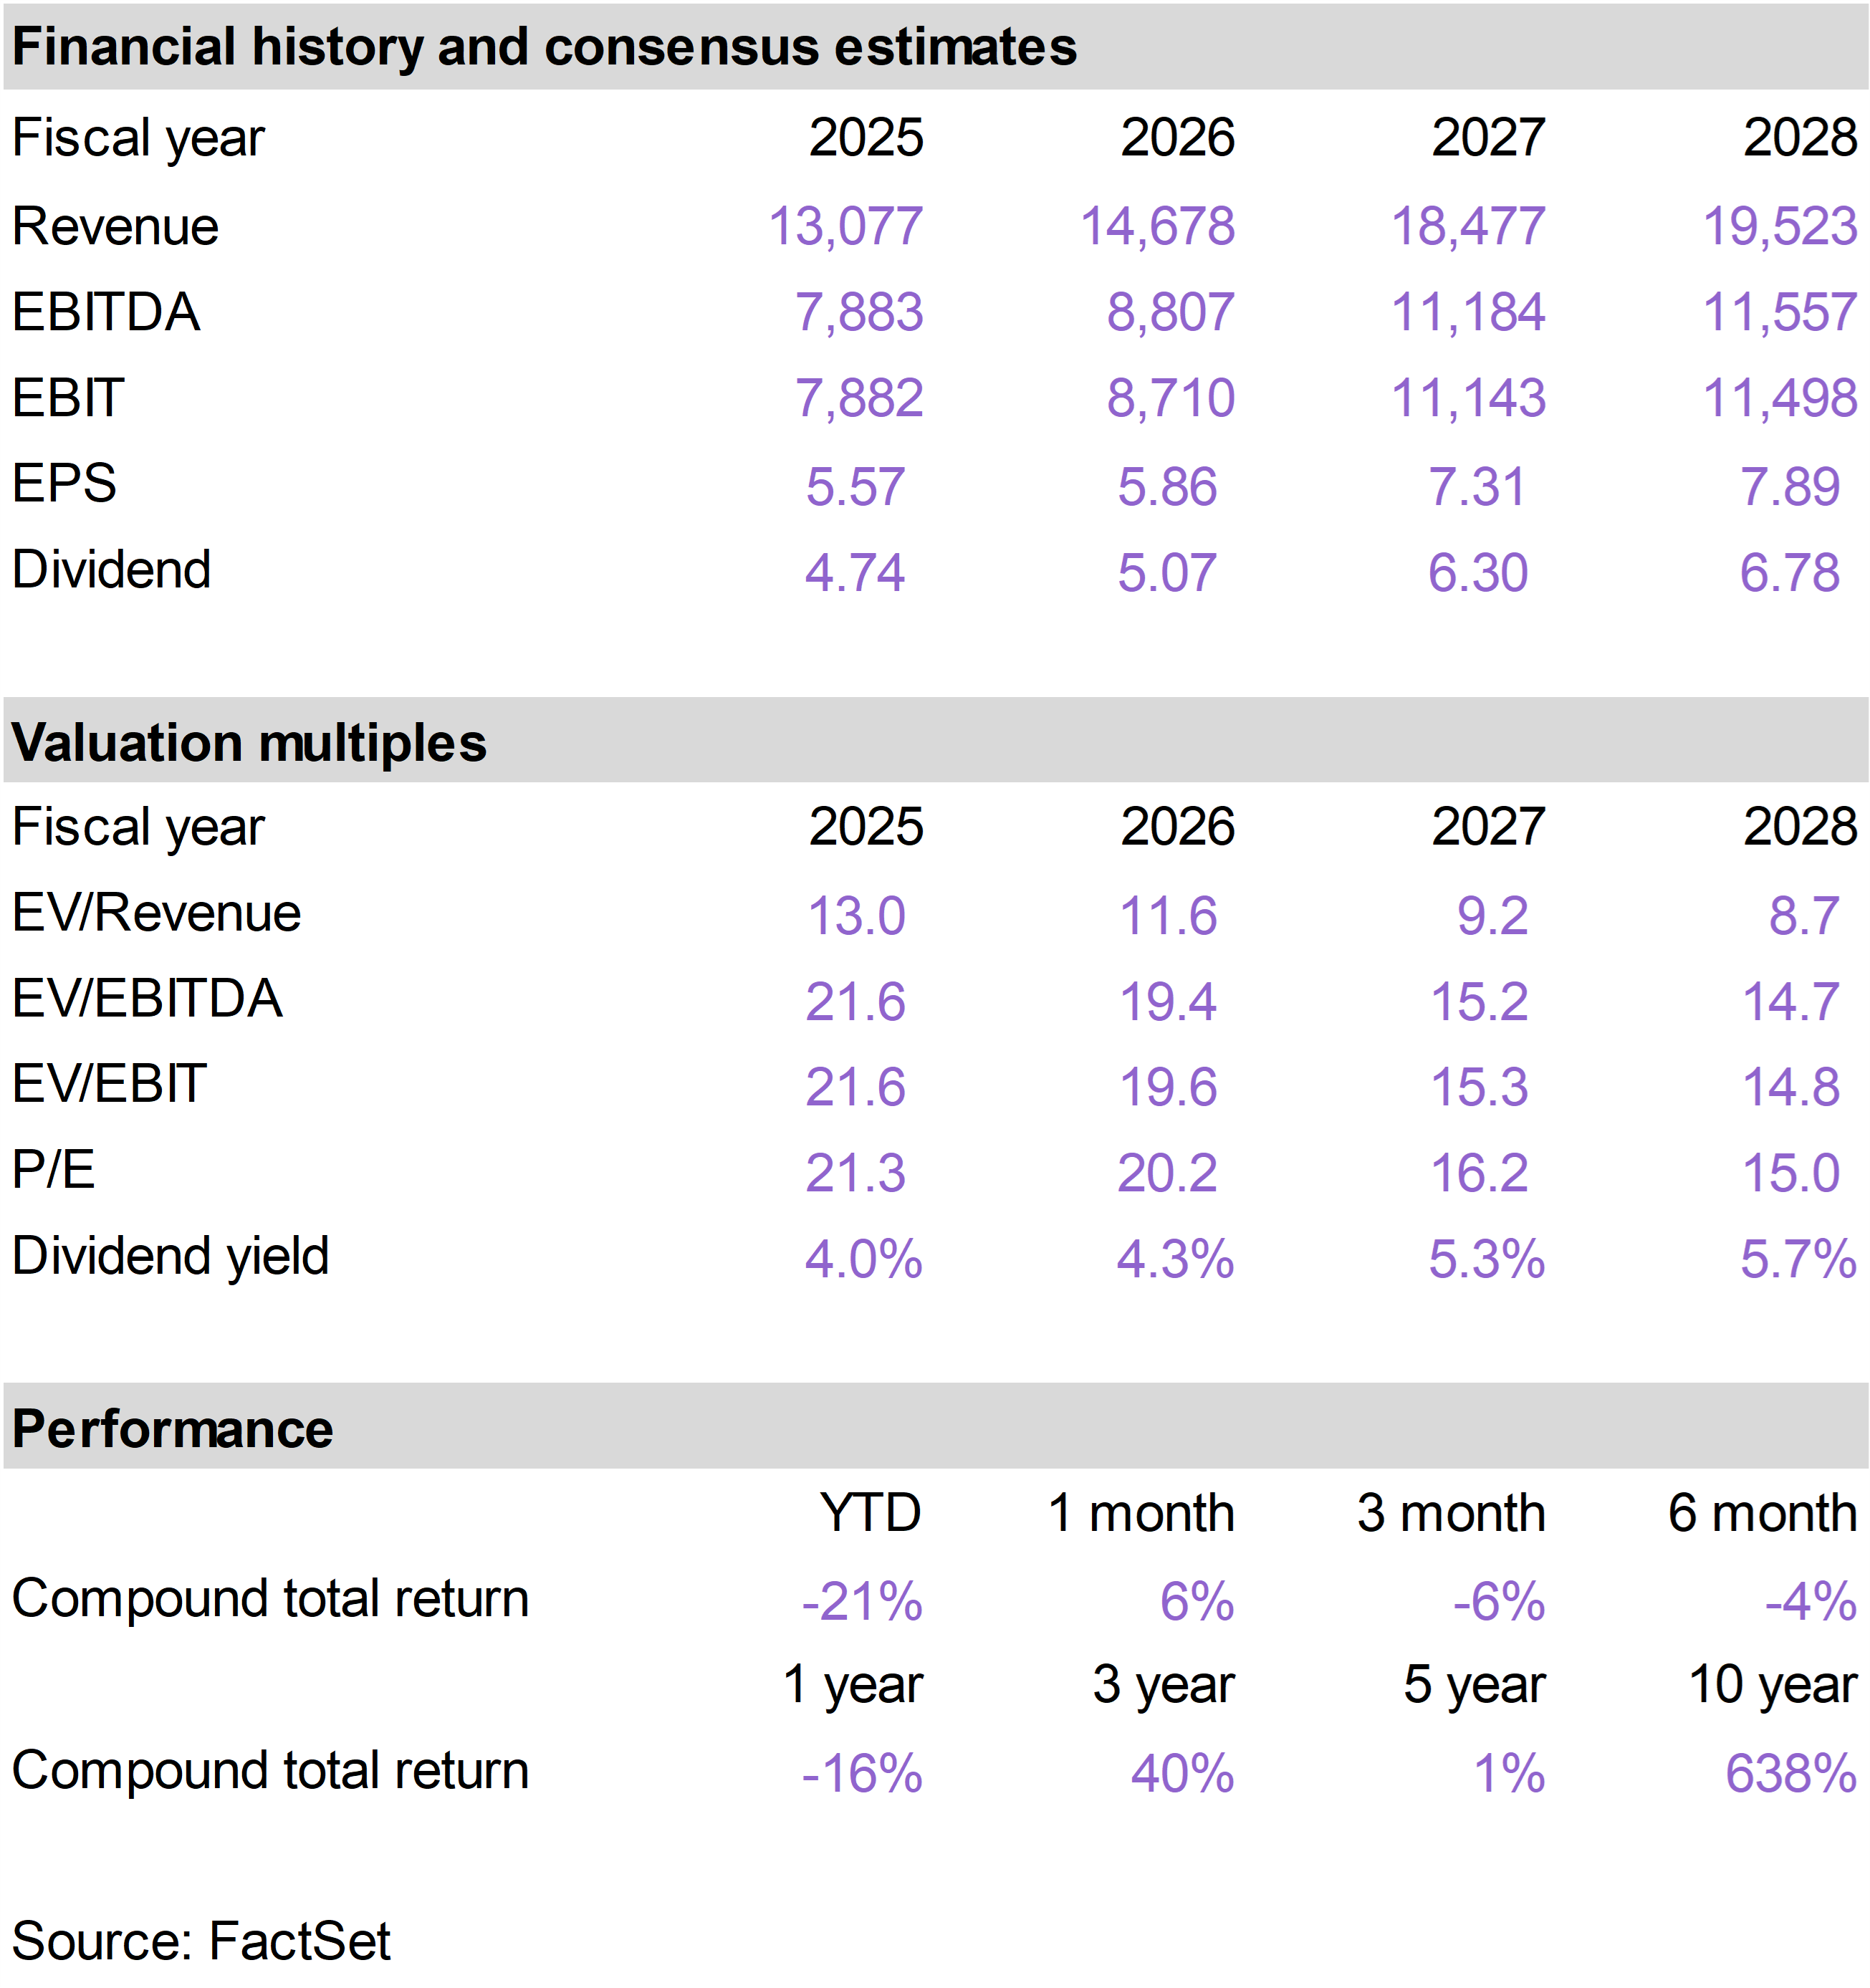
The top performing positions in the portfolio in October were Crown Castle (CCI), which returned 33%; Permian Resources (PR), which returned 23%; and WEC Energy Group (WEC), which returned 15%.
Two positions delivered negative returns this month. Strategy 8% Perpetual Preferred (STRK) returned -9%, while Prologis (PLD) returned -1%. |
|
|
The Anti-AI Trade
For much of 2026, including September, a relatively small group of large technology companies has dominated stock market performance, propelled by enormous enthusiasm surrounding the AI revolution.
That dynamic reversed dramatically in October.
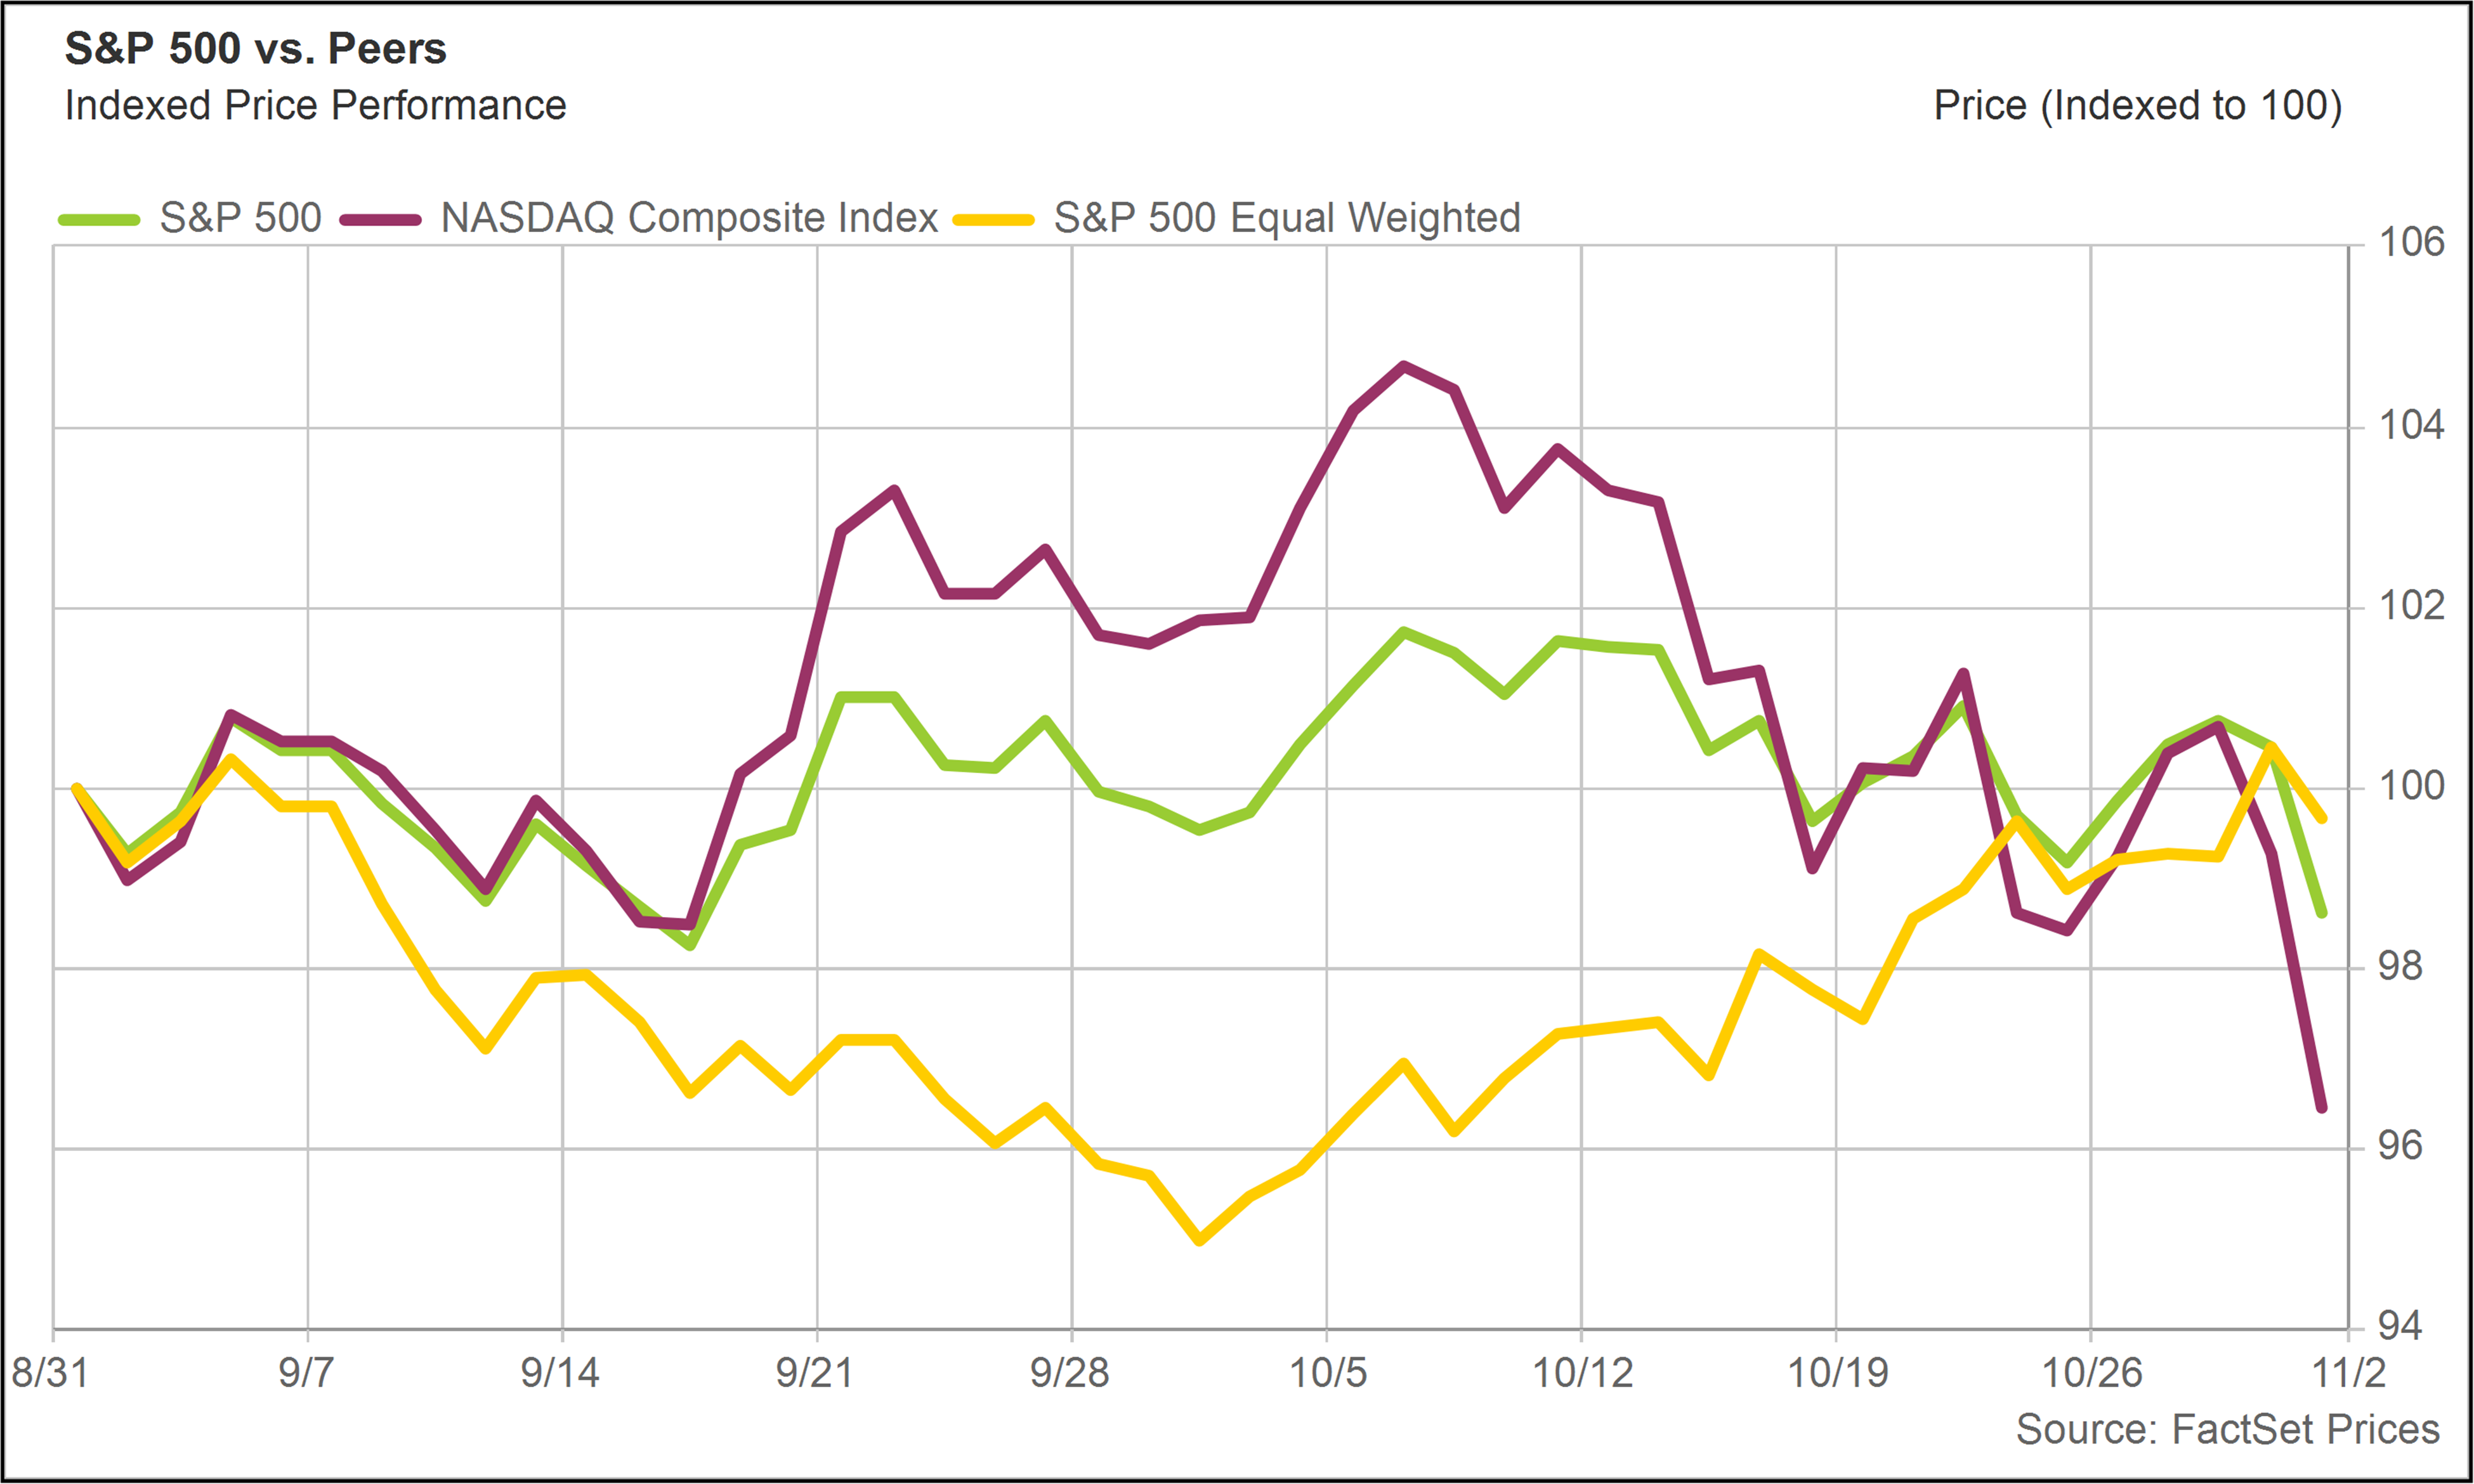
The S&P 500 declined 0.9%, while the tech-heavy NASDAQ Composite fell 5.3%, its worst monthly performance since March 2025.
Yet most stocks actually performed quite well.
The S&P 500 Equal Weight Index, which assigns the same importance to every company rather than weighting them by market capitalization, gained approximately 4.9%.
This represents an extraordinary divergence of nearly 6% between the two versions of the same index.
September had produced almost precisely the opposite outcome. Technology stocks rallied, while the equal-weighted S&P 500 declined 4.8%.
In October, investors shifted capital away from mega-cap tech and back toward a much broader range of industries that the market had largely abandoned the month prior. |
|
|
|
S&P 500 vs. NASDAQ, S&P 500 Equal Weight(Total Return - 8/31/2026-10/31/2026) |
|
|
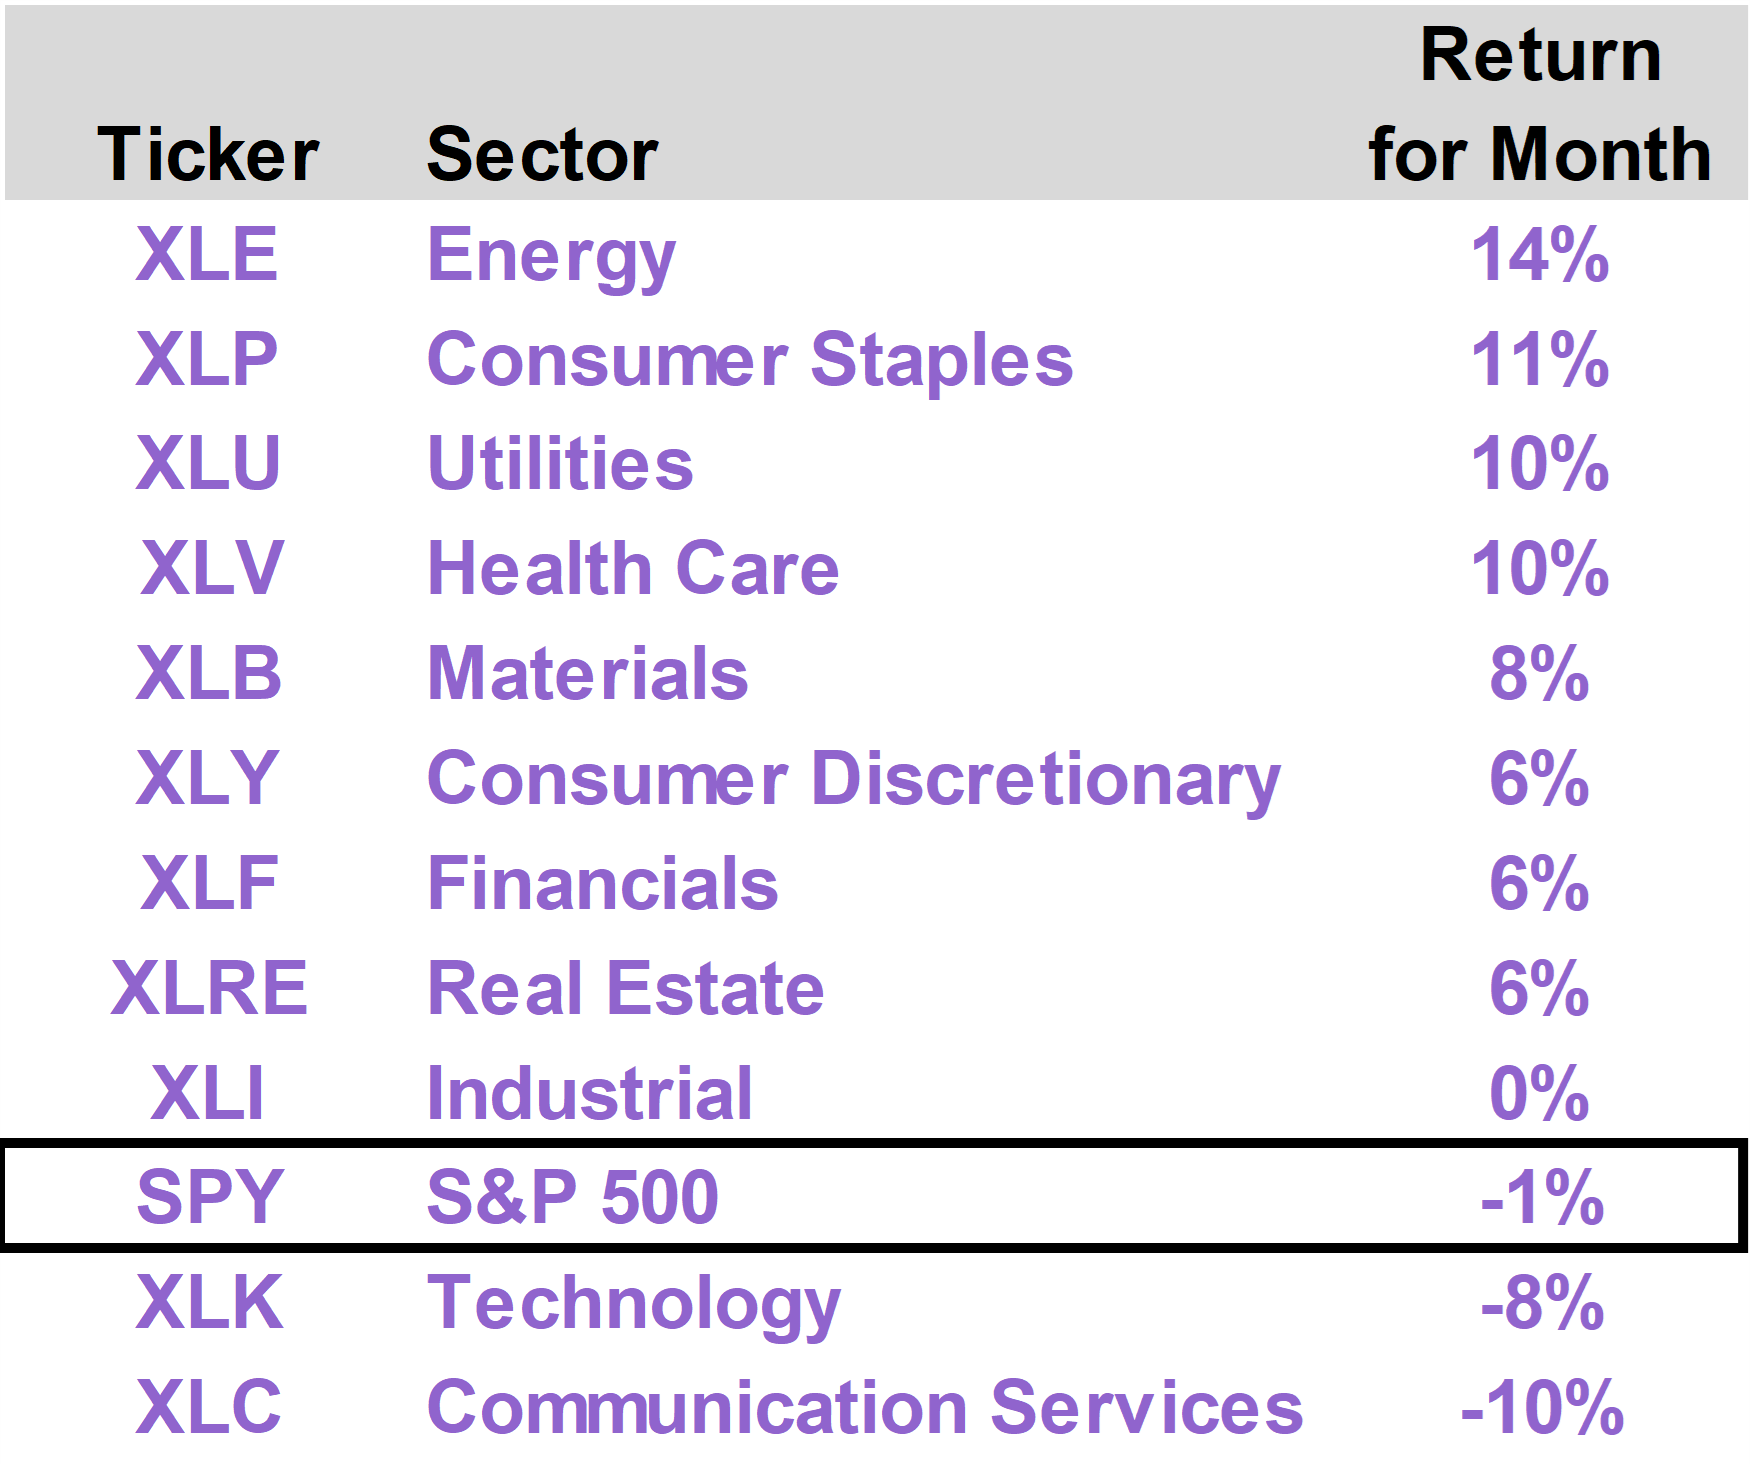
The reversal is particularly striking when we examine performance at the sector level.
Back in September, Technology was the only S&P 500 sector to generate a meaningfully positive return.
In October, nine of the eleven sectors advanced, while Technology and Communication Services were the only two to decline.
It is worth highlighting that, within the Communication Services sector, Alphabet (GOOGL) has a nearly 20% weighting. GOOGL declined 18% in October, which weighed heavily on the sector result. |
|
|
|
Energy was the top performer, benefiting from additional strength in oil prices.
Defensive sectors like Consumer Staples, Utilities, and Health Care also delivered double-digit returns, aided by a meaningful decline in long-term interest rates.
Meanwhile, the two sectors most heavily exposed to the largest AI-related technology companies suffered substantial losses.
The AI spending debate intensifies
Concerns over the enormous sums being committed to AI infrastructure became particularly acute toward the end of October, as the big AI hyperscalers reported third quarter earnings.
In addition to GOOGL, companies likes Amazon (AMZN), and Meta Platforms (META) continued to demonstrate impressive earnings growth. Yet their share prices came under pressure as investors focused on their aggressive capital spending programs.
The central question is whether these companies will ultimately earn attractive returns on their massive investments in data centers, computing infrastructure, and other AI-related assets.
As we discussed in our recent 76report (The Great AI Free Cash Flow Debate), high levels of capital expenditure can depress free cash flow even as earnings continue to grow.
Declining free cash flow does not necessarily indicate deteriorating business fundamentals. Investments intended to create new sources of earnings can require substantial cash expenditures years before they generate meaningful revenue.
But there is a legitimate risk that companies will spend too aggressively, misjudge future demand, or discover that maintaining their competitive positions requires more ongoing investment than originally anticipated.
The critical issue is not simply how much these companies are spending, but what economic returns those investments will ultimately produce.
Despite the sentiment shift, we remain optimistic about the long-term opportunity presented by AI.
Current demand for AI compute is overwhelming, which explains why the hyperscalers are pursuing the opportunity so aggressively. They do expect high returns as they become the world’s leading providers of this computational power.
At the same time, given the vast scale of the investments being made and uncertainty around how they will turn out, it is not surprising to see the market push back from time to time, especially when free cash flow turns severely negative.
Long-term rates finally retreat
Another important (and somewhat related) development in October was the reversal in long-term Treasury yields.
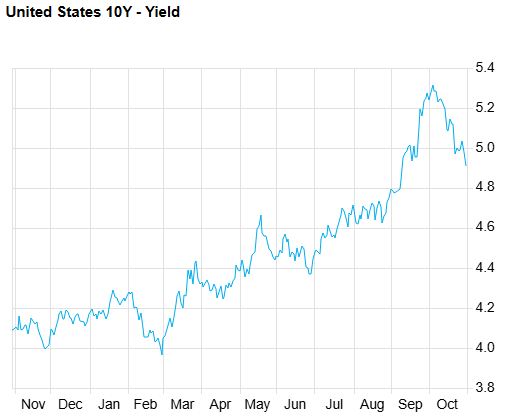
In September, rapidly rising interest rates created a major headwind for most areas of the stock market. The yield on the benchmark 10-Year Treasury climbed to approximately 5.3% by the end of September, reflecting persistent inflation, resilient economic activity, and renewed monetary tightening by the Federal Reserve.
October brought a significant change.
The 10-Year Treasury yield declined to approximately 4.9%, representing a drop of roughly 35 basis points over the course of the month. |
|
|
|
10-Year Treasury Yields—Last 12 Months(Source: FactSet) |
|
|
The 30-Year Treasury yield also moved meaningfully lower, declining from approximately 5.6% to 5.3%.
Interestingly, this happened even as the Federal Reserve maintained a relatively hawkish posture. At its October 28 meeting, the Fed left its target interest rate unchanged at 3.75%–4.00%. Two members actually favored another rate hike.
Inflation also remains elevated. The Personal Consumption Expenditures (PCE) price index, the Fed's preferred inflation measure, increased 3.6% over the twelve months ending in September.
Nonetheless, bond investors have begun to reassess whether the relentless upward movement in long-term interest rates is sustainable.
Part of the decline may reflect investors seeking the relative safety of government bonds amid tech volatility. But there is also the possibility that long-term yields had simply moved too far, too quickly.
As we have previously discussed, higher borrowing costs eventually create their own economic consequences, discouraging investment and weakening demand for credit.
The decline in long-term yields was particularly favorable for many of the stocks that suffered most during September's sell-off.
Real Estate, Utilities, and other income-producing businesses are especially sensitive to interest rates because investors frequently compare their expected returns with those available on government bonds.
Lower Treasury yields make their earnings and dividends relatively more attractive, while also reducing the discount rates investors apply to future cash flows.
Many of these businesses had experienced substantial valuation declines despite generally resilient operating fundamentals. As we signaled last month, this pressure on valuations set the stage for a potentially sharp recovery once rates stabilized or reversed.
October demonstrated how quickly market sentiment toward such companies can improve when the direction of interest rates begins to change.
Oil remains a major complication
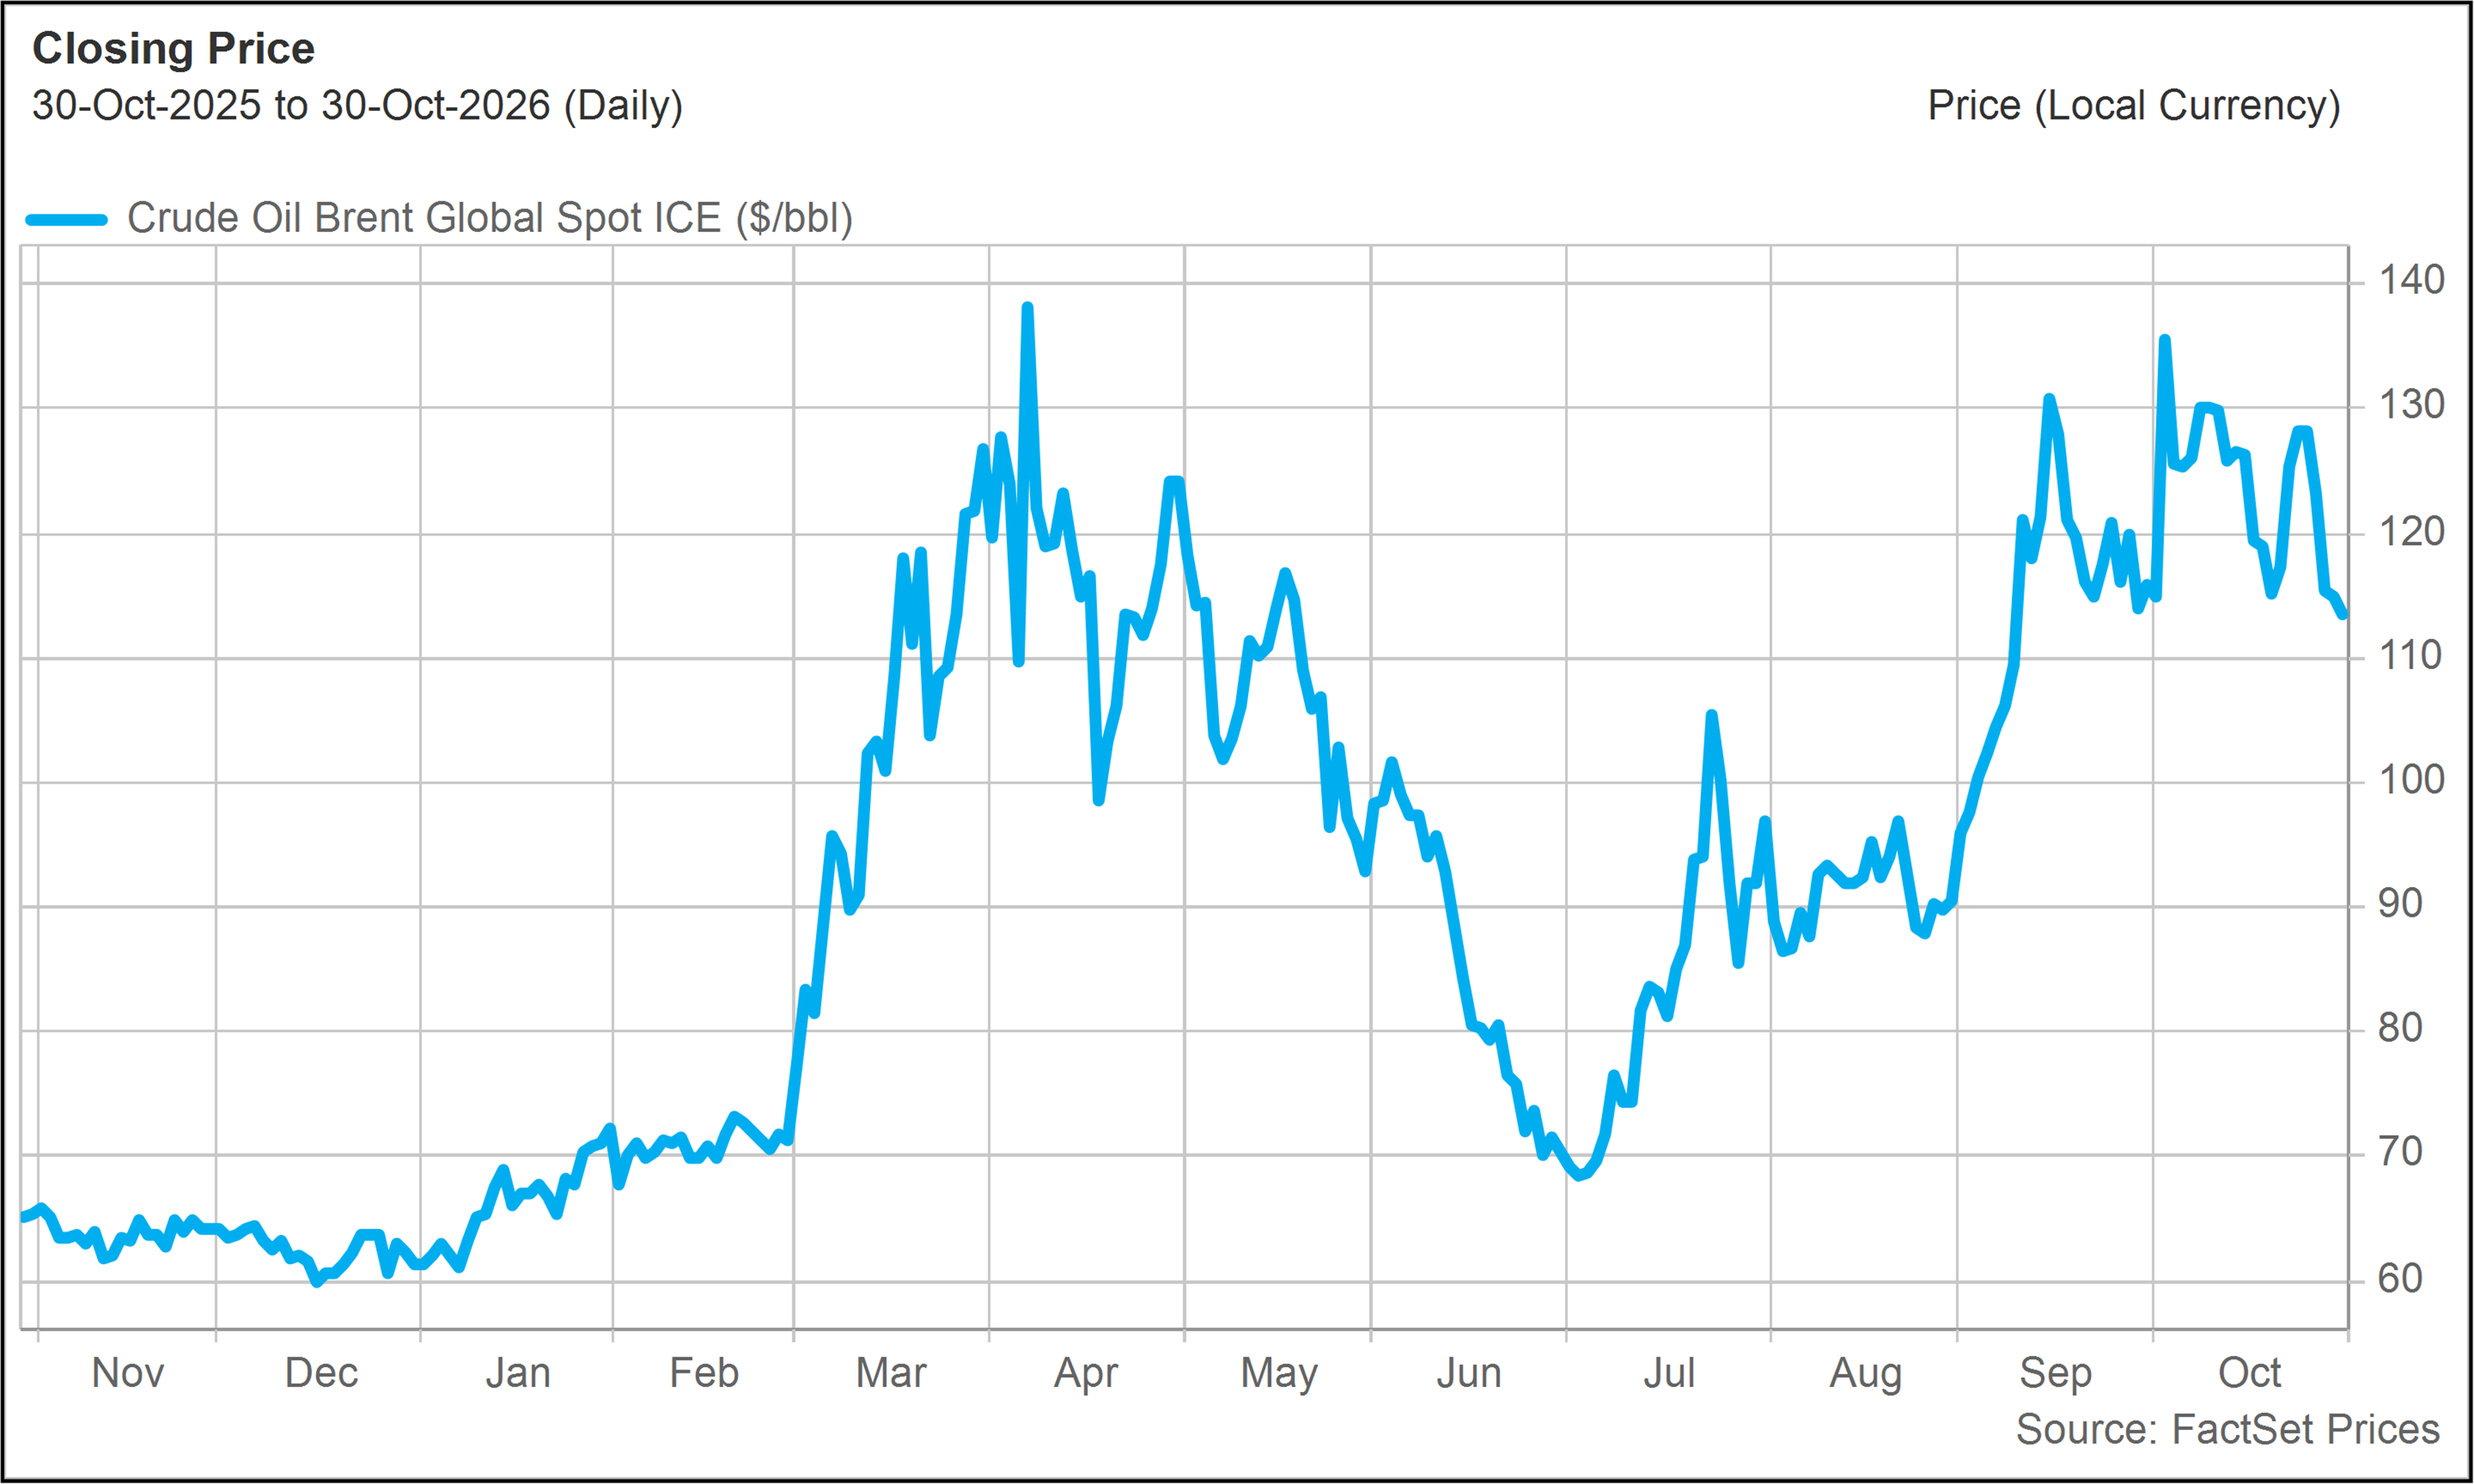
While the reversal in Treasury yields is encouraging, the inflation picture remains complicated by persistently elevated energy prices.
Oil prices were generally higher in October as the conflict with Iran continued to disrupt global energy markets. Brent crude ended the month at approximately $113 per barrel. |
|
|
|
Crude Oil($/barrel - Year to Date) |
|
|
High oil prices have added to inflationary pressure and created a difficult political environment for the Trump administration.
As we discussed earlier in the 76report (Midterms and the Stock Market—How Worried Should We Be?), there has been some encouraging progress in the physical oil market.
Regional producers have managed to restore a substantial portion of their export volumes through alternative pipelines, shipping arrangements, and other logistical adaptations.
Yet the recovery in physical supply has not translated into normalized prices. Shipping costs, insurance premiums, security risks, and shortages of certain refined petroleum products—particularly diesel—continue to create substantial additional costs.
The important question is whether the global energy system can continue adapting to these disruptions and eventually reduce the enormous risk premiums embedded in oil prices.
We remain cautiously optimistic that these pressures will eventually ease.
A sustained decline in energy prices could materially improve the inflation outlook, potentially giving the Fed more flexibility and creating additional downward pressure on long-term interest rates.
Midterms are now imminent
Another major source of uncertainty is political.
The November 3 midterm elections could shift control of Congress, with Democrats widely expected to make gains, particularly in the House of Representatives.
This has implications for the Trump administration's legislative agenda, as well as regulation and oversight affecting individual industries. Yet we believe investors should be careful about placing too much emphasis on the election itself.
As we discussed in our recent midterm-election analysis, the two most consequential forces driving the stock market—AI and oil prices—are largely independent of which political party controls Congress.
AI investment will ultimately be determined by technological progress, commercial demand, and the economic returns available to companies deploying capital.
Similarly, the resolution of the Iran conflict and the resulting trajectory of global oil prices will depend primarily on geopolitical and economic developments rather than congressional majorities.
The election could certainly influence market sentiment, particularly if the results differ materially from expectations. But significant Democratic gains are already widely anticipated.
Historically, markets have often performed well following midterm elections, regardless of which party wins, as political uncertainty begins to fade.
The more important determinants of longer-term stock market performance will remain economic growth, inflation, interest rates, and corporate profitability.
A healthier market beneath the volatility?
Despite the sharp decline in technology stocks, October brought several reasons for optimism. The broader economy continues to demonstrate considerable resilience.
Real U.S. GDP expanded at an annualized rate of 3.4% in the third quarter, accelerating from 2.2% in the second quarter.
Corporate earnings generally remain strong, and investment in AI infrastructure continues at a robust pace (although resistance from the equity market could lead to some moderation).
Meanwhile, the recent decline in long-term interest rates has begun to provide relief to many high-quality businesses whose valuations were severely pressured in September.
Most importantly, the stock market is no longer relying exclusively on a handful of technology companies to generate positive returns. The extraordinary divergence between the NASDAQ and the equal-weighted S&P 500 suggests that market leadership is broadening in a constructive way.
There are certainly reasons to remain cautious. AI-related capital spending must ultimately generate attractive financial returns. Oil prices remain elevated, inflation is still too high, and the political environment is uncertain.
But October also demonstrated the benefits of maintaining exposure to a diversified collection of fundamentally attractive businesses.
We remain confident in the long-term economic transformation driven by AI, while recognizing the journey has been and will likely continue to be volatile.
At the same time, many high-quality companies outside the largest technology names offer compelling opportunities to participate in continued economic growth.
If long-term interest rates stabilize or decline further, these businesses could benefit from both improving operating performance and a meaningful recovery in valuations.
October was a difficult month for the AI theme, but it may also have marked an important and constructive shift toward a broader, more balanced stock market. |
|
| | | The top performing positions within the portfolio in October were Crown Castle (CCI), which returned 33%; Permian Resources (PR), which returned 23%; and WEC Energy Group (WEC), which returned 15%.
Two holdings within the portfolio generated negative returns. Strategy 8% Perpetual Preferred (STRK) returned -9%, while Prologis (PLD) returned -1%. |
|
| |
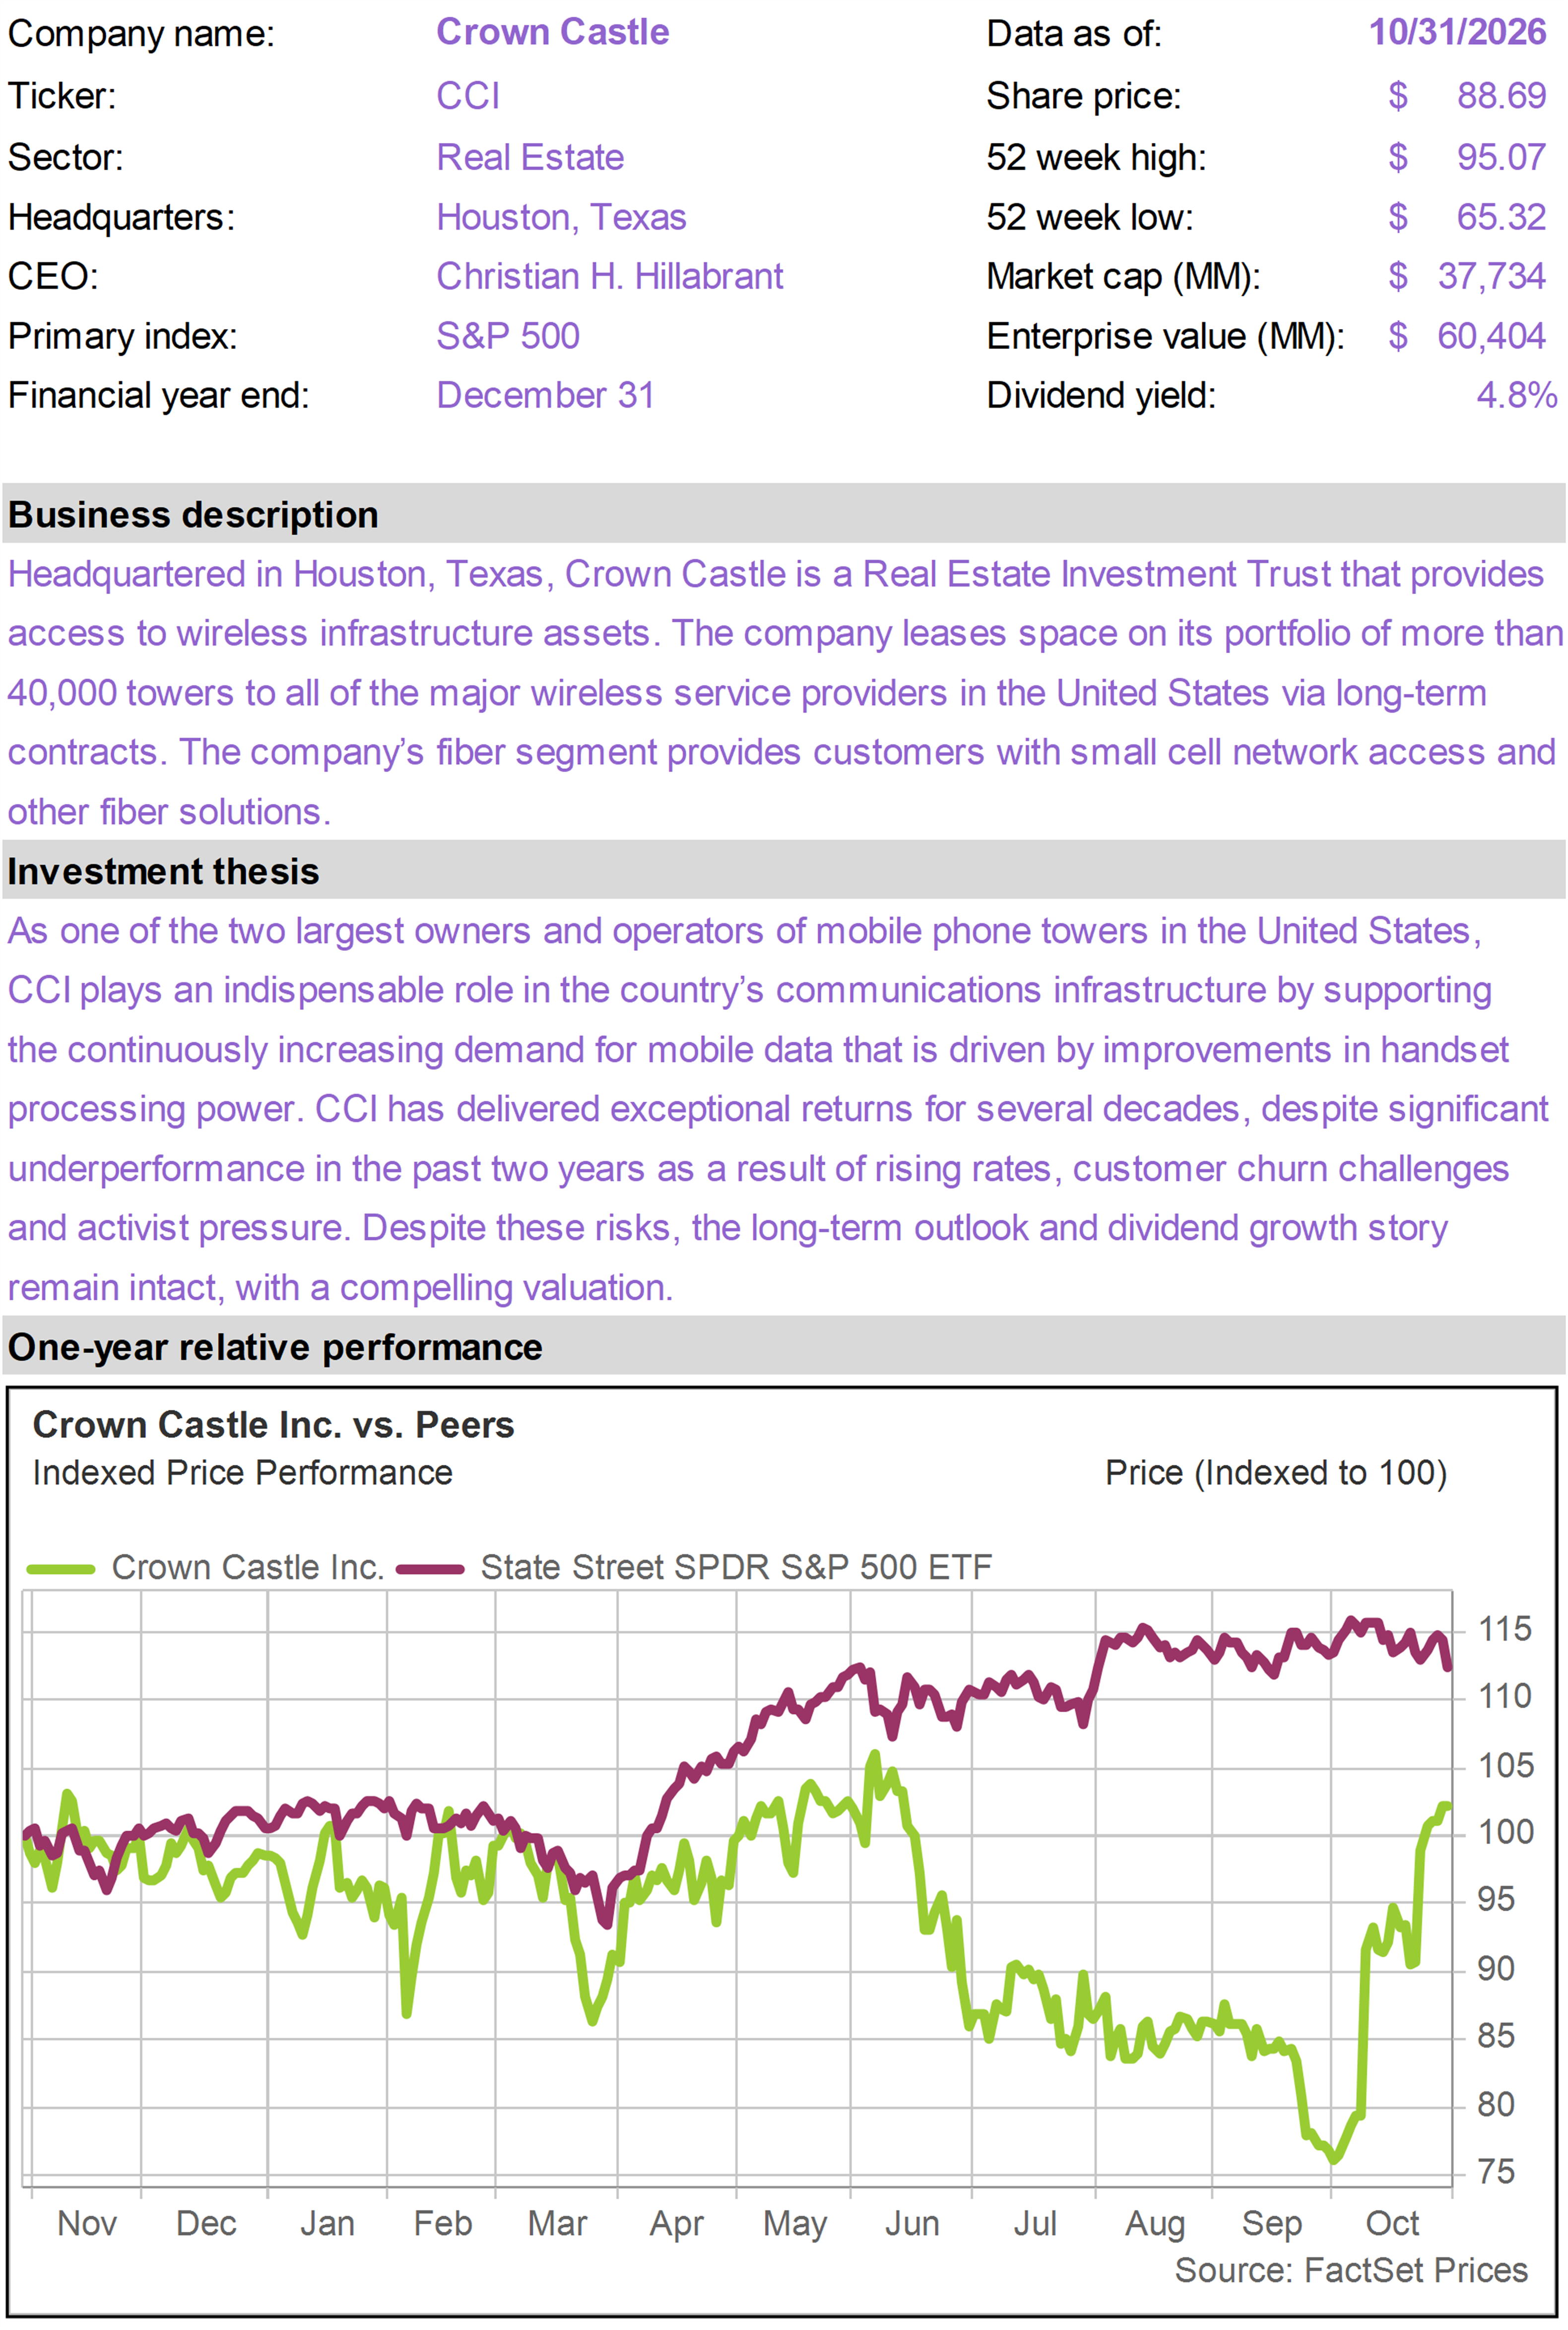
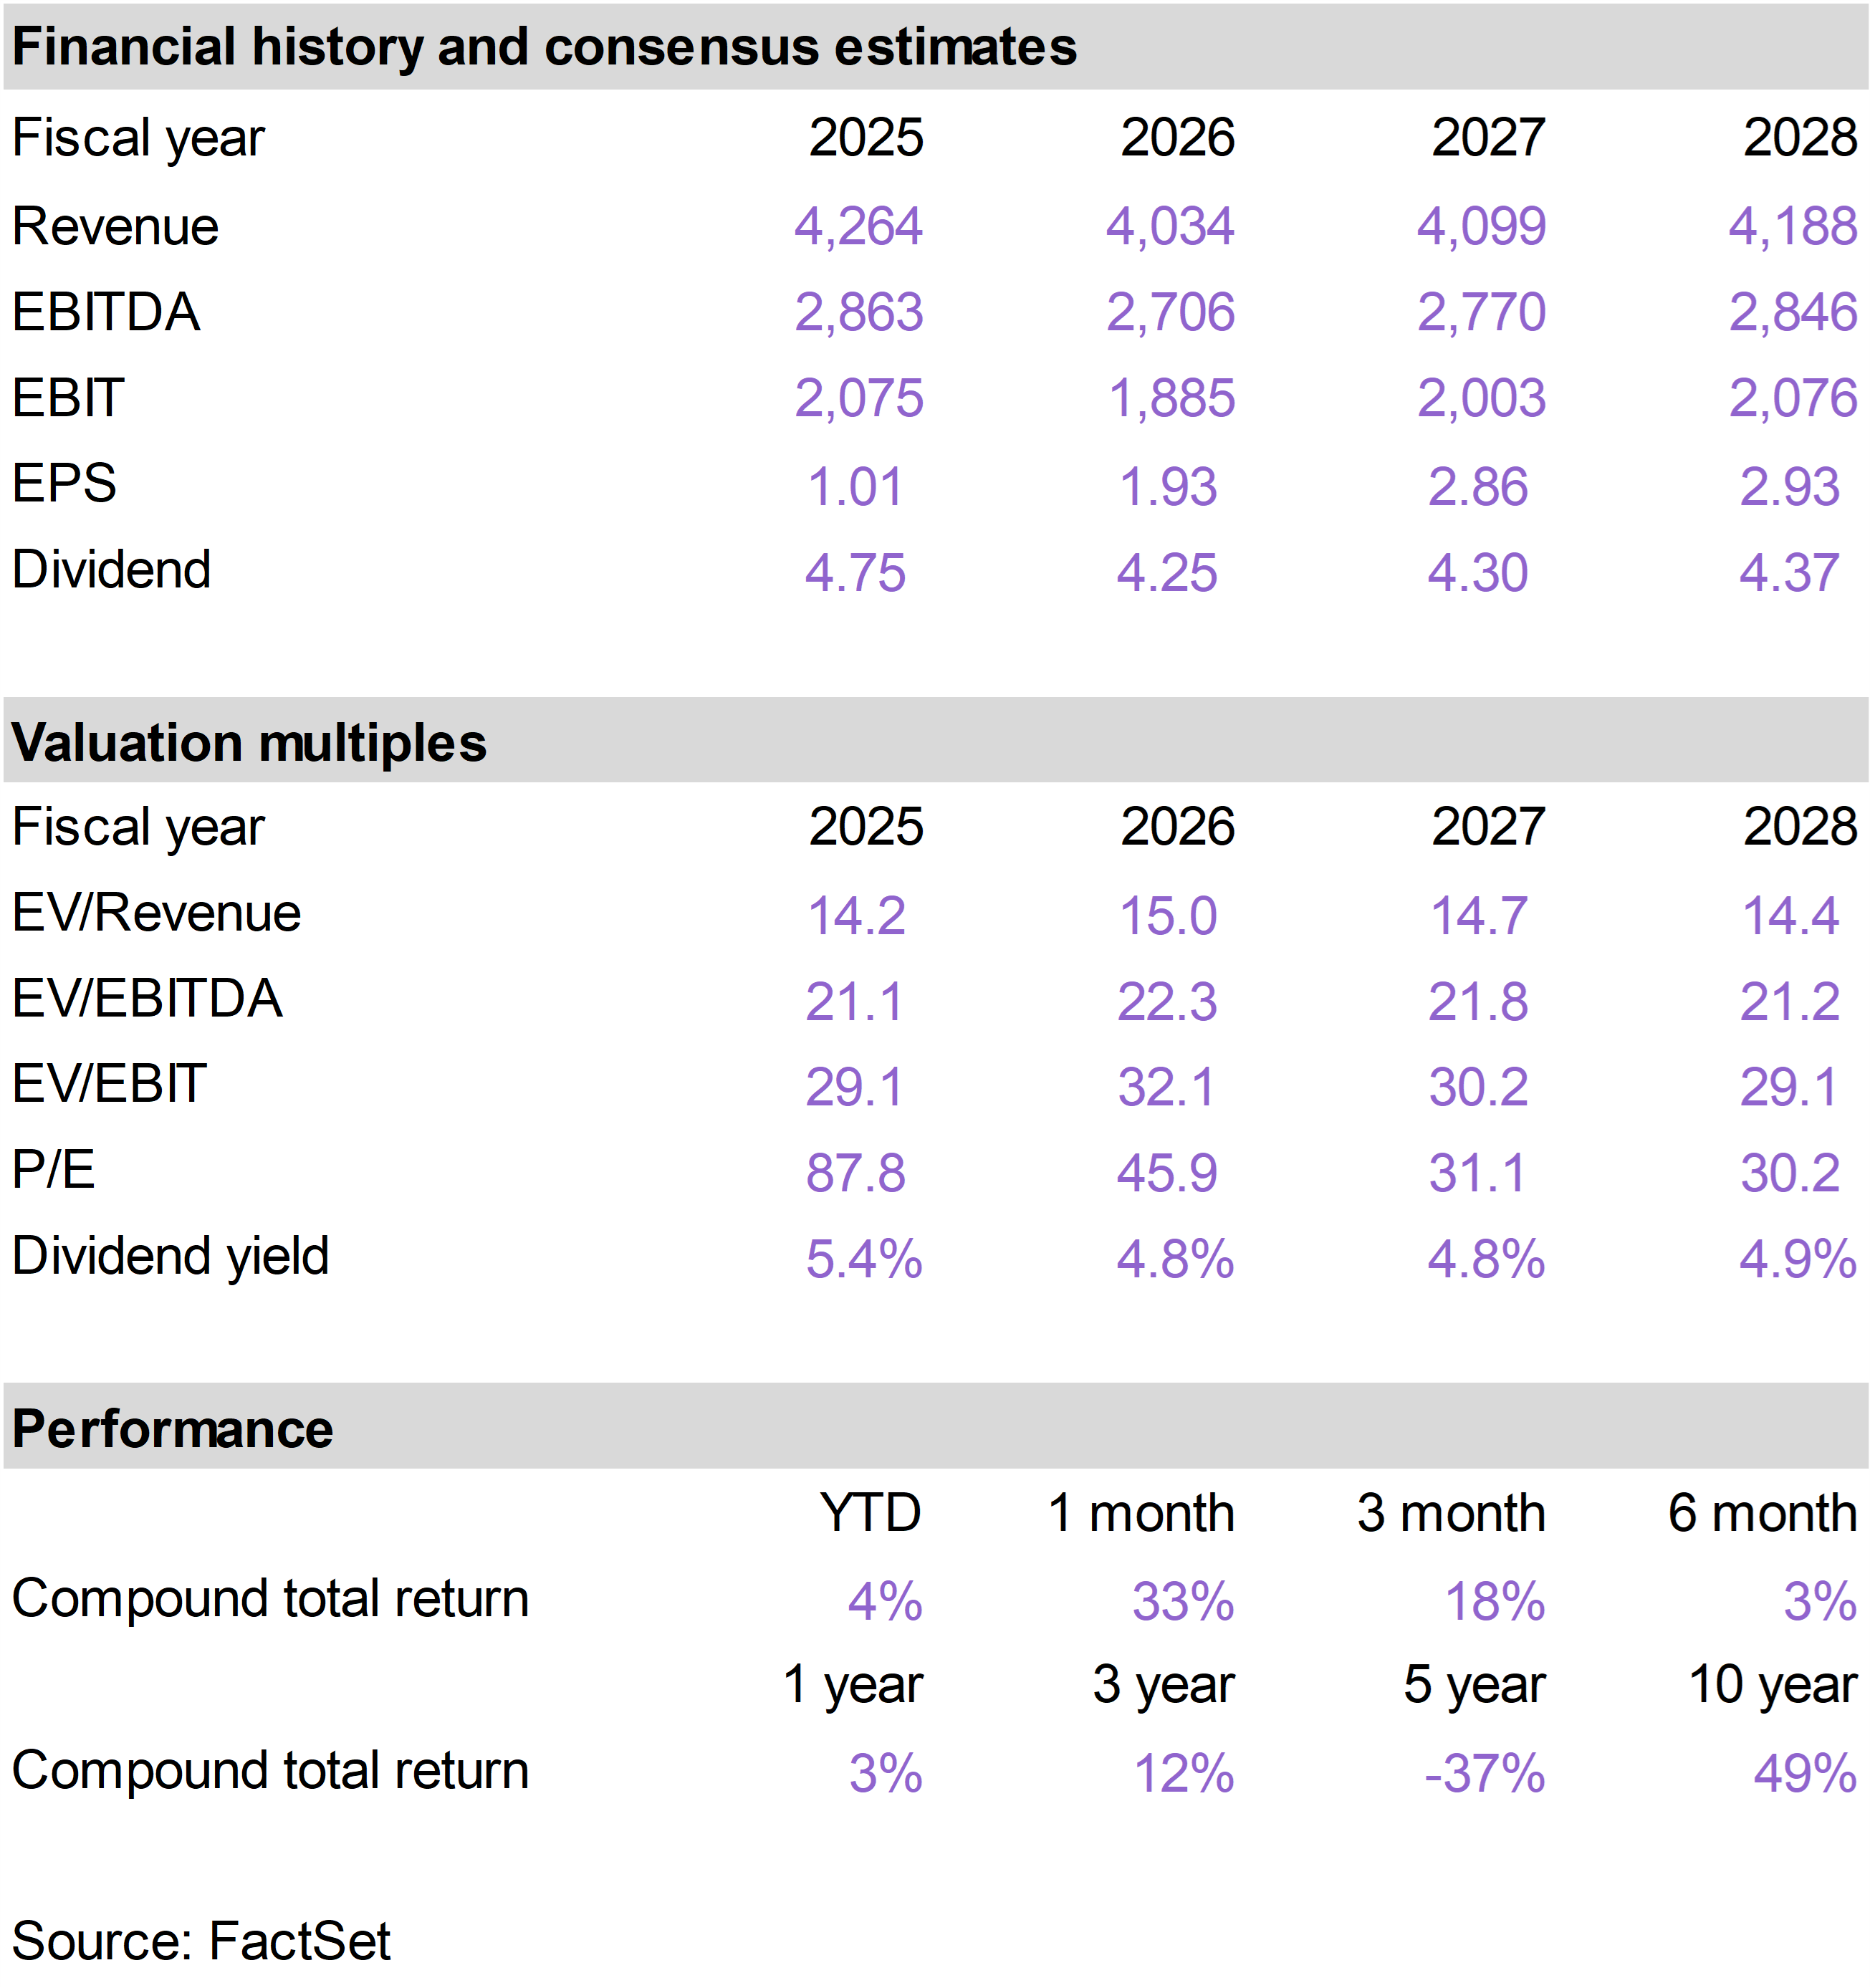
CCI surged in October, benefiting from falling long-term interest rates and growing optimism that the entry of SpaceX (SPCX) into the U.S. wireless market could create significant new demand for cell towers.
The company reported solid third quarter results, with adjusted funds from operations (AFFO) per share increasing 11% to $1.24, exceeding expectations.
Management also modestly raised its full-year outlook, supported by operational efficiencies and lower interest expenses following the sale of its fiber business.
While leasing activity remains subdued, management continues to anticipate that 2026 will represent the bottom of the cycle, with improving growth in 2027 as wireless carriers deploy recently acquired spectrum.
Perhaps the most important development was SPCX's acquisition of nationwide 800 MHz wireless spectrum, signaling its intention to compete more directly with established mobile carriers.
This has fundamentally changed the narrative surrounding satellite communications and the traditional cell tower industry.
Investors have long worried that SPCX's Starlink technology could eventually reduce the need for terrestrial wireless infrastructure by enabling mobile devices to communicate directly with satellites.
However, SPCX's ambitions appear to involve a hybrid network combining satellites with conventional cell towers, rather than replacing terrestrial infrastructure.
The fundamental technological challenge for Starlink is that direct-to-satellite connectivity generally requires a relatively unobstructed line of sight to the sky. Because the vast majority of mobile phone usage occurs indoors, reliable coverage still depends on terrestrial infrastructure, particularly lower-frequency signals that can penetrate buildings more effectively.
Recent reports indicate that SPCX is negotiating access to at least 80,000 U.S. cell sites, potentially creating billions of dollars in new business for tower operators.
CCI, which owns approximately 40,000 towers exclusively in the United States, could be particularly well positioned to benefit. Management has acknowledged discussions with prospective satellite-related customers, although no specific agreements have been announced.
Competition from SPCX could also encourage AT&T (T), Verizon (VZ), and T-Mobile (TMUS) to accelerate their own network investments.
Meanwhile, CCI is exploring opportunities to deploy computing infrastructure at existing tower locations, potentially benefiting from growing demand for edge computing and AI applications requiring extremely low latency.
We view these developments as highly encouraging, particularly following several years of disappointing share price performance.
With its simplified business model, improving cash flow outlook, and annual dividend of $4.25 per share, CCI remains an attractive income-generating investment.
We continue to see meaningful long-term upside as wireless network investment recovers, while SPCX's emergence as a potential new customer could provide an additional source of growth not previously anticipated. |
|
| |
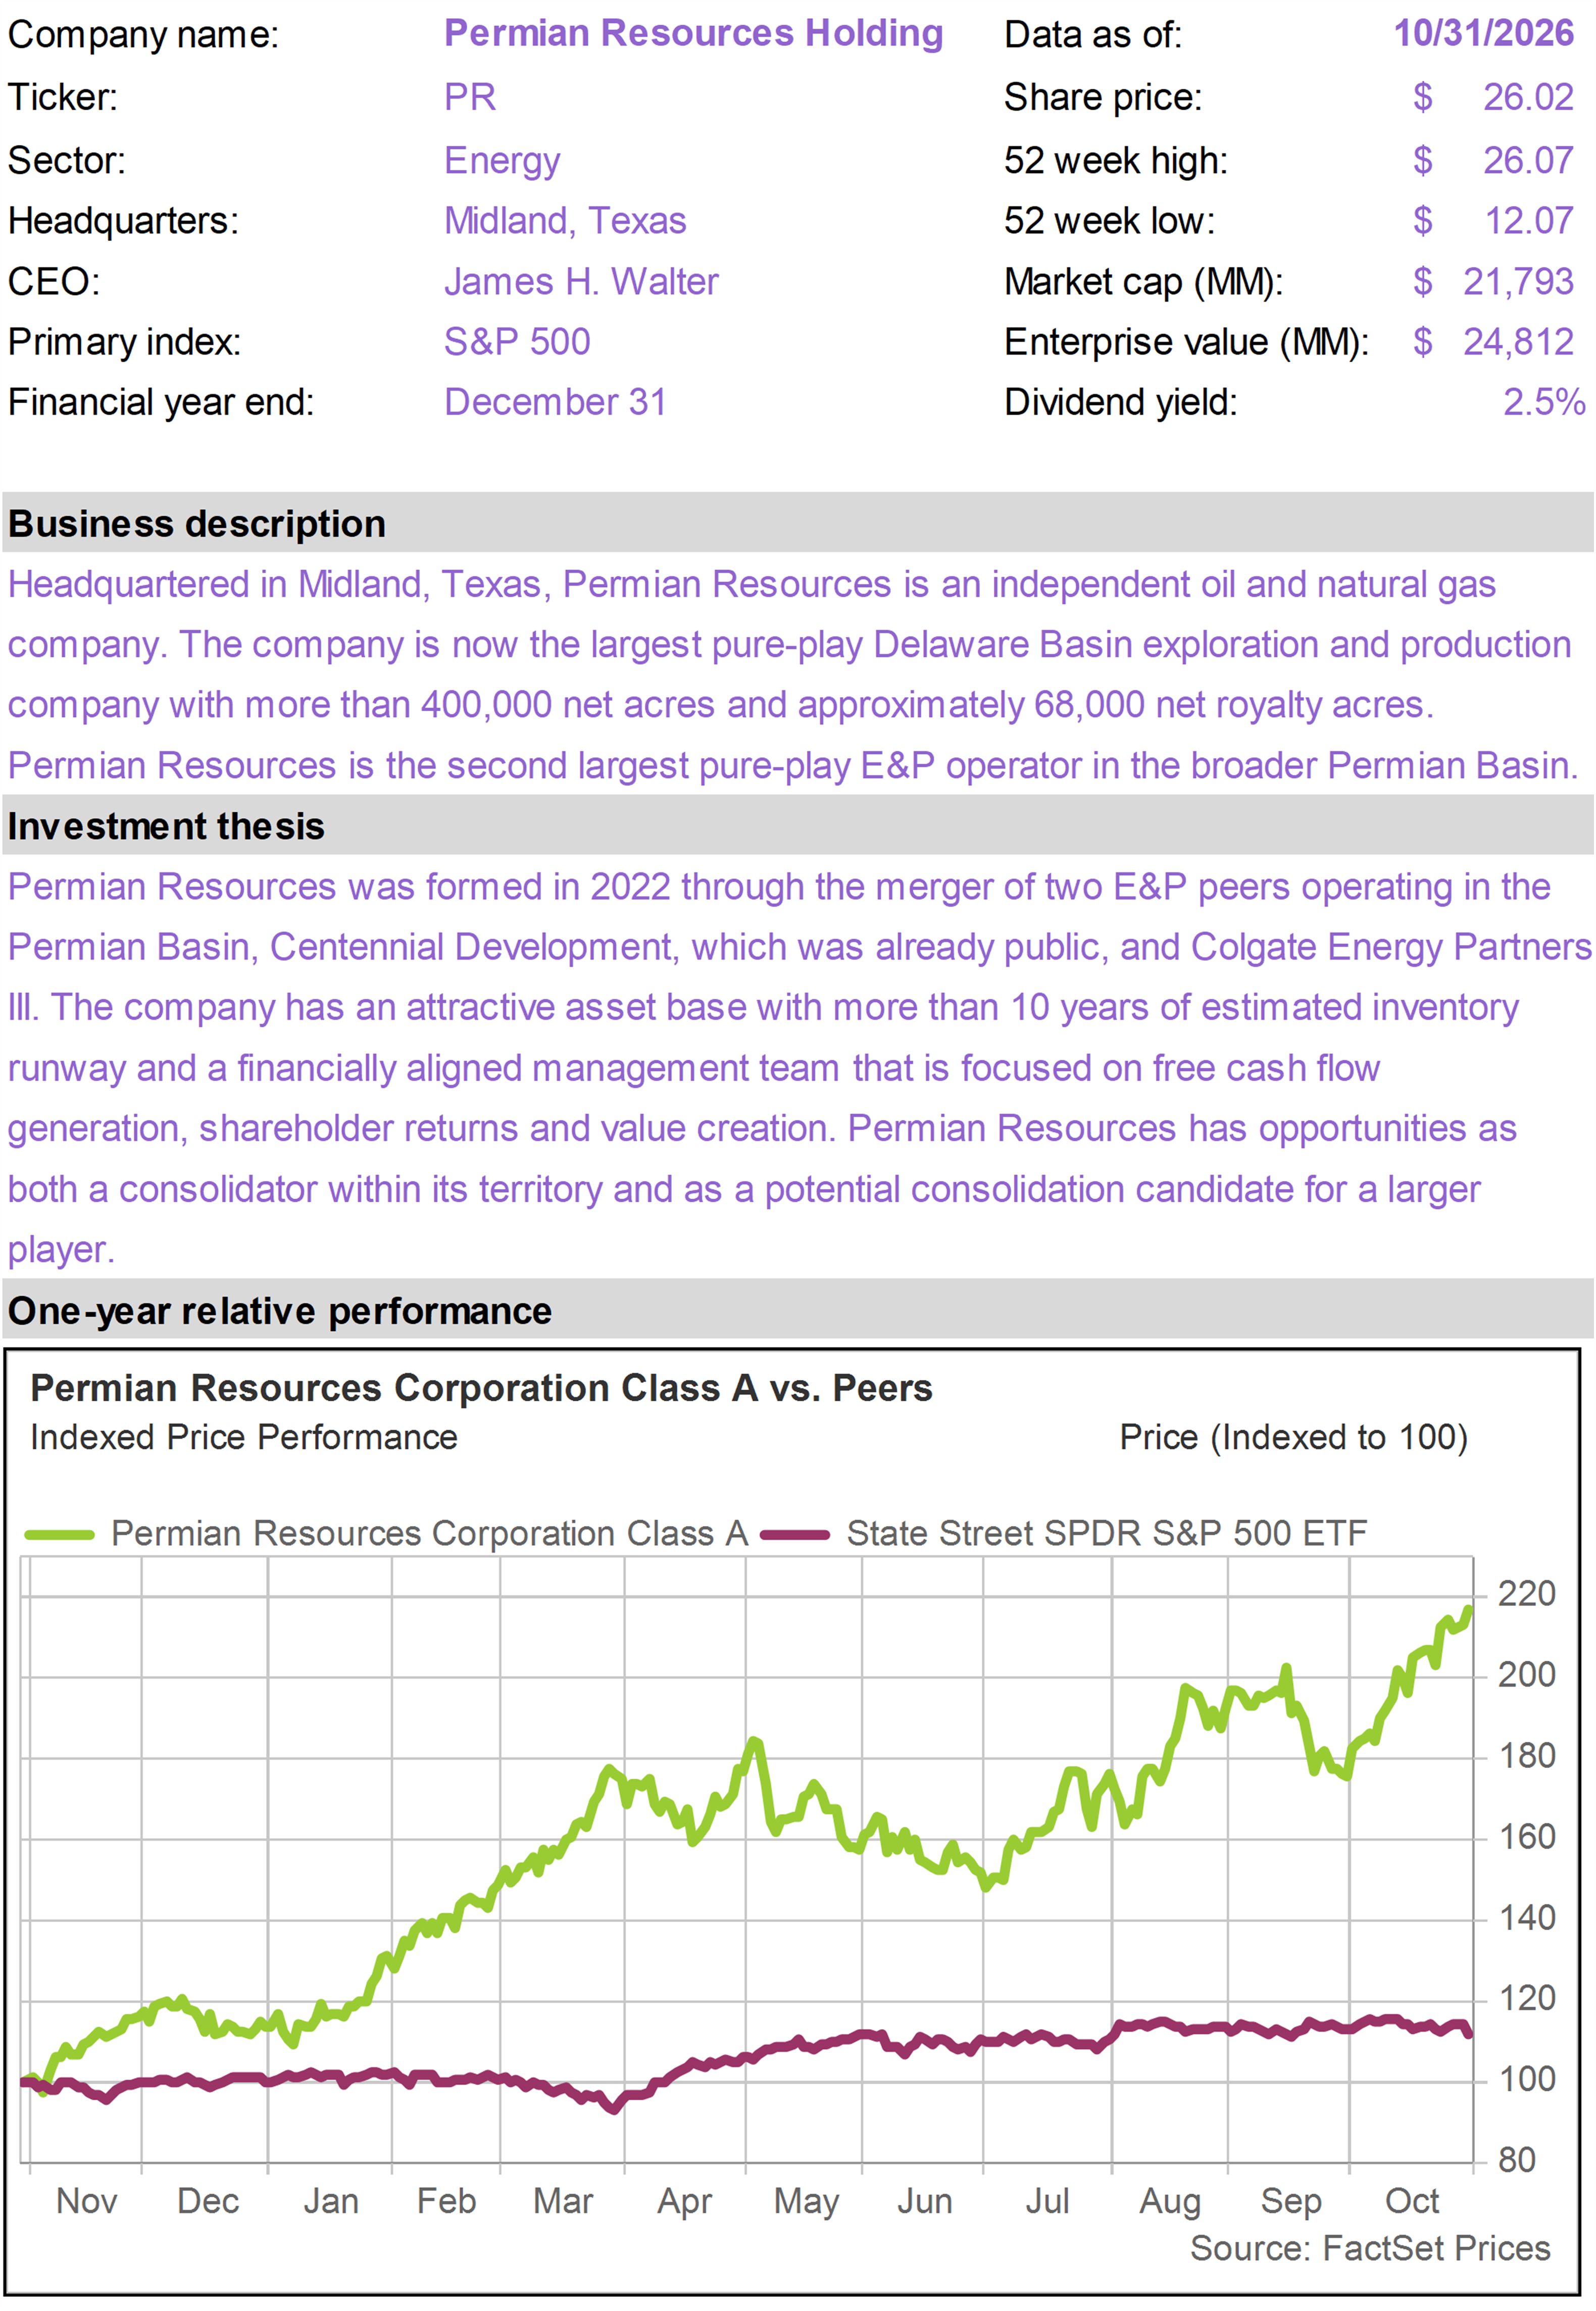
PR advanced in October, benefiting from continued strength in oil prices and growing investor confidence in the company's ability to generate substantial free cash flow.
The company is one of the largest independent producers in the Permian Basin, with a concentration of high-quality assets in the Delaware Basin of West Texas and New Mexico.
PR has distinguished itself through operational efficiency, disciplined capital allocation, and an aggressive strategy of acquiring attractive drilling acreage at favorable prices.
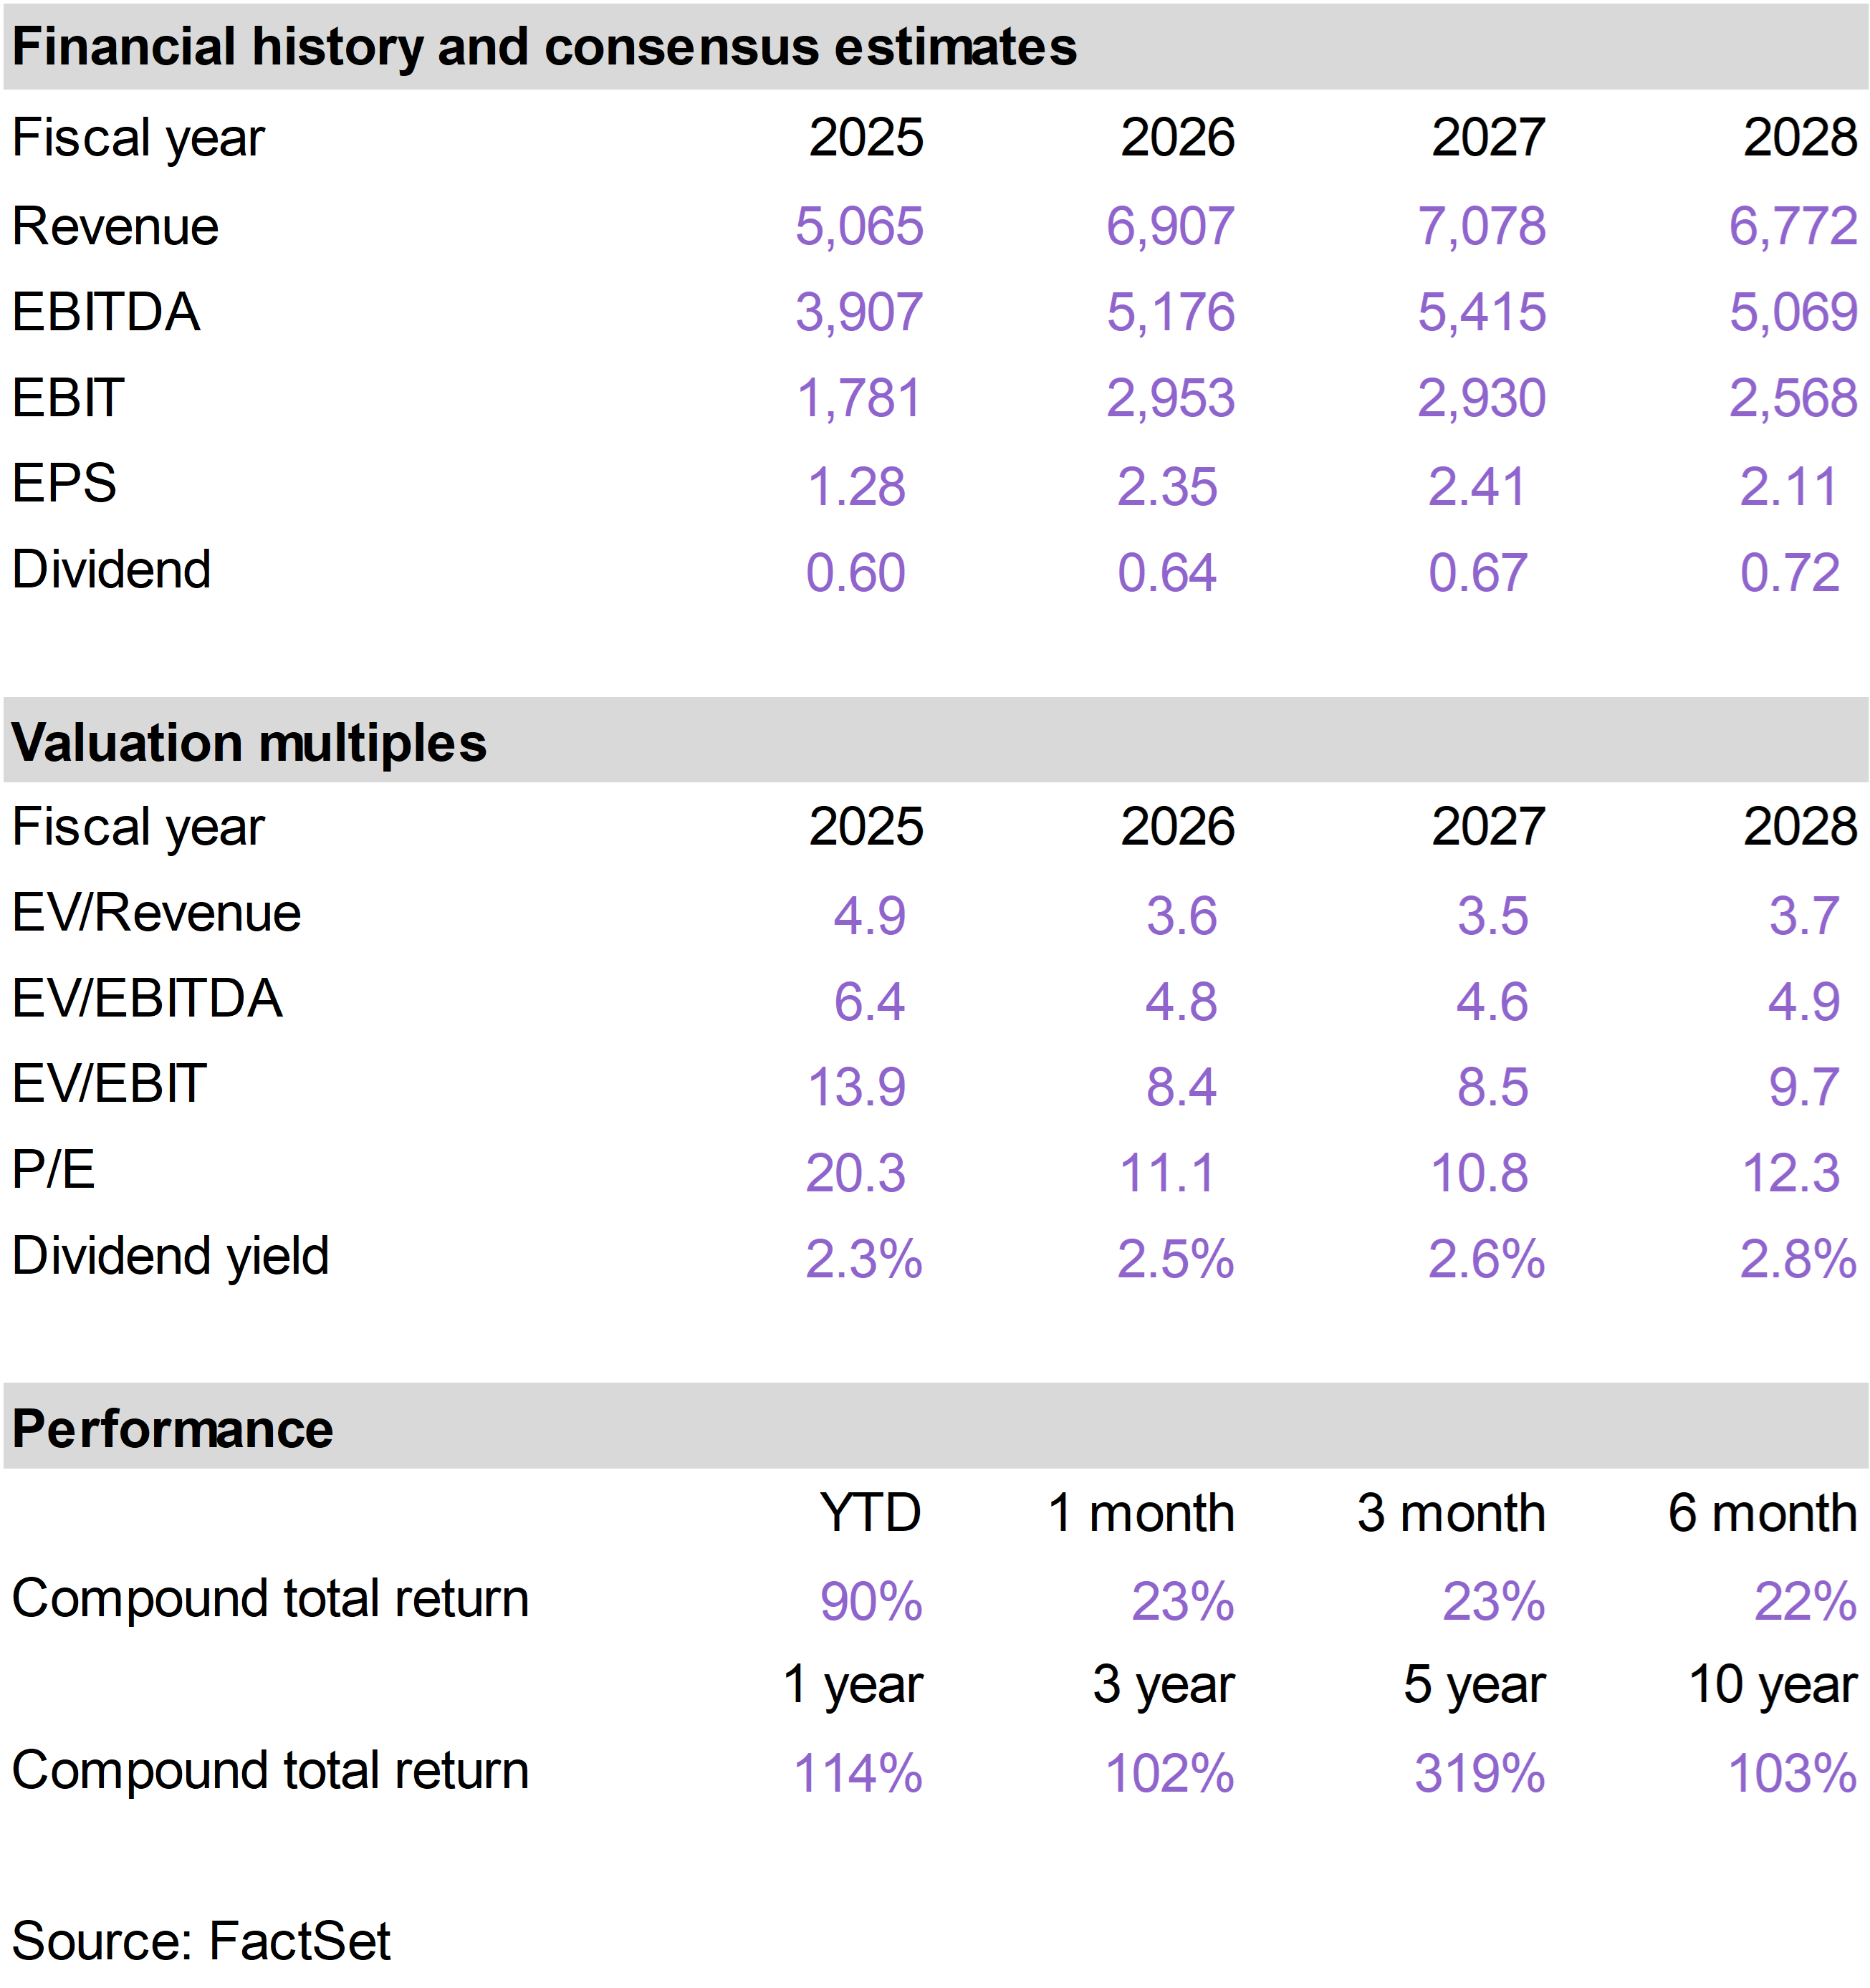
Second quarter results demonstrated these strengths, with oil production reaching approximately 198,000 barrels per day and adjusted free cash flow of $751 million.
Management subsequently raised its full-year oil production guidance to approximately 199,000 barrels per day, representing nearly 10% growth from 2025, while maintaining a capital spending budget of approximately $2 billion.
Third quarter earnings will be reported after the market closes on November 4. Expectations are favorable, with production anticipated to exceed 200,000 barrels of oil per day and potentially surpass the upper end of management's guidance.
PR has been particularly effective at responding to higher oil prices by accelerating high-return projects, including workovers that increase production from existing wells without requiring substantial additional drilling investment.
Meanwhile, the company continues to expand its inventory of attractive drilling locations through smaller acquisitions. During the first half of 2026, PR announced approximately $1.05 billion of transactions, adding valuable acreage and royalty interests within its existing operating footprint.
These investments should support production growth and capital efficiency for years to come.
Despite its expansion, PR maintains a strong balance sheet, with net leverage of approximately 0.5 times annualized adjusted EBITDA at the end of the second quarter.
At prevailing oil prices, the company is positioned to generate substantial excess cash flow, with estimates suggesting an annual free cash flow yield in the mid-to-high teens.
This creates considerable flexibility to pursue additional acquisitions, repurchase shares, reduce debt, and support its dividend.
While the eventual resolution of the Iran conflict could put downward pressure on oil prices, we believe PR's low-cost operations and disciplined management provide important protection against a less favorable commodity environment.
We continue to view PR as one of the most attractive operators in the U.S. energy sector, combining significant exposure to elevated oil prices with strong underlying economics and a shareholder-oriented capital allocation strategy. |
|
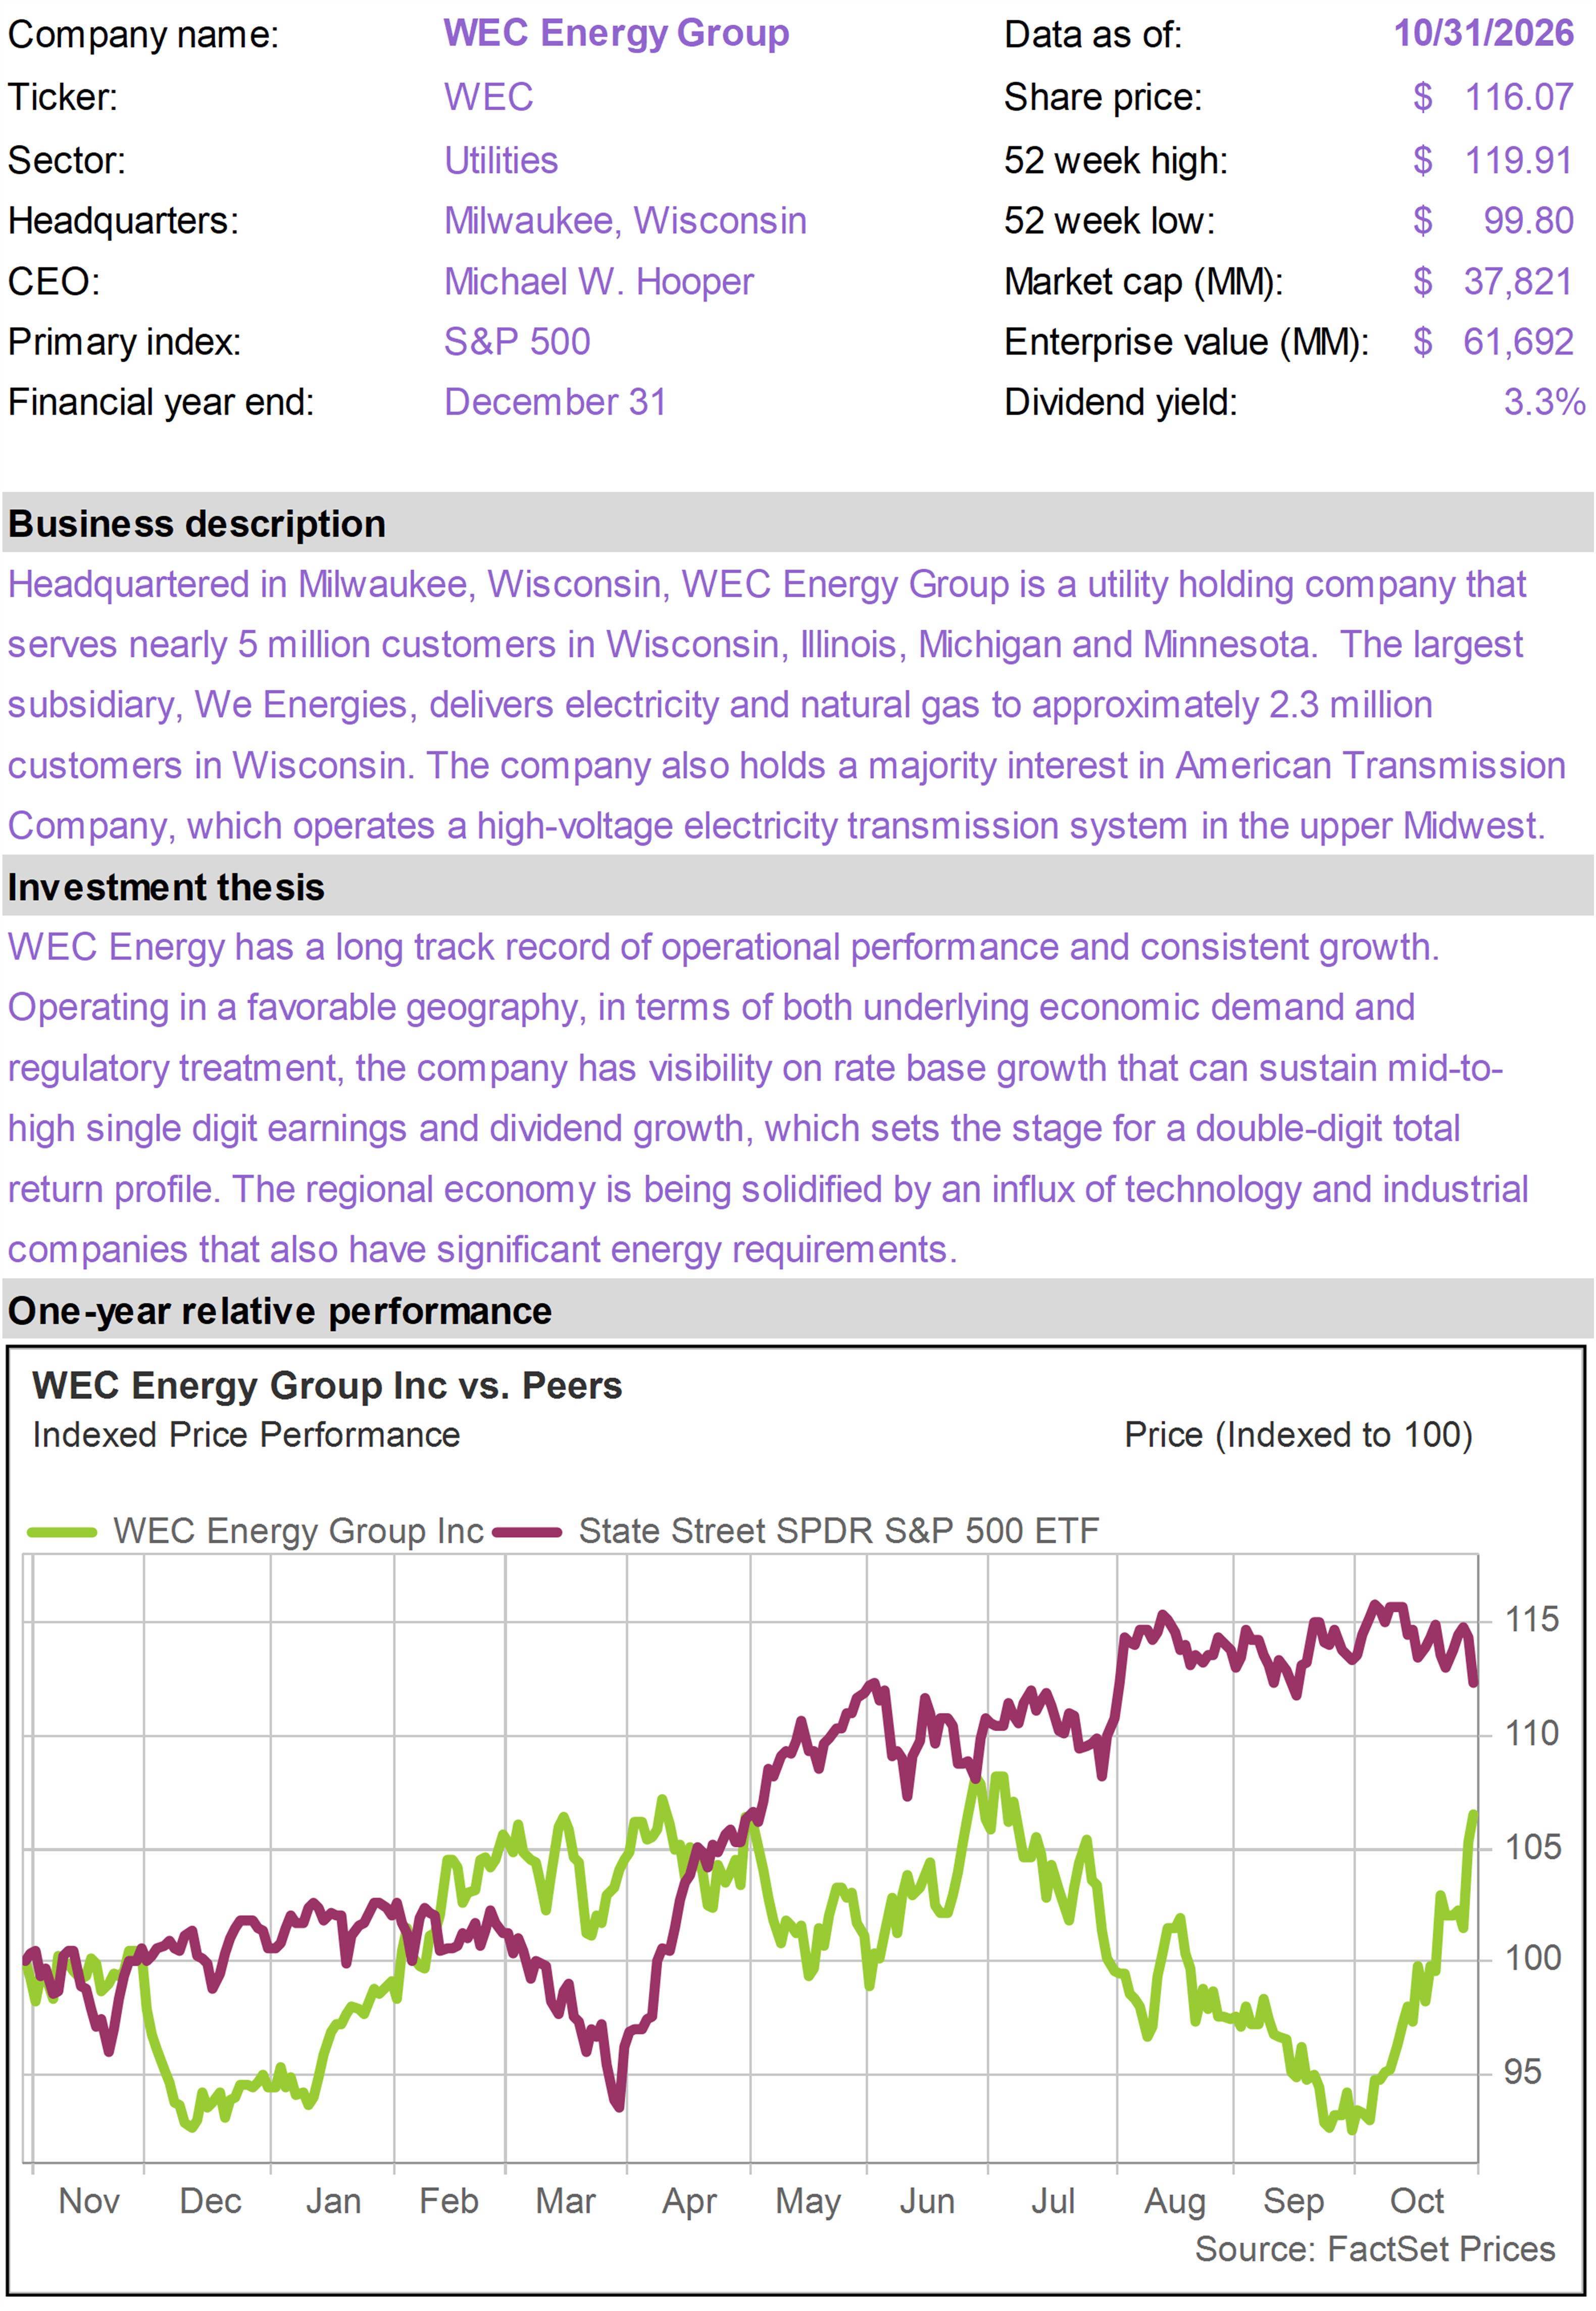
| | WEC gained in October, benefiting from declining long-term interest rates and growing investor enthusiasm for the company's expanding role in supplying electricity to major AI data centers.
WEC reported strong third quarter results, with earnings per share increasing 42% to $1.18, exceeding expectations. Management also raised its full-year earnings guidance to $5.60–$5.64 per share, supported by favorable weather, operational efficiencies, and growing electricity demand.
Perhaps the most significant development was management's announcement of a dramatically expanded capital investment plan, reflecting the extraordinary growth in electricity requirements from large technology companies.
WEC now expects to invest $47.5 billion between 2027 and 2031, an increase of $10 billion from its previous five-year plan.
The expansion is being driven largely by major data center projects under development by Microsoft (MSFT) and Oracle (ORCL) in Wisconsin.
MSFT is rapidly expanding its Mount Pleasant campus, with WEC now anticipating approximately 3.2 gigawatts of electricity demand across the surrounding region by 2031.
Meanwhile, ORCL's data center development in Port Washington is expected to require 1.3 gigawatts, with the potential to reach 3.5 gigawatts over time.
These projects require enormous investments in new generating capacity, transmission lines, and supporting electrical infrastructure.
Importantly, WEC operates under a special regulatory framework that requires these large customers to bear their share of infrastructure costs, protecting existing utility customers while allowing WEC to earn attractive regulated returns on new investments.
Through its approximately 60% ownership of American Transmission Company, WEC also stands to benefit from additional transmission investments, including a proposed $1.1 billion grid reliability project associated with ORCL's development.
Reflecting these opportunities, management increased its long-term earnings growth outlook to 7%–9% or more annually through 2031, up from its previous 7%–8% target.
WEC also expects to maintain annual dividend growth of approximately 6.5%–7%, providing an attractive combination of current income and long-term growth.
While regulatory approvals, project execution, and financing requirements remain important considerations, we believe the company's expanding investment opportunities provide considerable earnings visibility.
We continue to view WEC as a highly attractive utility investment, combining the stability of a regulated business with unusually strong growth opportunities arising from AI infrastructure investment and the broader electrification of the economy. |
|
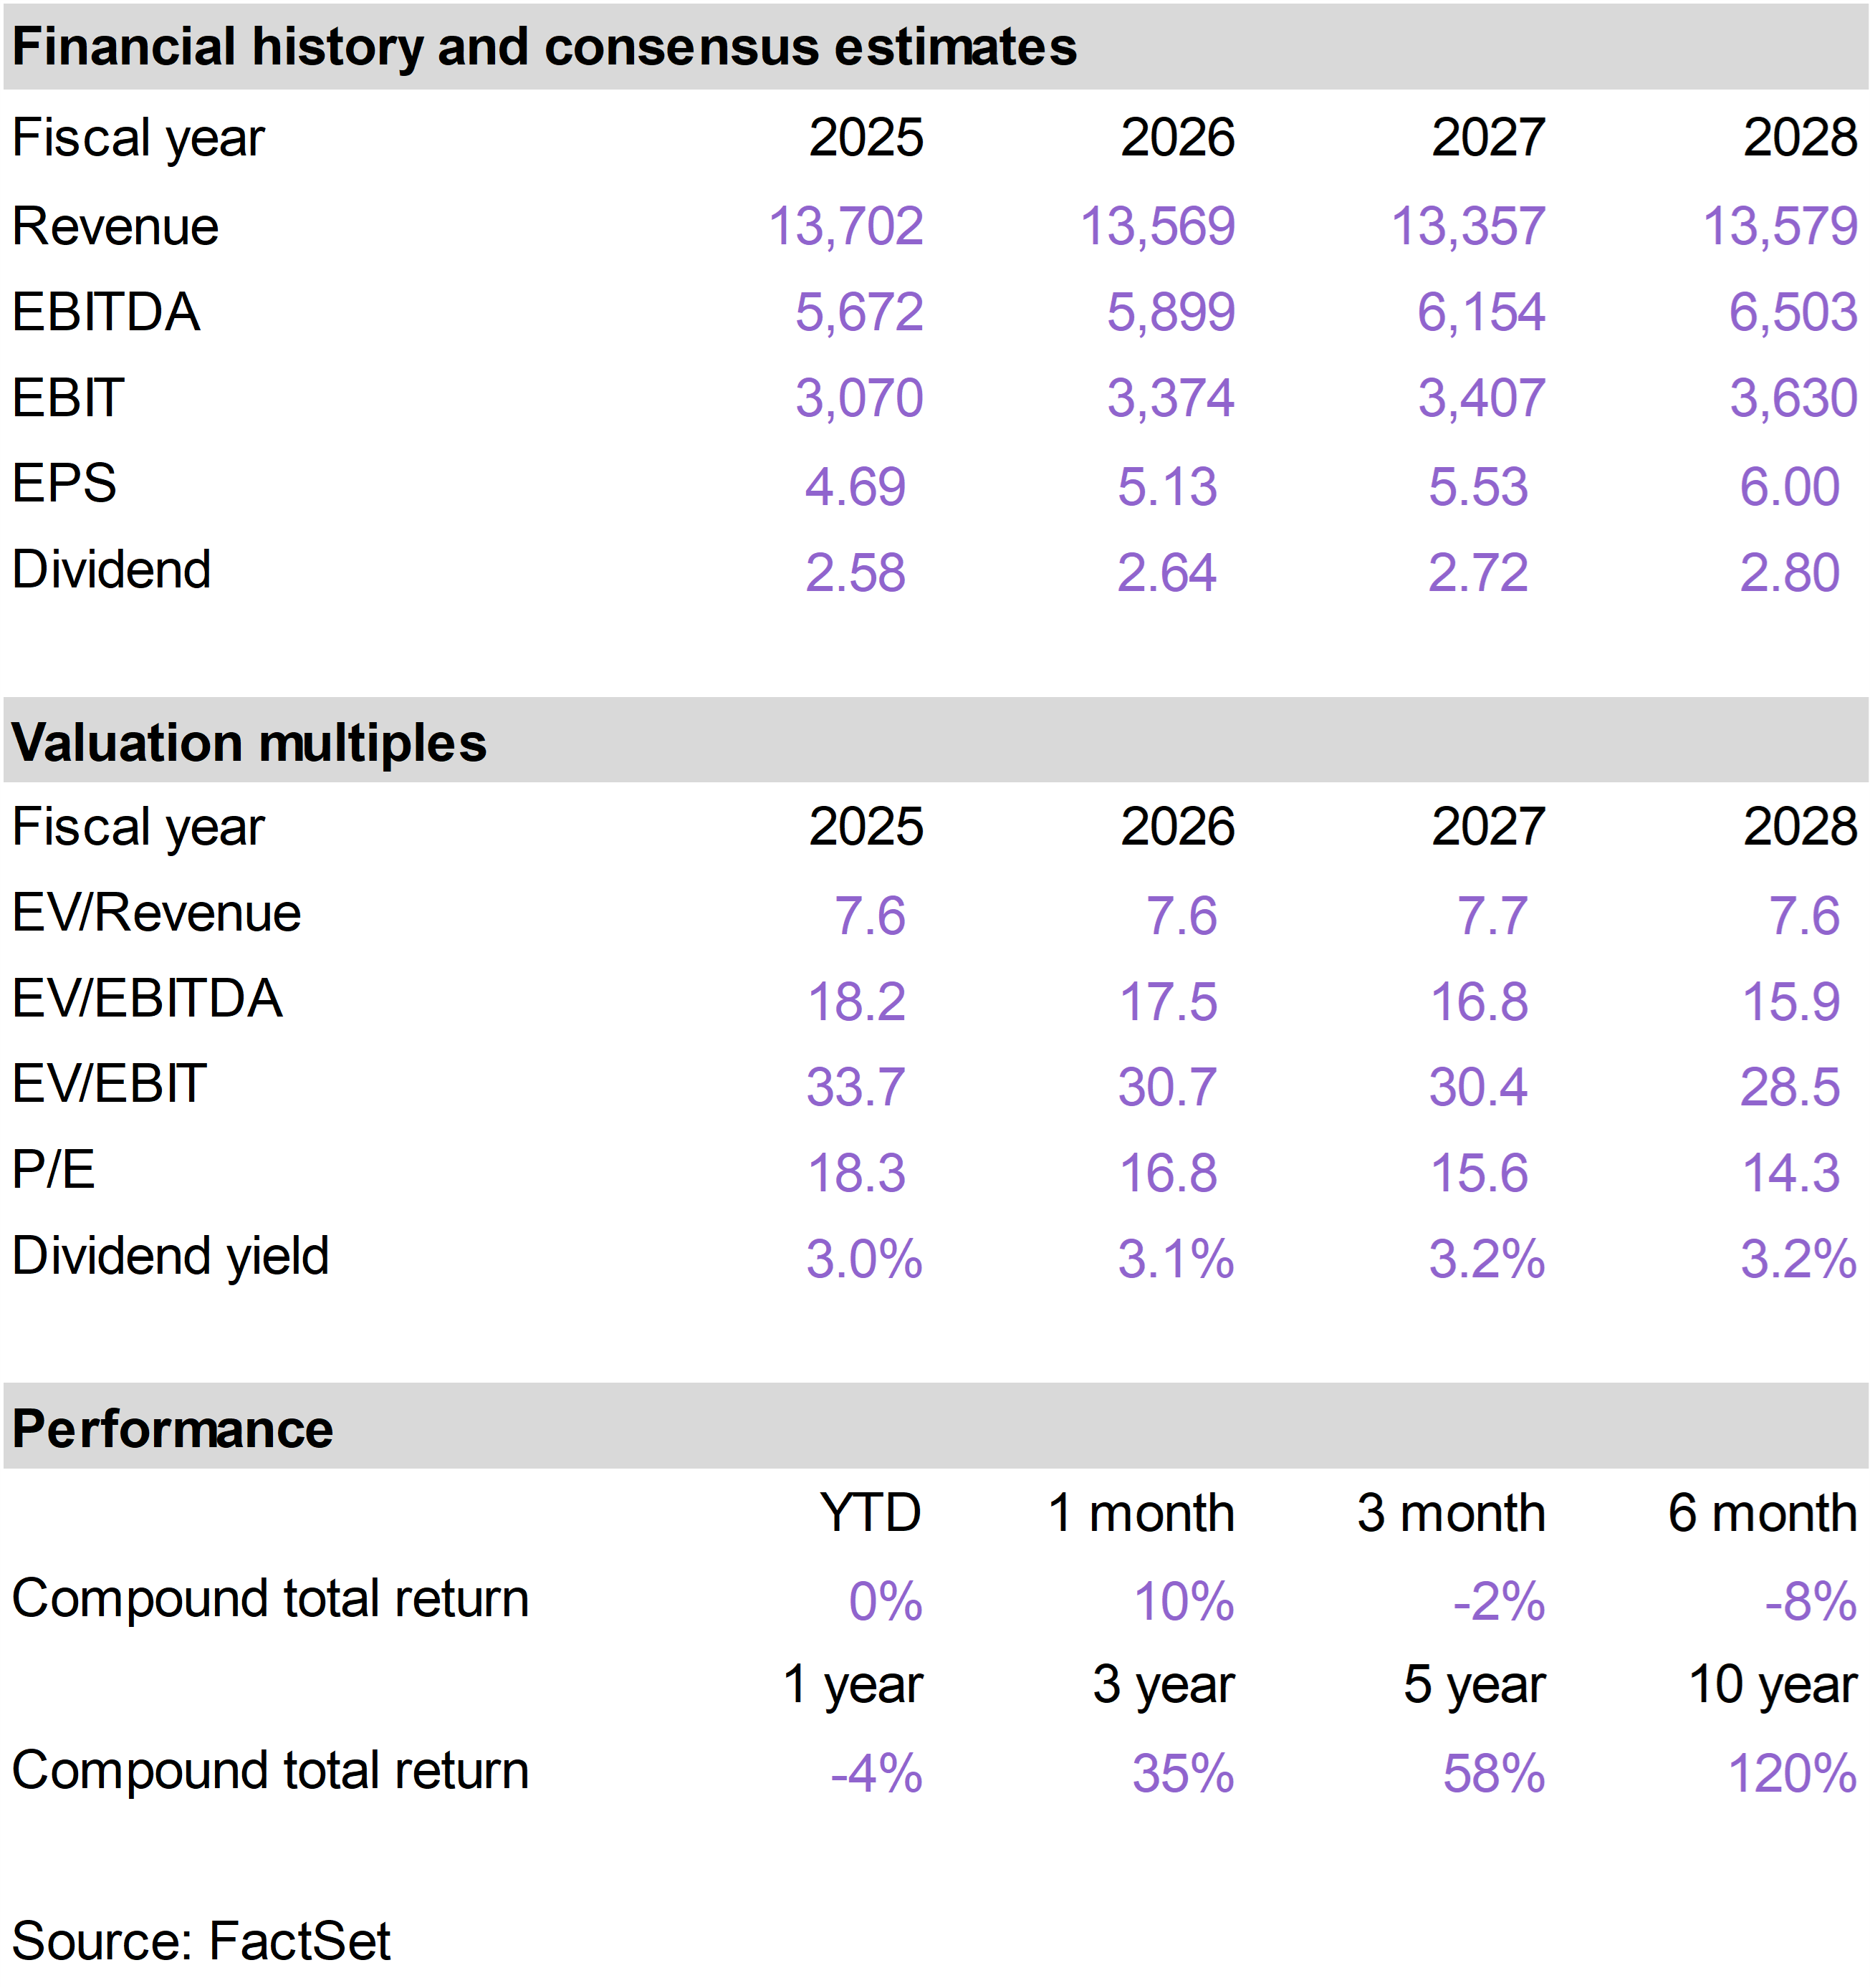
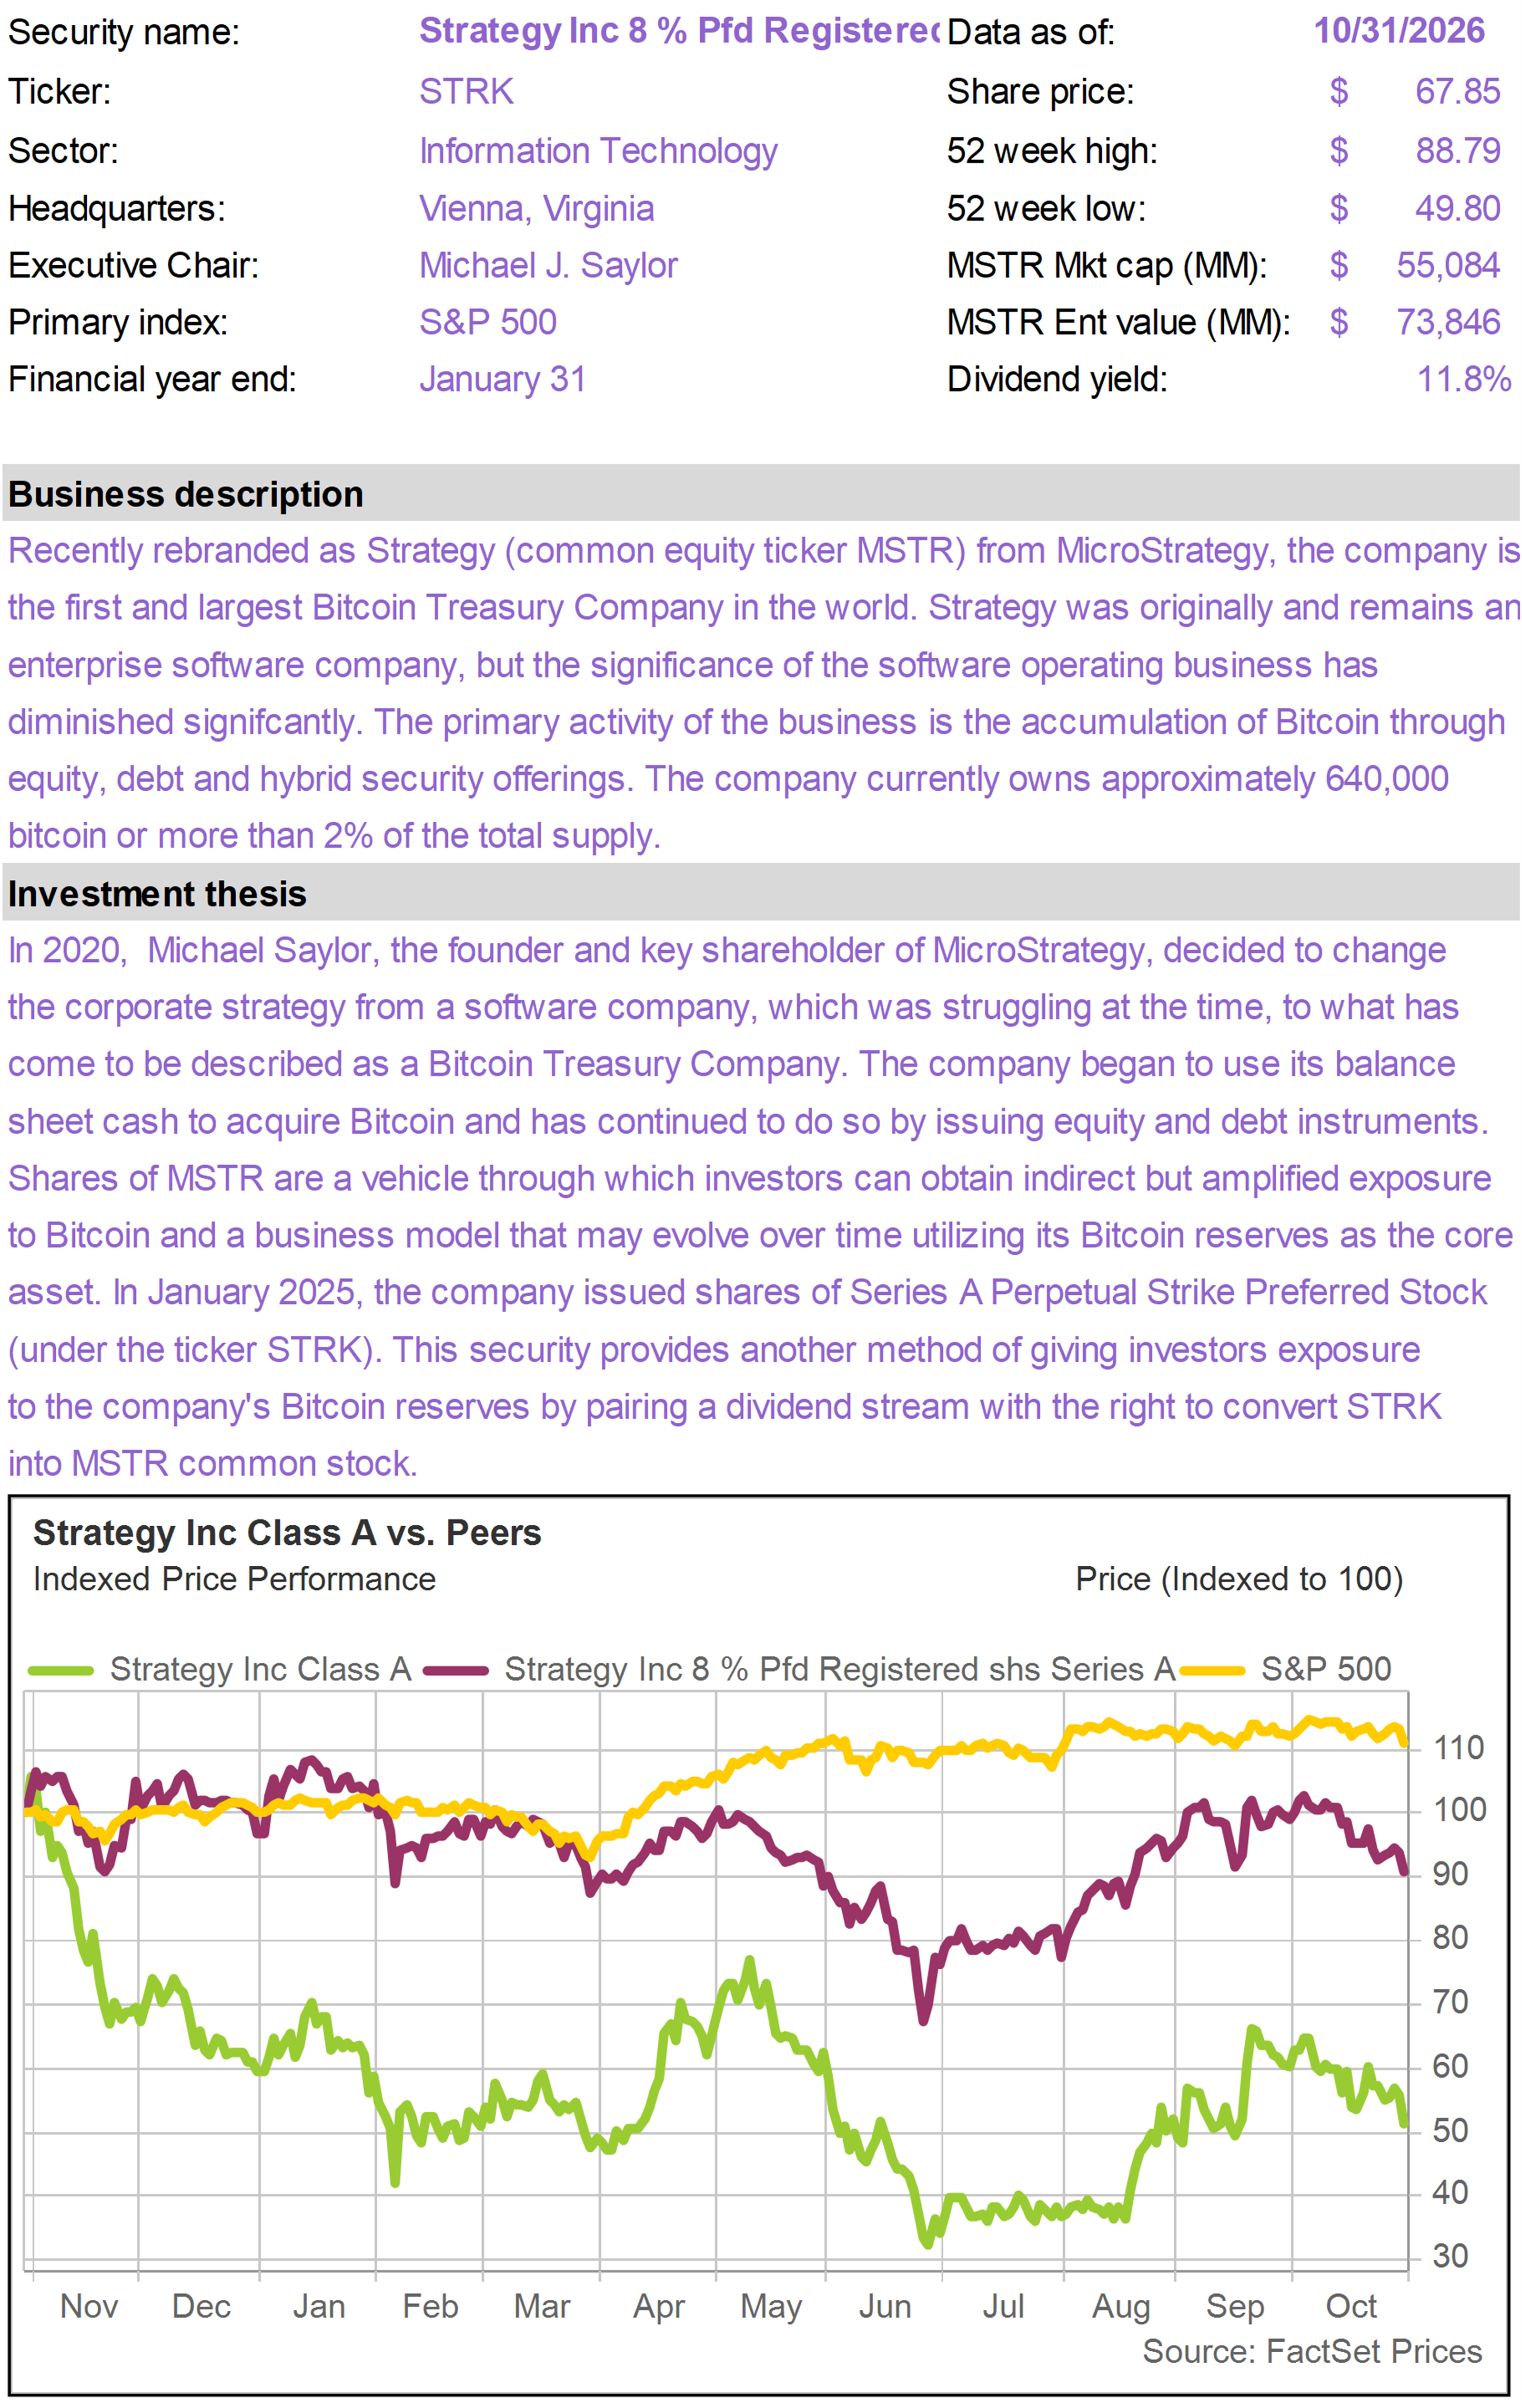
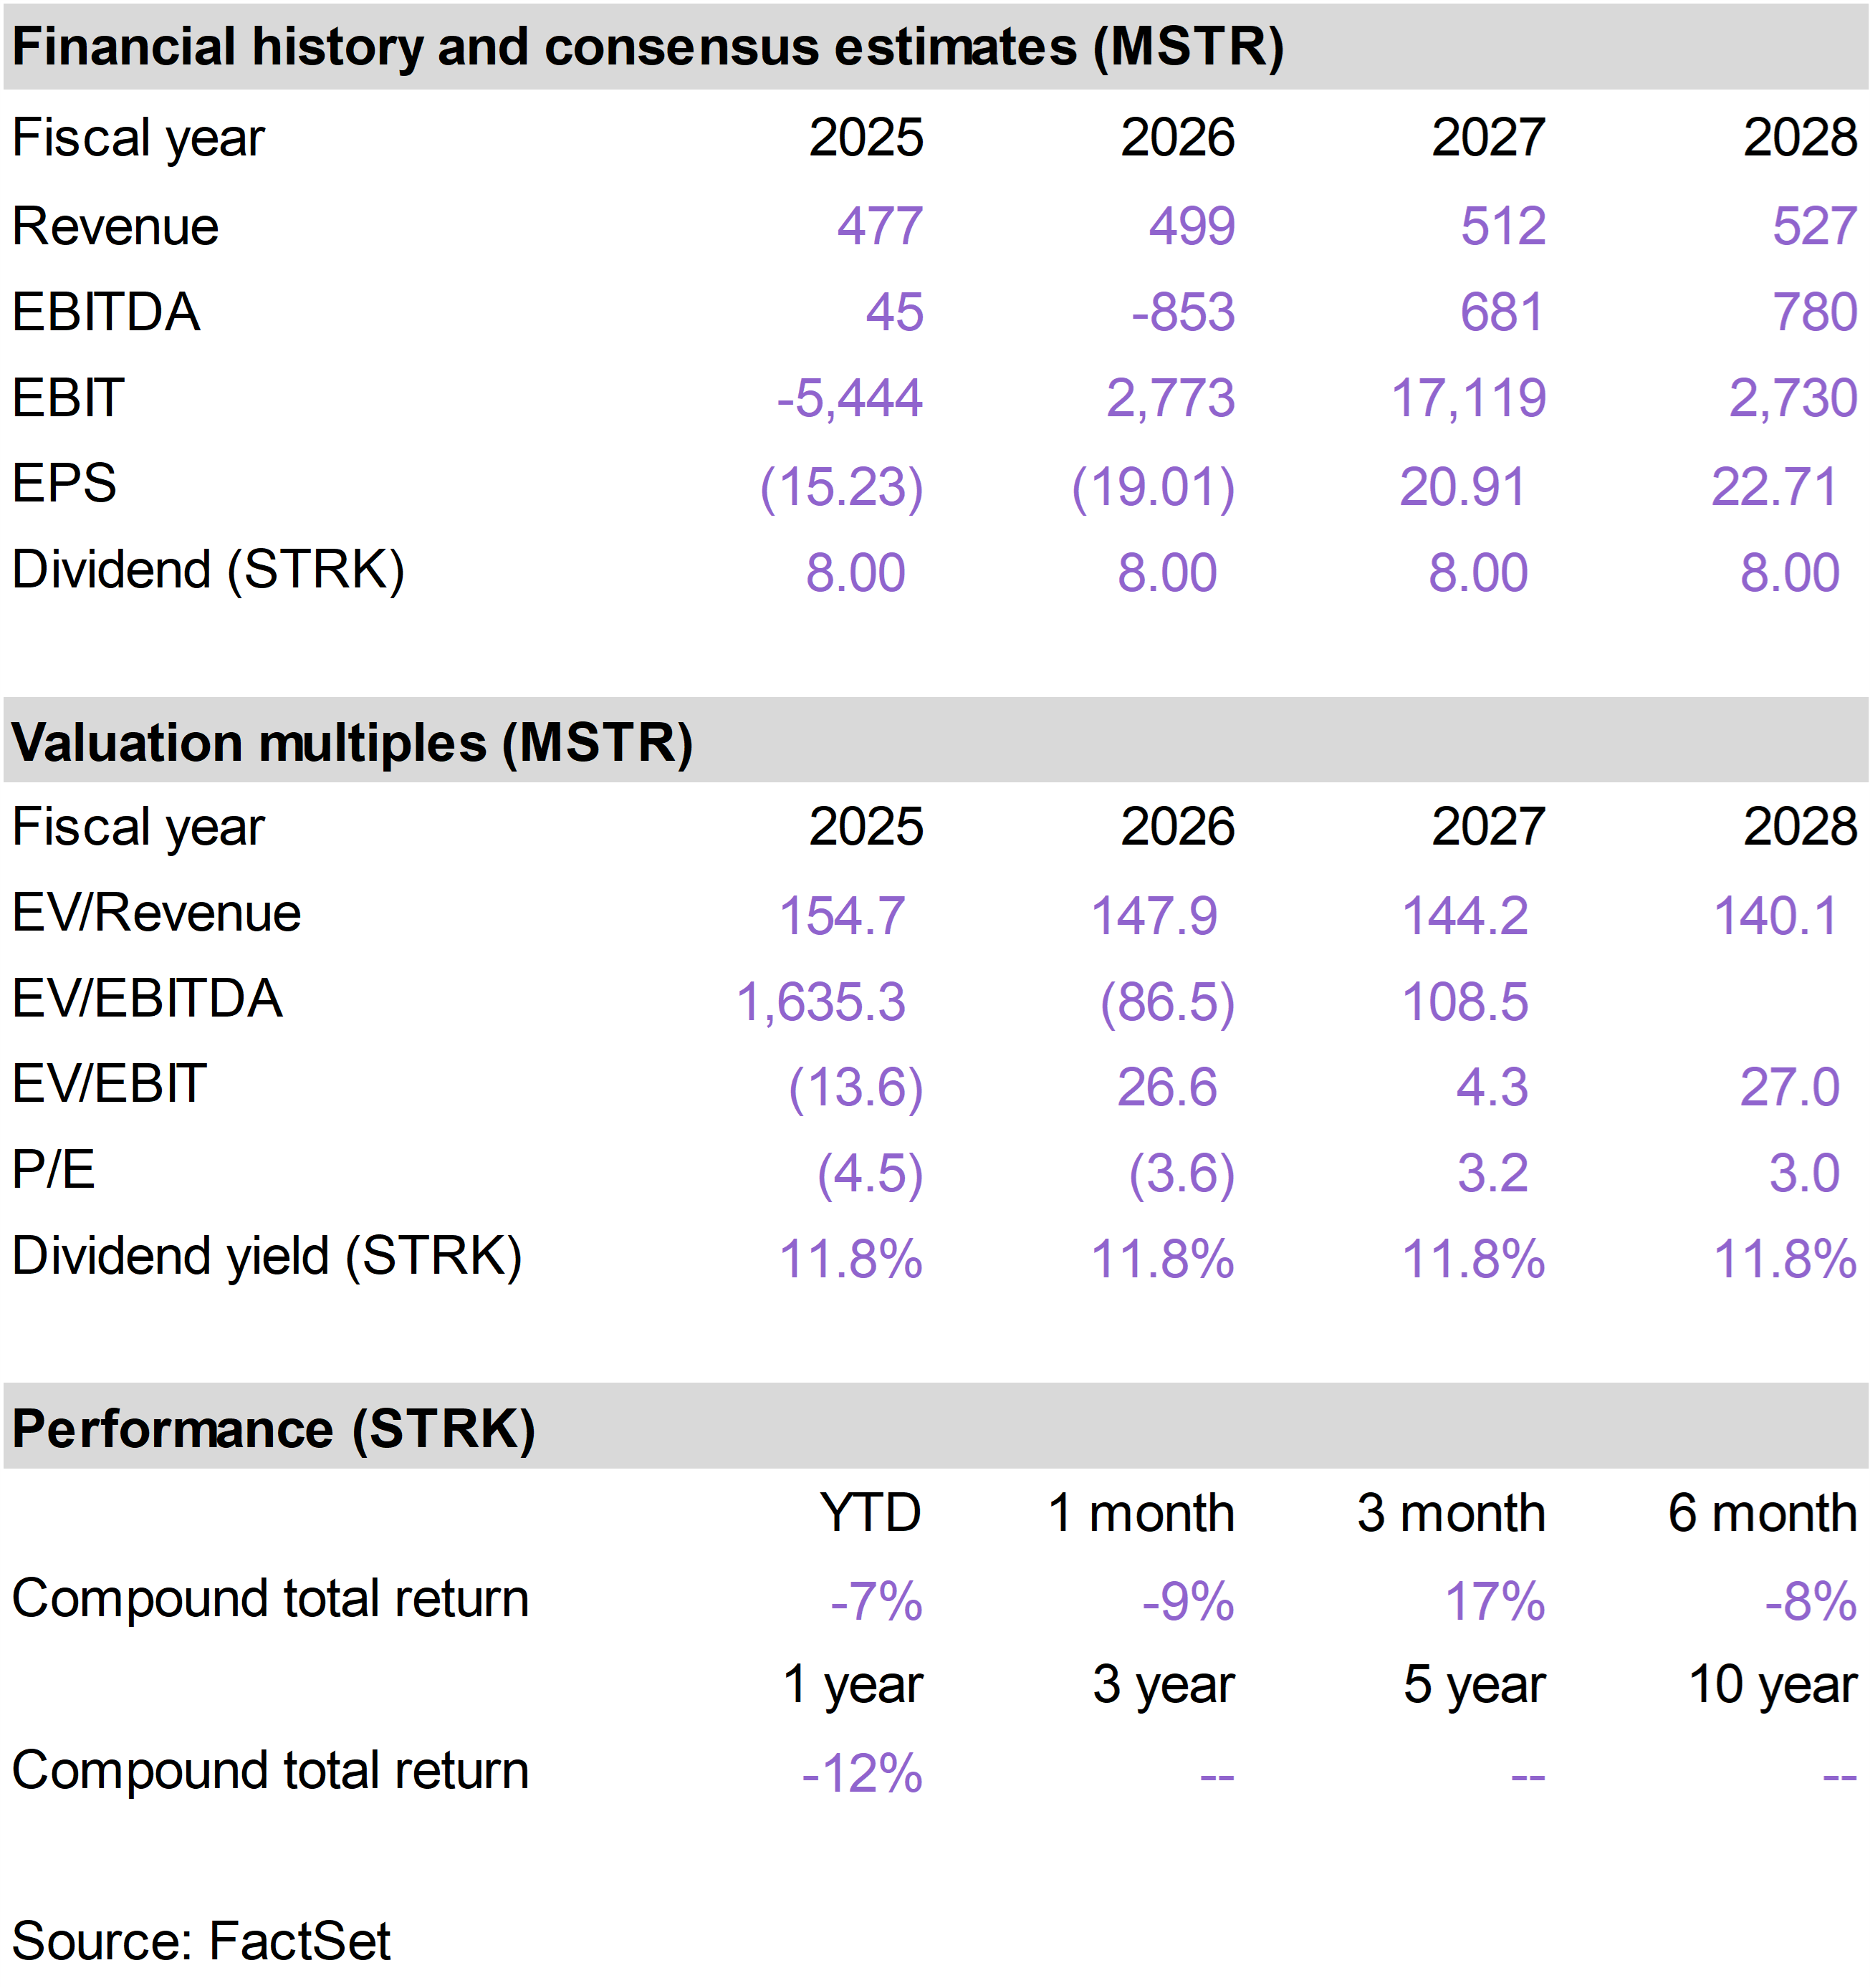
| | STRK declined in October, giving back its September gains as some renewed weakness in Bitcoin and Strategy common stock (MSTR) weighed on investor sentiment.
Bitcoin declined approximately 7% during the month, while MSTR shares fell 15%, reflecting broader selling pressure across the cryptocurrency sector.
The weakness intensified toward the end of October following a massive security breach at Binance, the world's largest cryptocurrency exchange.
On October 29, hackers stole approximately $6.3 billion in digital assets from Binance, triggering a sharp sell-off across the cryptocurrency market. The incident highlighted the continuing security risks associated with digital asset exchanges and custody arrangements.
Interestingly, the Binance incident also reinforces one of the attractions of gaining exposure to Bitcoin indirectly through publicly traded securities such as STRK.
Investors can participate in the Bitcoin ecosystem without having to manage private keys, maintain digital wallets, or entrust their assets to cryptocurrency exchanges.
Although STRK is a preferred security rather than common equity, its market value remains sensitive to perceptions of Strategy's financial strength and the value of its enormous Bitcoin holdings.
The company's financial position has improved substantially since the severe volatility experienced over the summer. At the end of October, Strategy held approximately 848,500 Bitcoin, while its cash and short-term investment reserves had increased to approximately $5.1 billion.
These reserves provide roughly 3.4 years of coverage for the company's preferred dividend and debt interest obligations, substantially reducing near-term liquidity concerns.
Another important development was shareholder approval on October 28 of a plan to transition Strategy's preferred securities to daily dividend payments.
Beginning January 1, 2027, STRK will accrue dividends every calendar day, including weekends and holidays, with payments scheduled for the following business day. The first payment is scheduled for January 4.
The change does not affect STRK's fixed annual dividend rate of 8%, based on its $100 stated value. However, more frequent payments should improve liquidity, reduce the price volatility associated with quarterly ex-dividend dates, and make the security more attractive to income-oriented investors.
At October's closing price of approximately $68, STRK offers a current annualized dividend yield of nearly 12%. These dividends are expected to be characterized as returns of capital and therefore not subject to U.S. income taxes for the foreseeable future.
STRK also retains its convertible feature, providing potential participation in MSTR's share price appreciation if Bitcoin experiences a sustained recovery.
We continue to view STRK as an attractive higher-risk income opportunity, offering substantial current yield alongside potential capital appreciation as confidence in Strategy and the broader cryptocurrency market recovers. |
|
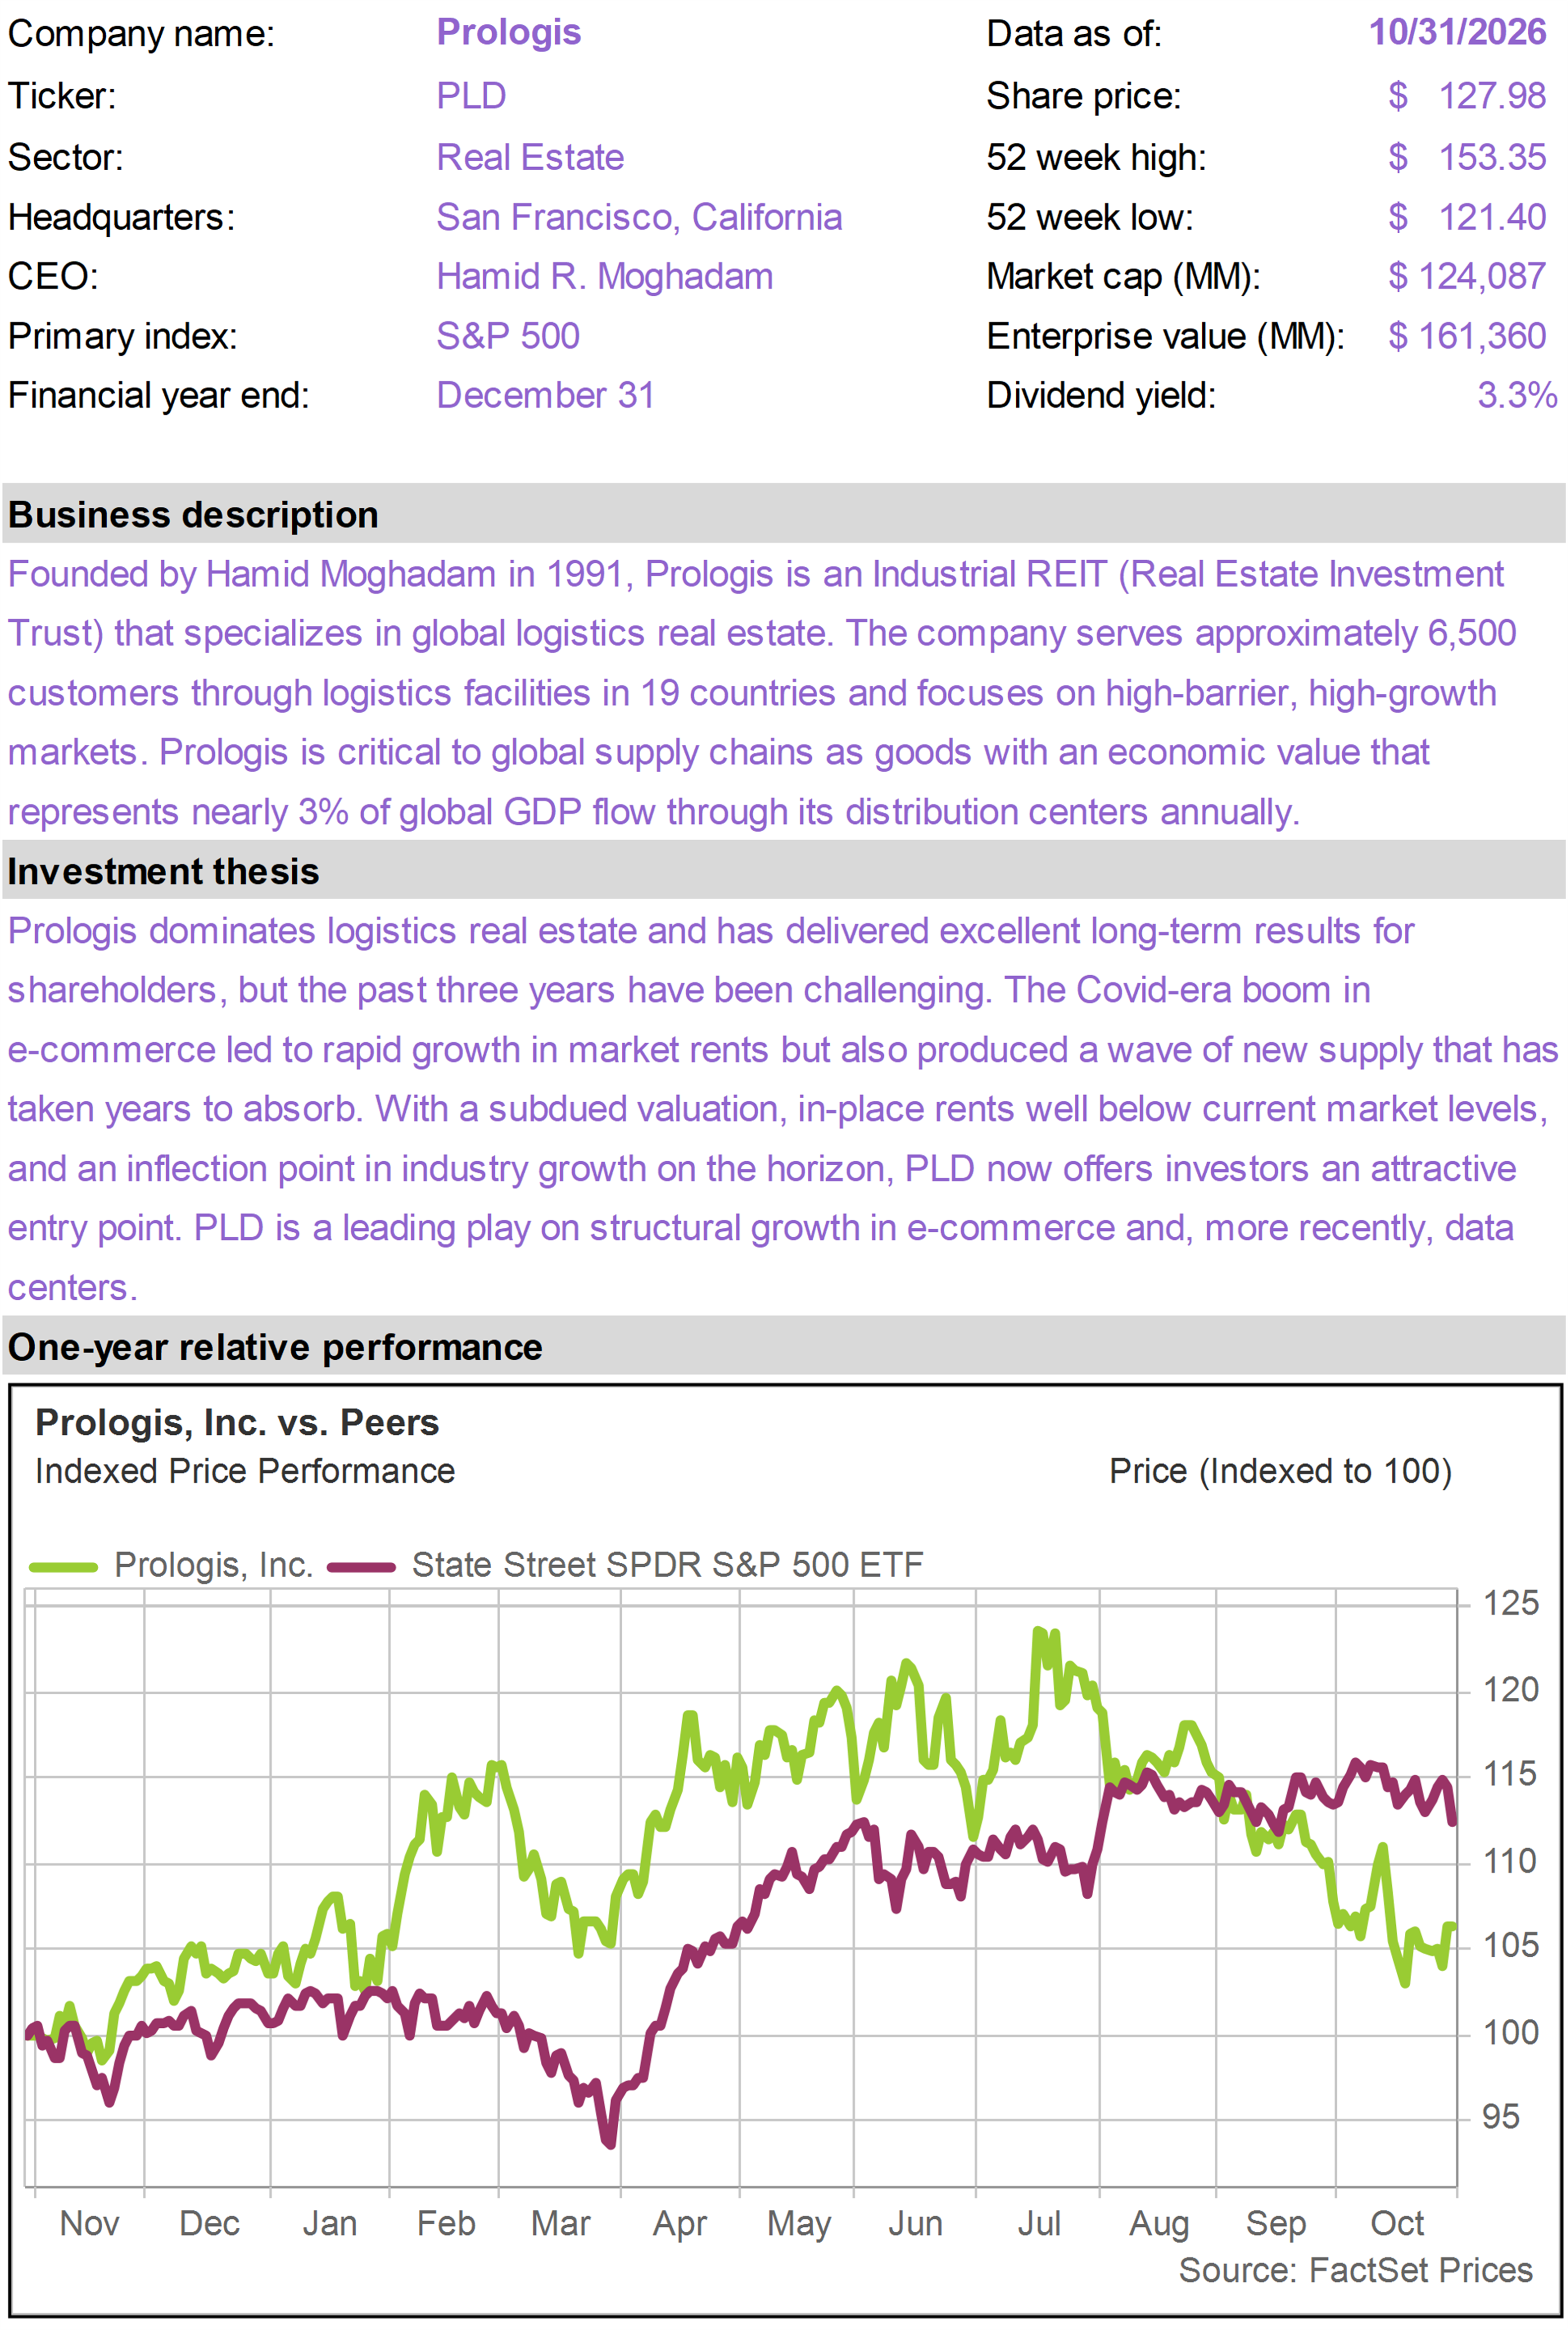
| | PLD declined modestly in October, despite the broader recovery in real estate stocks, as investors remained concerned about the company's pending acquisition of SEGRO and the impact of elevated borrowing costs on future earnings.
PLD reported solid third quarter results, with core funds from operations (FFO) per share increasing 7% to $1.60. Portfolio occupancy remained healthy at 95.6%, while cash same-store net operating income increased 5.9%.
Leasing activity continues to improve, supported by e-commerce, advanced manufacturing, and businesses supplying the rapidly expanding data center industry.
The company also benefits from substantial embedded rent growth. Cash rents on newly commenced leases increased 23% relative to expiring leases, reflecting the significant appreciation in market rents over the past several years.
Management raised its full-year outlook for same-store net operating income growth, although it modestly reduced occupancy expectations.
An important source of uncertainty remains PLD's pending acquisition of SEGRO, a major European logistics property owner. The transaction, expected to close during the first half of 2027, will significantly expand PLD's international footprint.
While the acquisition offers strategic benefits, investors remain concerned about financing costs, integration risks, and the near-term impact on earnings.
Meanwhile, PLD continues to pursue an ambitious strategy in data center development, leveraging its extensive land holdings, infrastructure relationships, and ability to secure electricity capacity.
The company has secured approximately 1.7 gigawatts of power for potential data center projects and anticipates beginning construction on approximately 1 gigawatt in 2027.
Demand for warehouses supporting data center construction is also accelerating. Approximately 17% of new leasing activity during the third quarter came from businesses supplying the data center industry.
We believe this creates a compelling opportunity for PLD to participate in the AI infrastructure investment cycle through both traditional logistics properties and new development initiatives.
Despite these opportunities, the stock continues to trade at a meaningful discount to estimated net asset value, reflecting uncertainty surrounding interest rates and the SEGRO transaction.
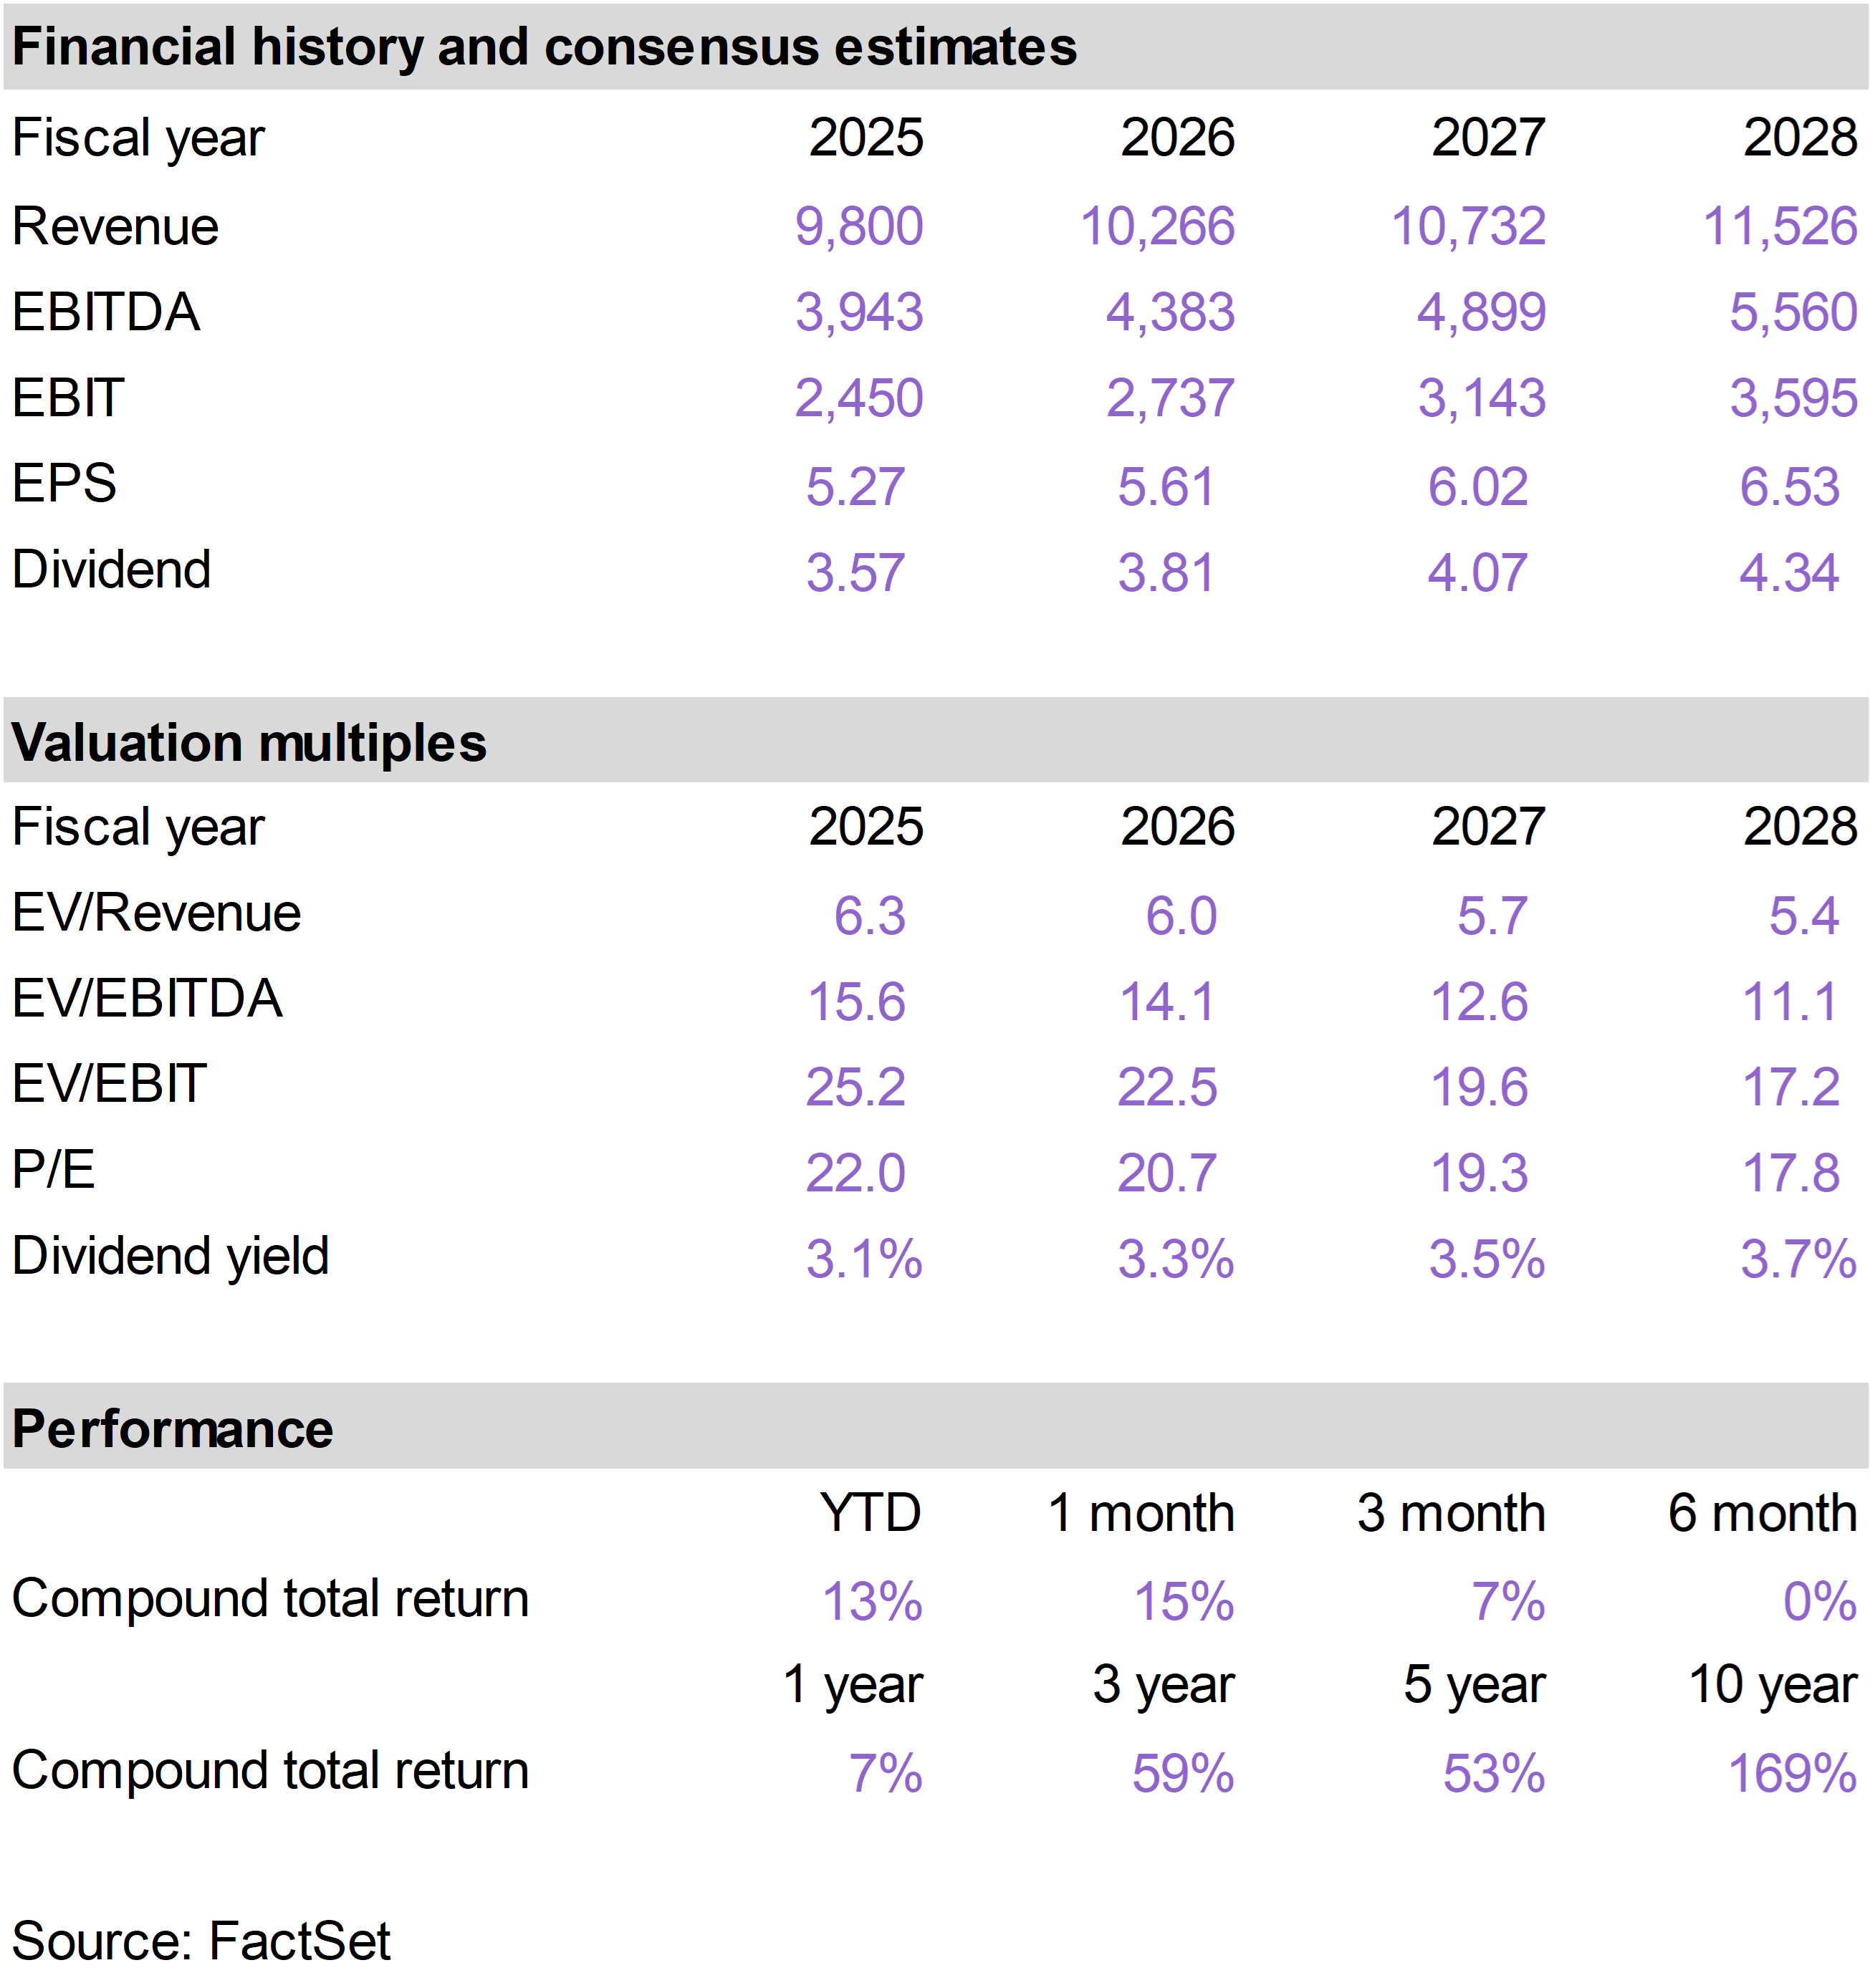
With an annual dividend of $4.28 per share, yielding approximately 3.3%, PLD offers an attractive combination of current income and long-term growth potential.
We continue to view PLD as a well-managed real estate business with significant competitive advantages. As industrial property fundamentals improve and interest rates potentially decline further, we believe the shares offer substantial upside from current valuations. |
|
| | | |
| | |
| | |
| | | |
|
| | Digital Realty Trust (DLR) |
|
|
|
| | |
|
| | |
|
| | |
|
| | |
|
| | |
|
| | Diamondback Energy (FANG) |
|
|
|
| | |
|
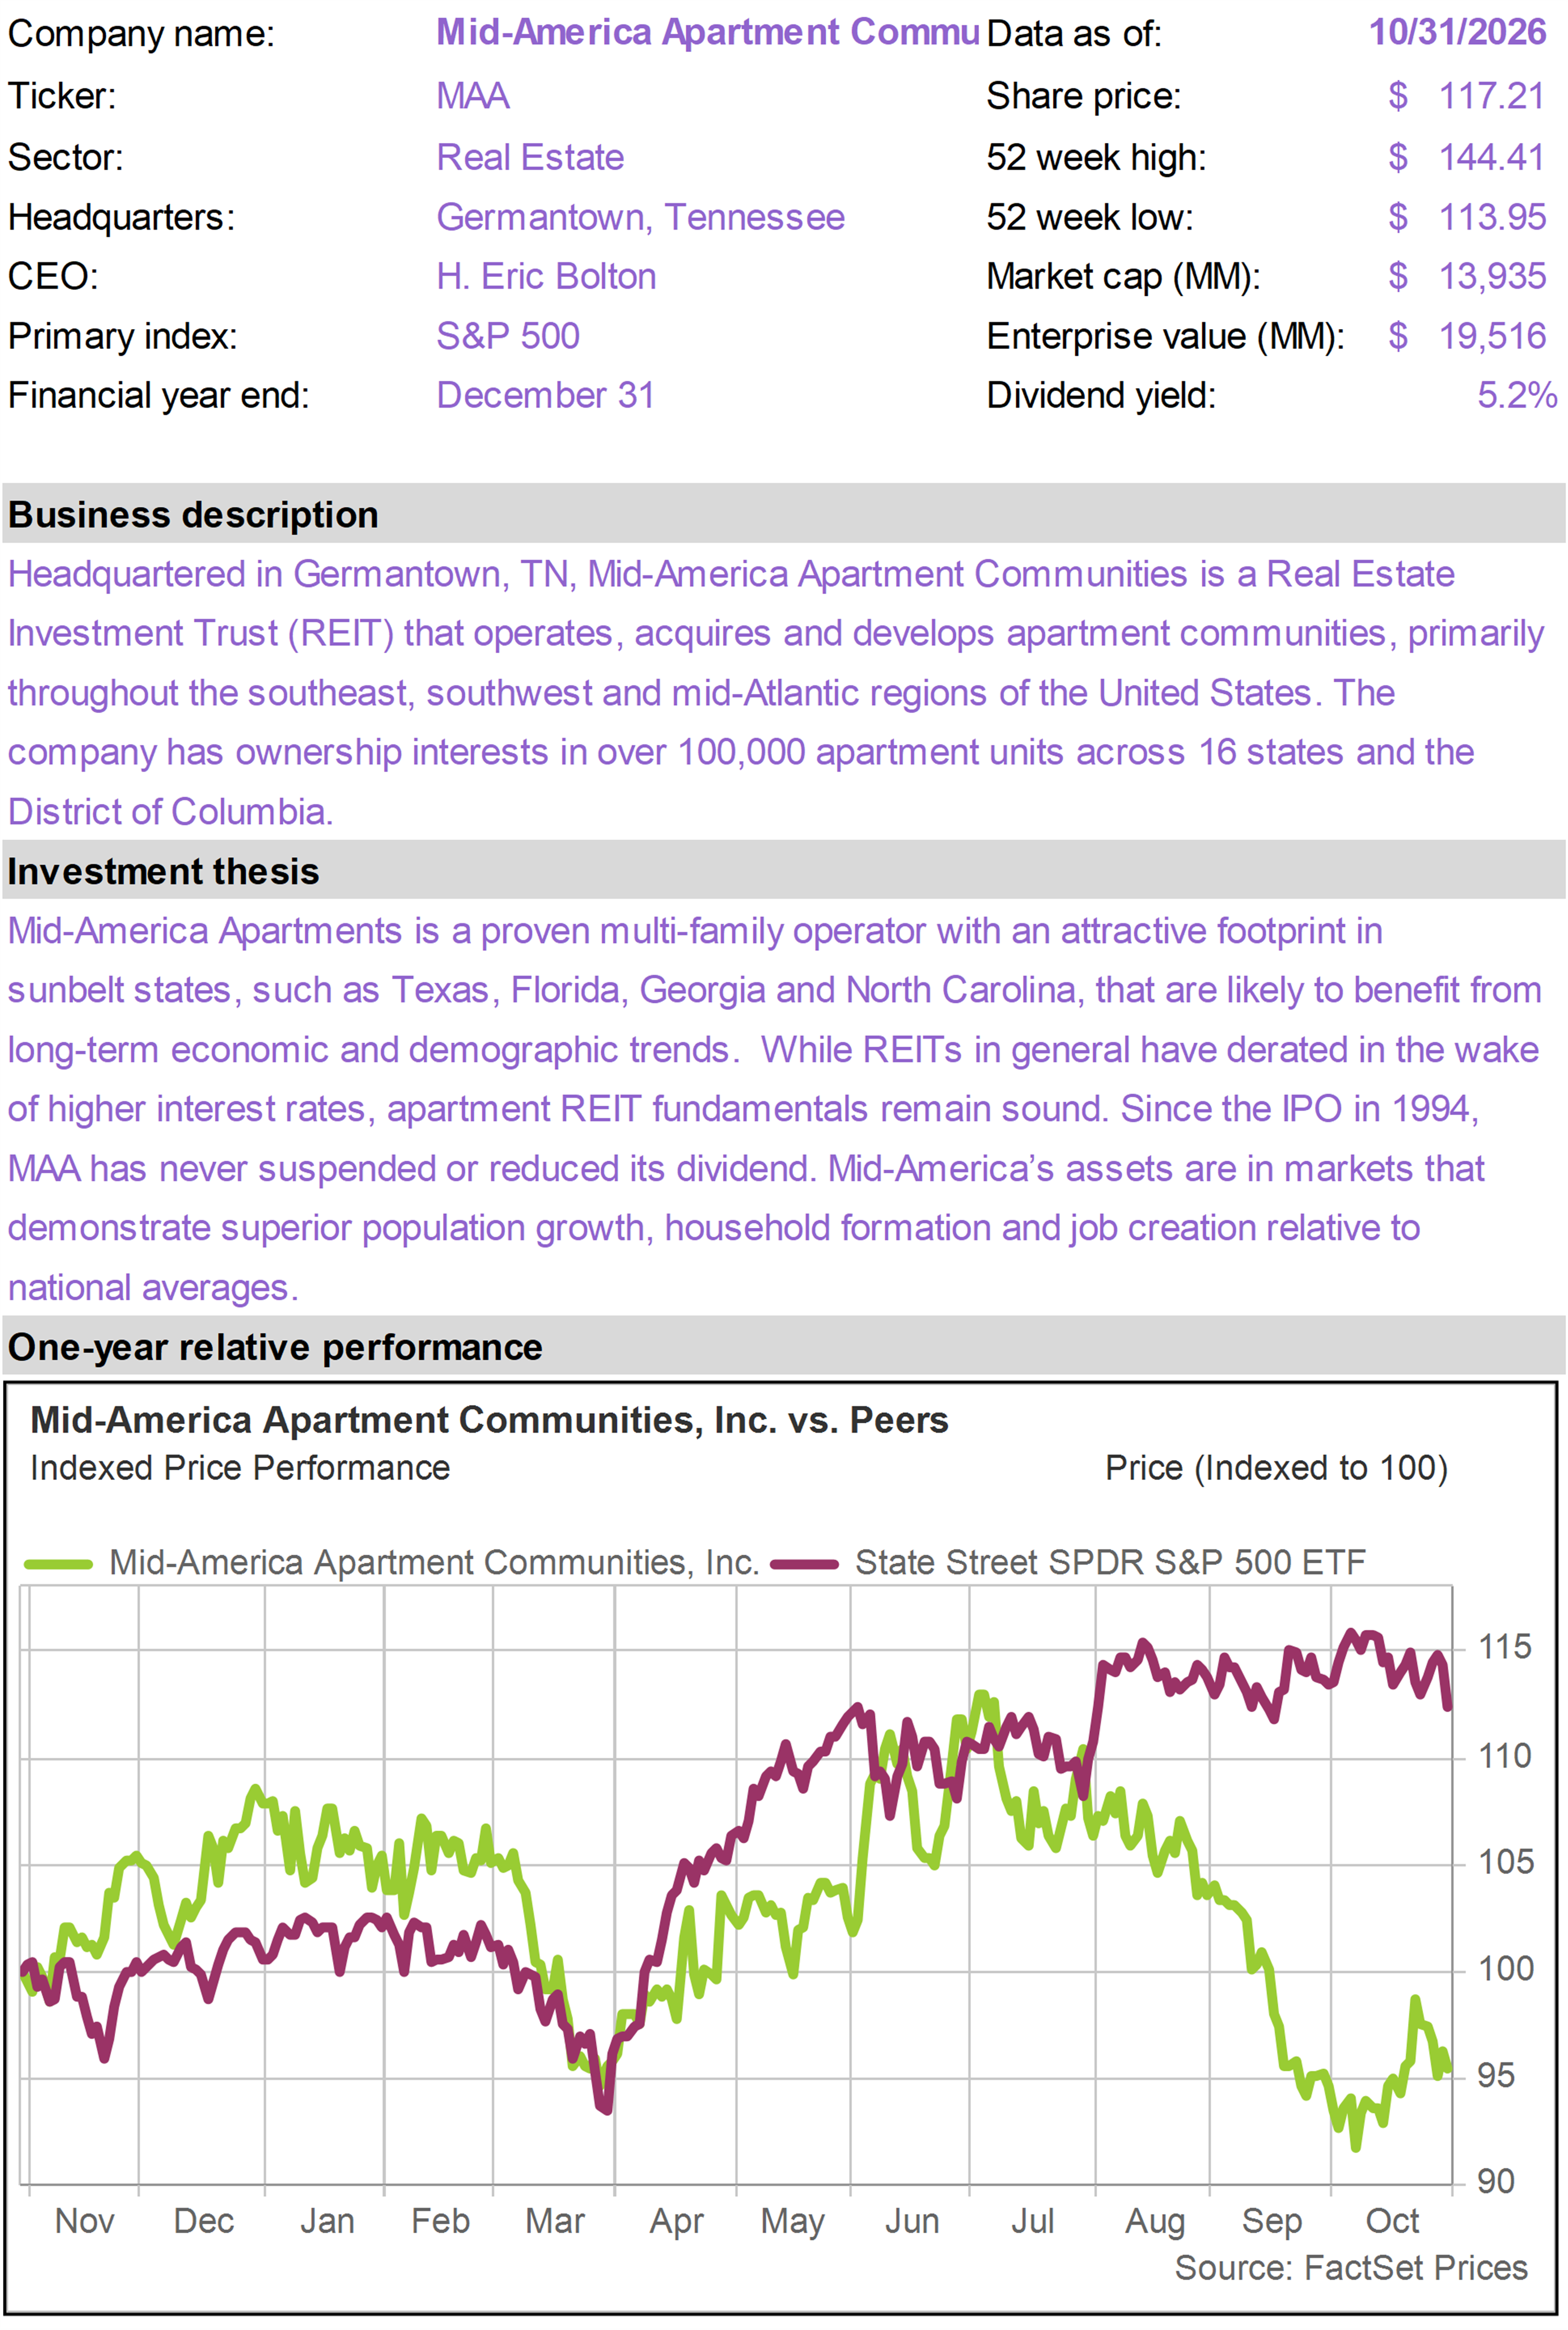
| | Mid-America Apartment (MAA) |
|
|
|
| | |
|
| | |
|
| | |
|
| | Strategy 8% Perpetual Pref (STRK) |
|
|
|
| | |
|
| | The 76research Income Builder Model Portfolio is intended for income-oriented investors and managed to generate an overall yield that is materially higher than broad equity indices. The portfolio includes stocks with above average dividend yields from a cross section of industries. While investments are screened for their income and income growth characteristics, specific holdings are chosen based on valuation and general business quality, growth and risk considerations. |
|
| | FOR SUBSCRIBER USE ONLY. DO NOT FORWARD OR SHARE. |
|
| | | |
|
|
|
|
|