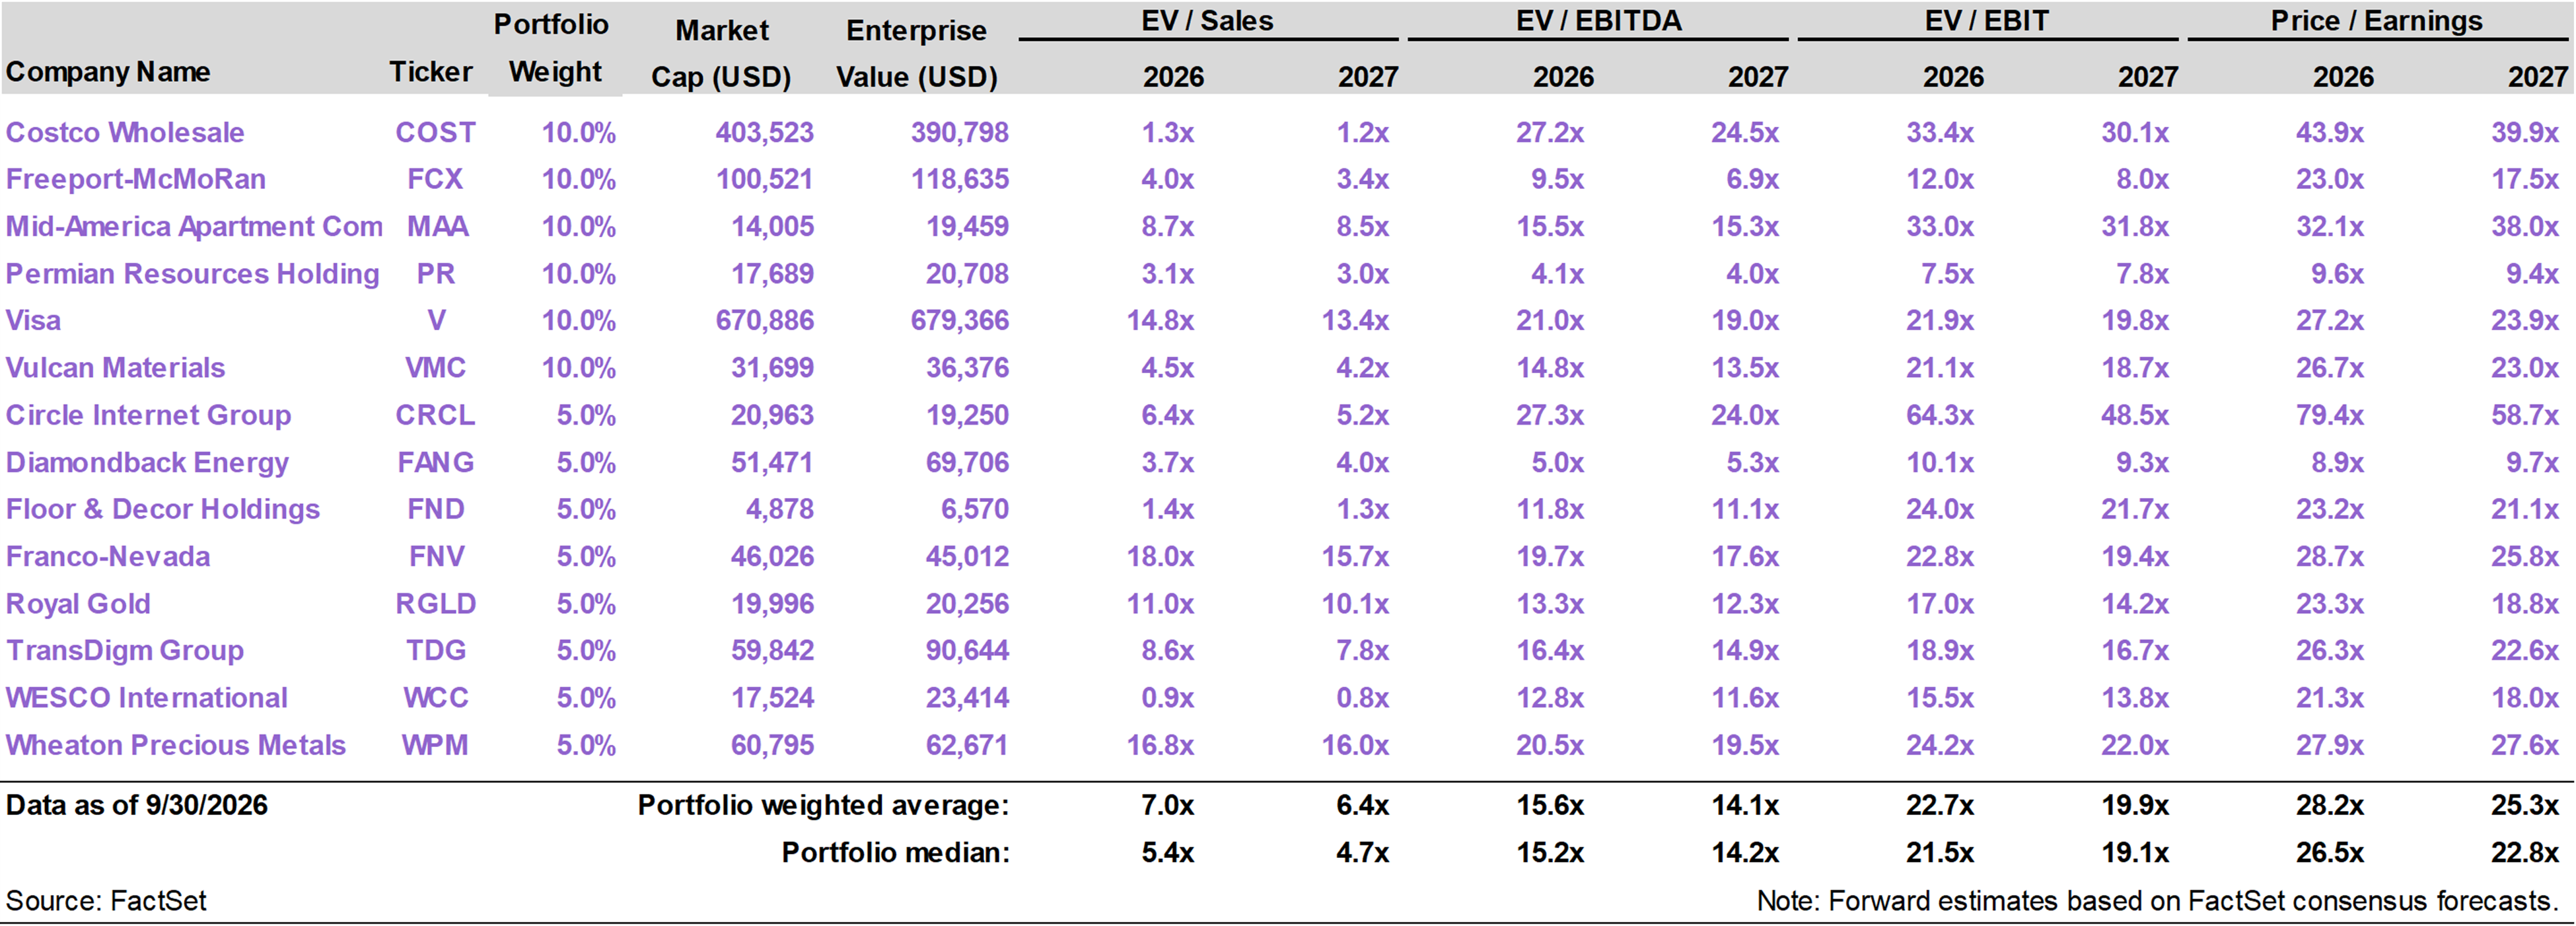
| Inflation Protection Model Portfolio |
|
| Monthly Portfolio Review: September 2026Publication date: October 5, 2026 |
|
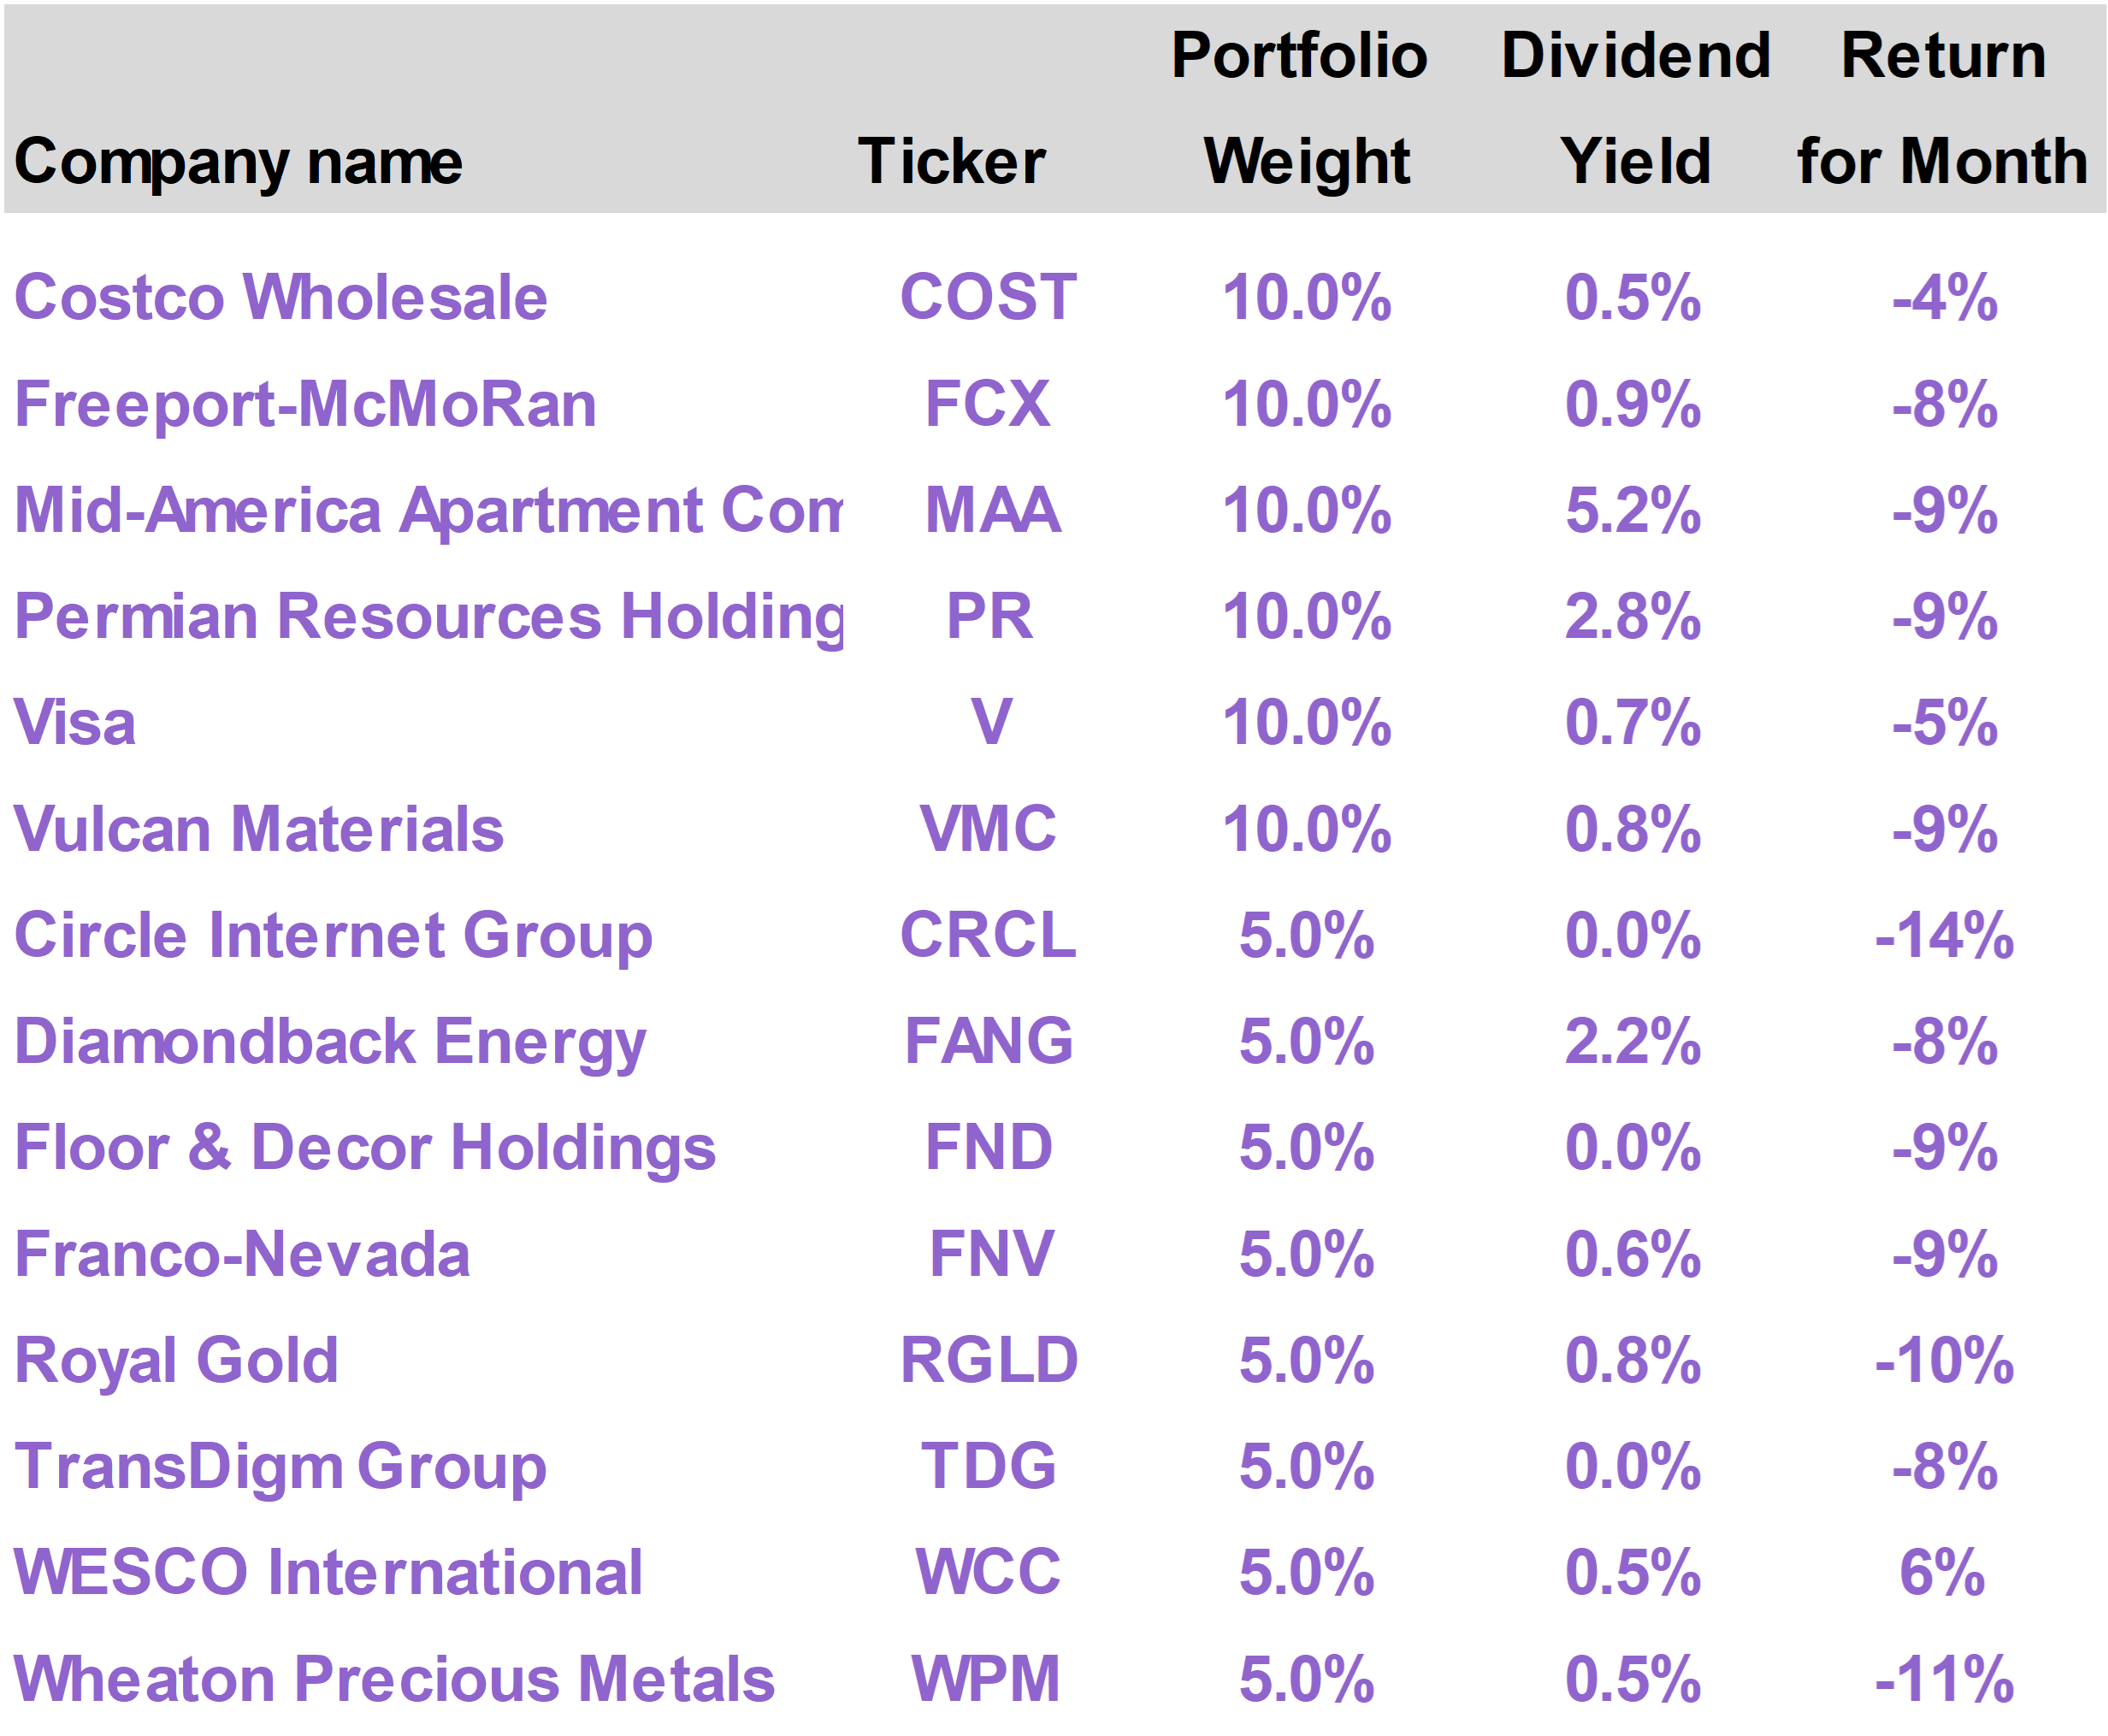
| | | Current portfolio holdings |
|
|
| | FOR SUBSCRIBER USE ONLY. DO NOT FORWARD OR SHARE. |
|
| | | September was a difficult month for most of the market outside a narrow group of AI-related Technology stocks. The S&P 500 Equal Weight Index declined 4.8%, even as the standard S&P 500 Index, propped up by mega-cap tech, was only slightly down. Sharply higher short- and long-term interest rates dominated the macro picture. Treasury bond yields rose approximately half a percent as additional Fed rate hikes got priced in. Gold came under significant pressure as real rates spiked and the dollar strengthened, reversing August’s strong rally. The Inflation Protection portfolio returned -7.5% this month. On a year to date basis, the portfolio has returned 15.1%, versus 12.7% for the S&P 500. The softer September employment report suggests the market may have become too pessimistic on interest rates. If real yields begin to stabilize or move lower, gold and other rate-sensitive Inflation Protection holdings could see a meaningful rebound.
|
|
| | | The Inflation Protection portfolio returned -7.5% in September, versus the S&P 500 Index return of -0.4%. On a year to date basis through the end of the month, the portfolio has generated a total return of 15.1%, versus the 12.7% return of the S&P 500.
The portfolio’s top performing stocks this month were WESCO International (WCC), which returned 6%; Costco (COST), which returned -4%; and Visa (V), which returned -5%.
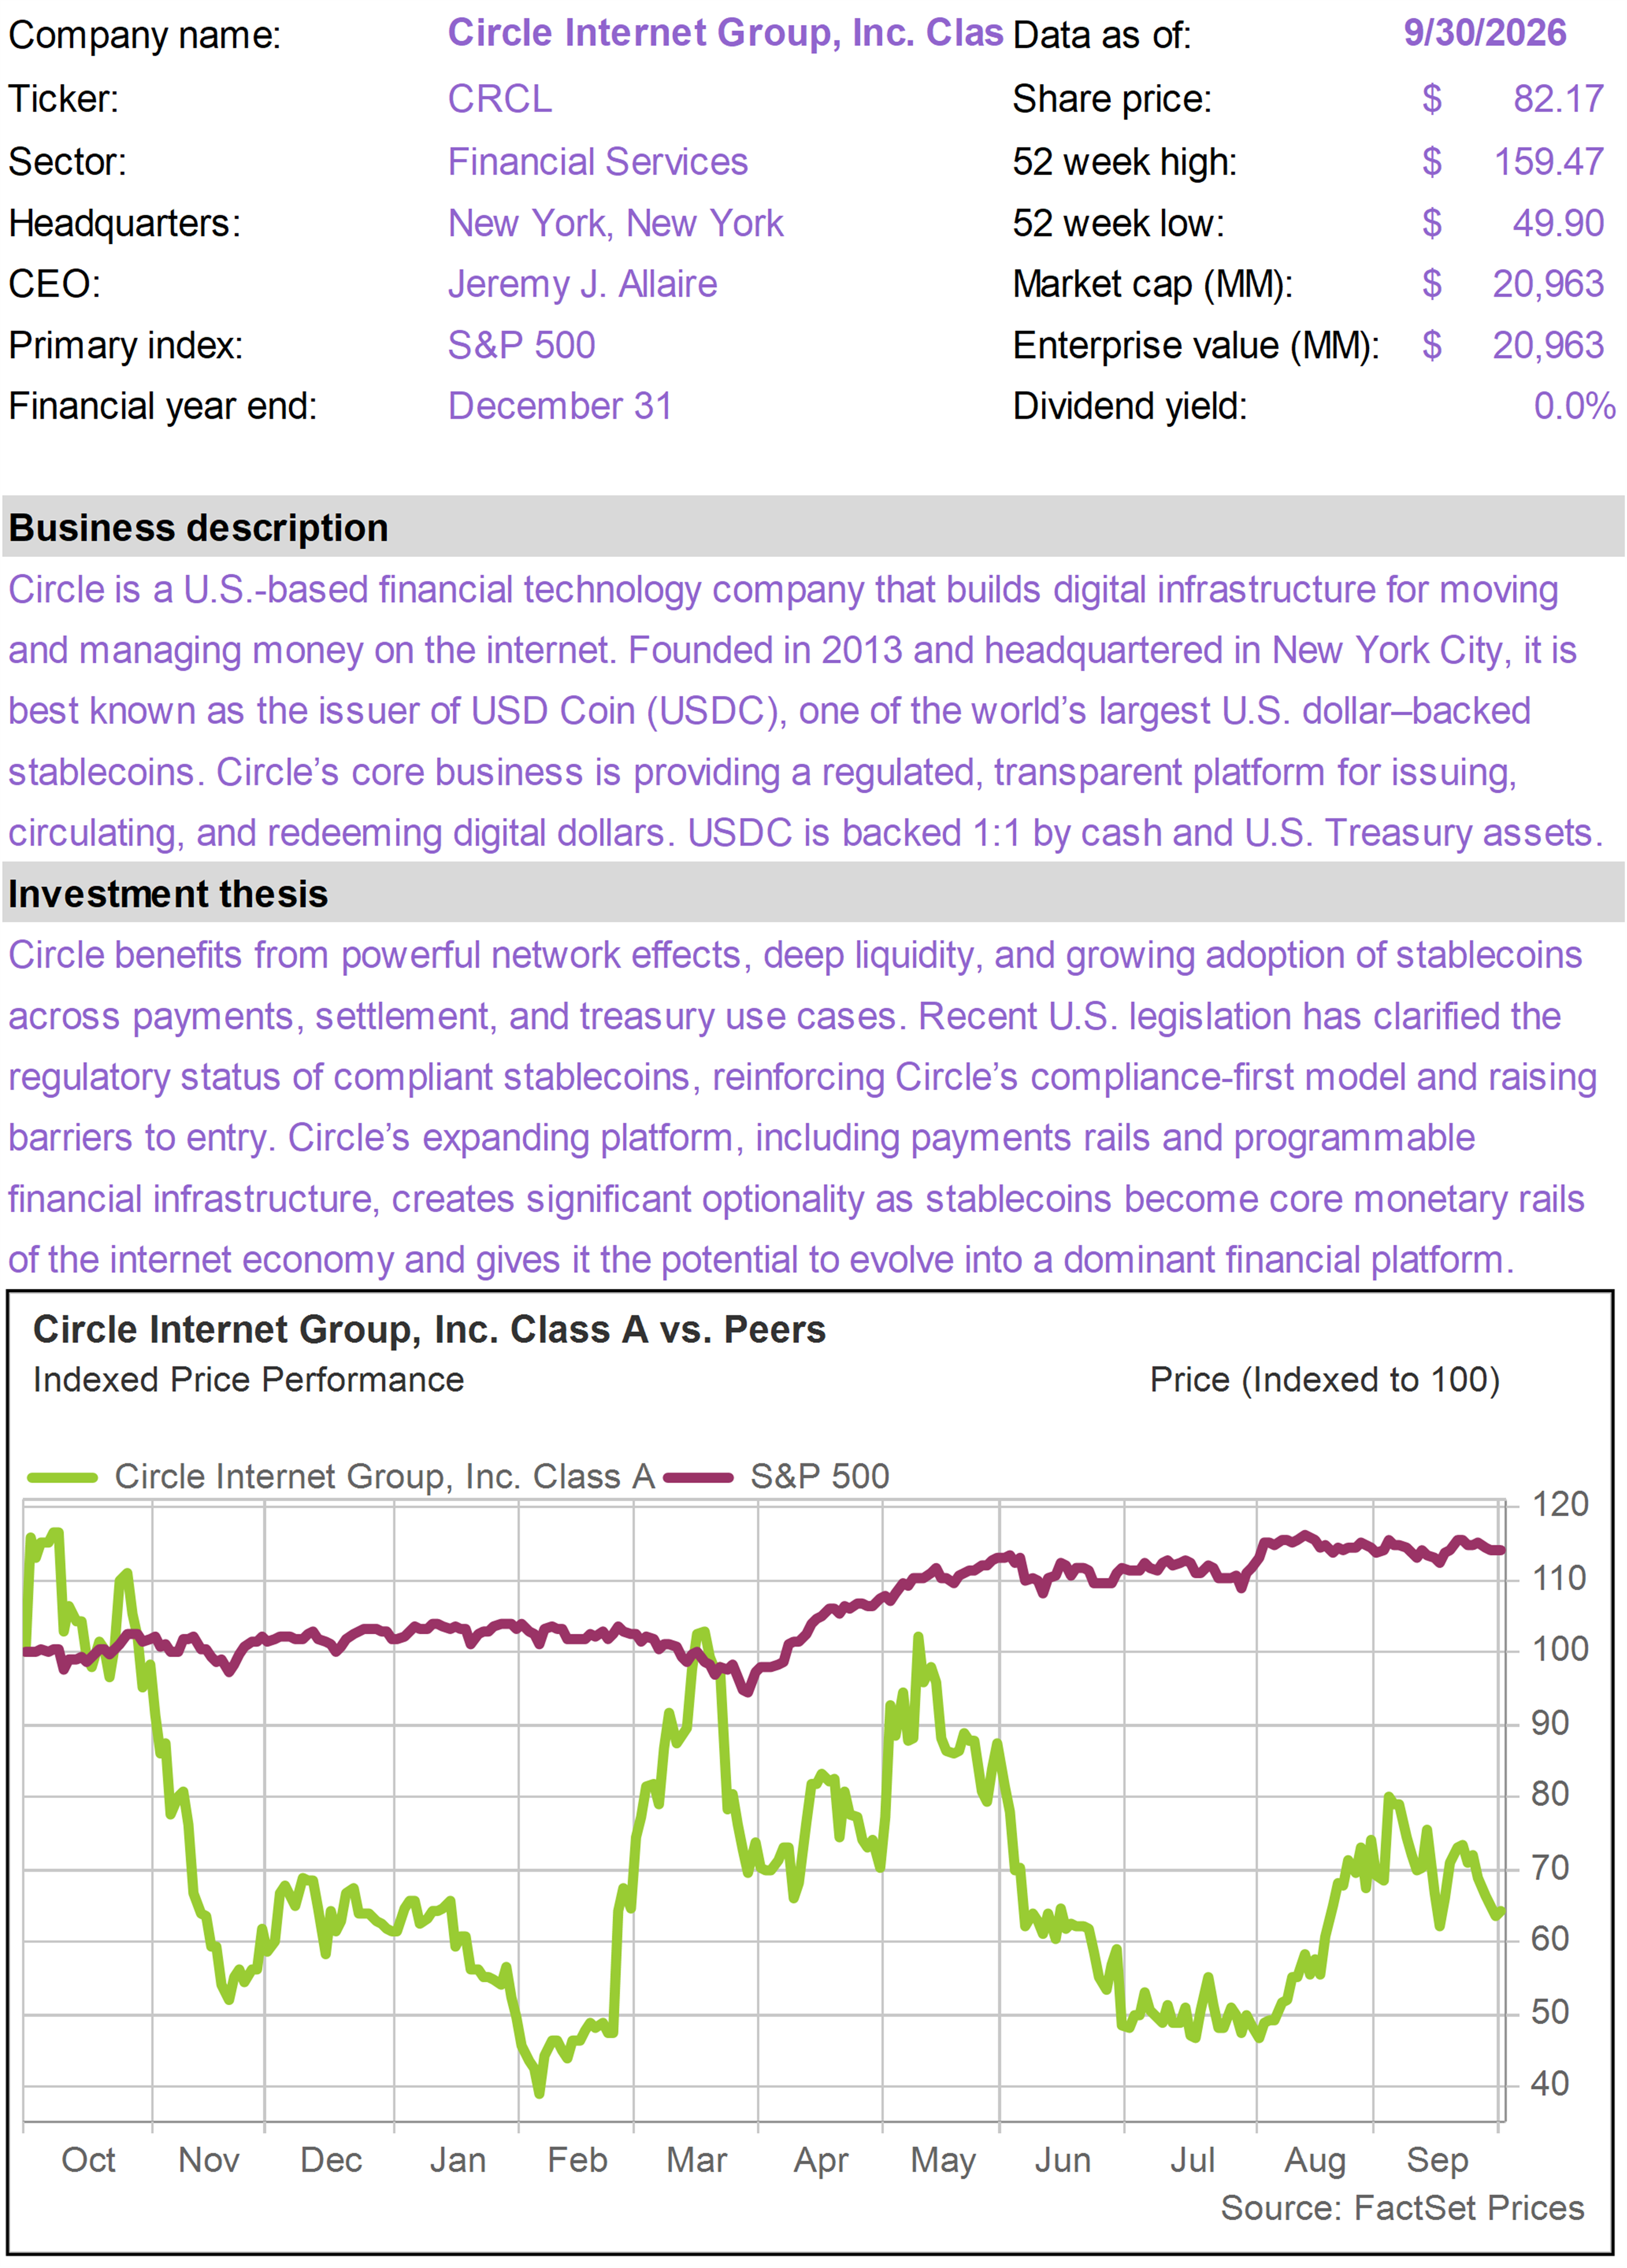
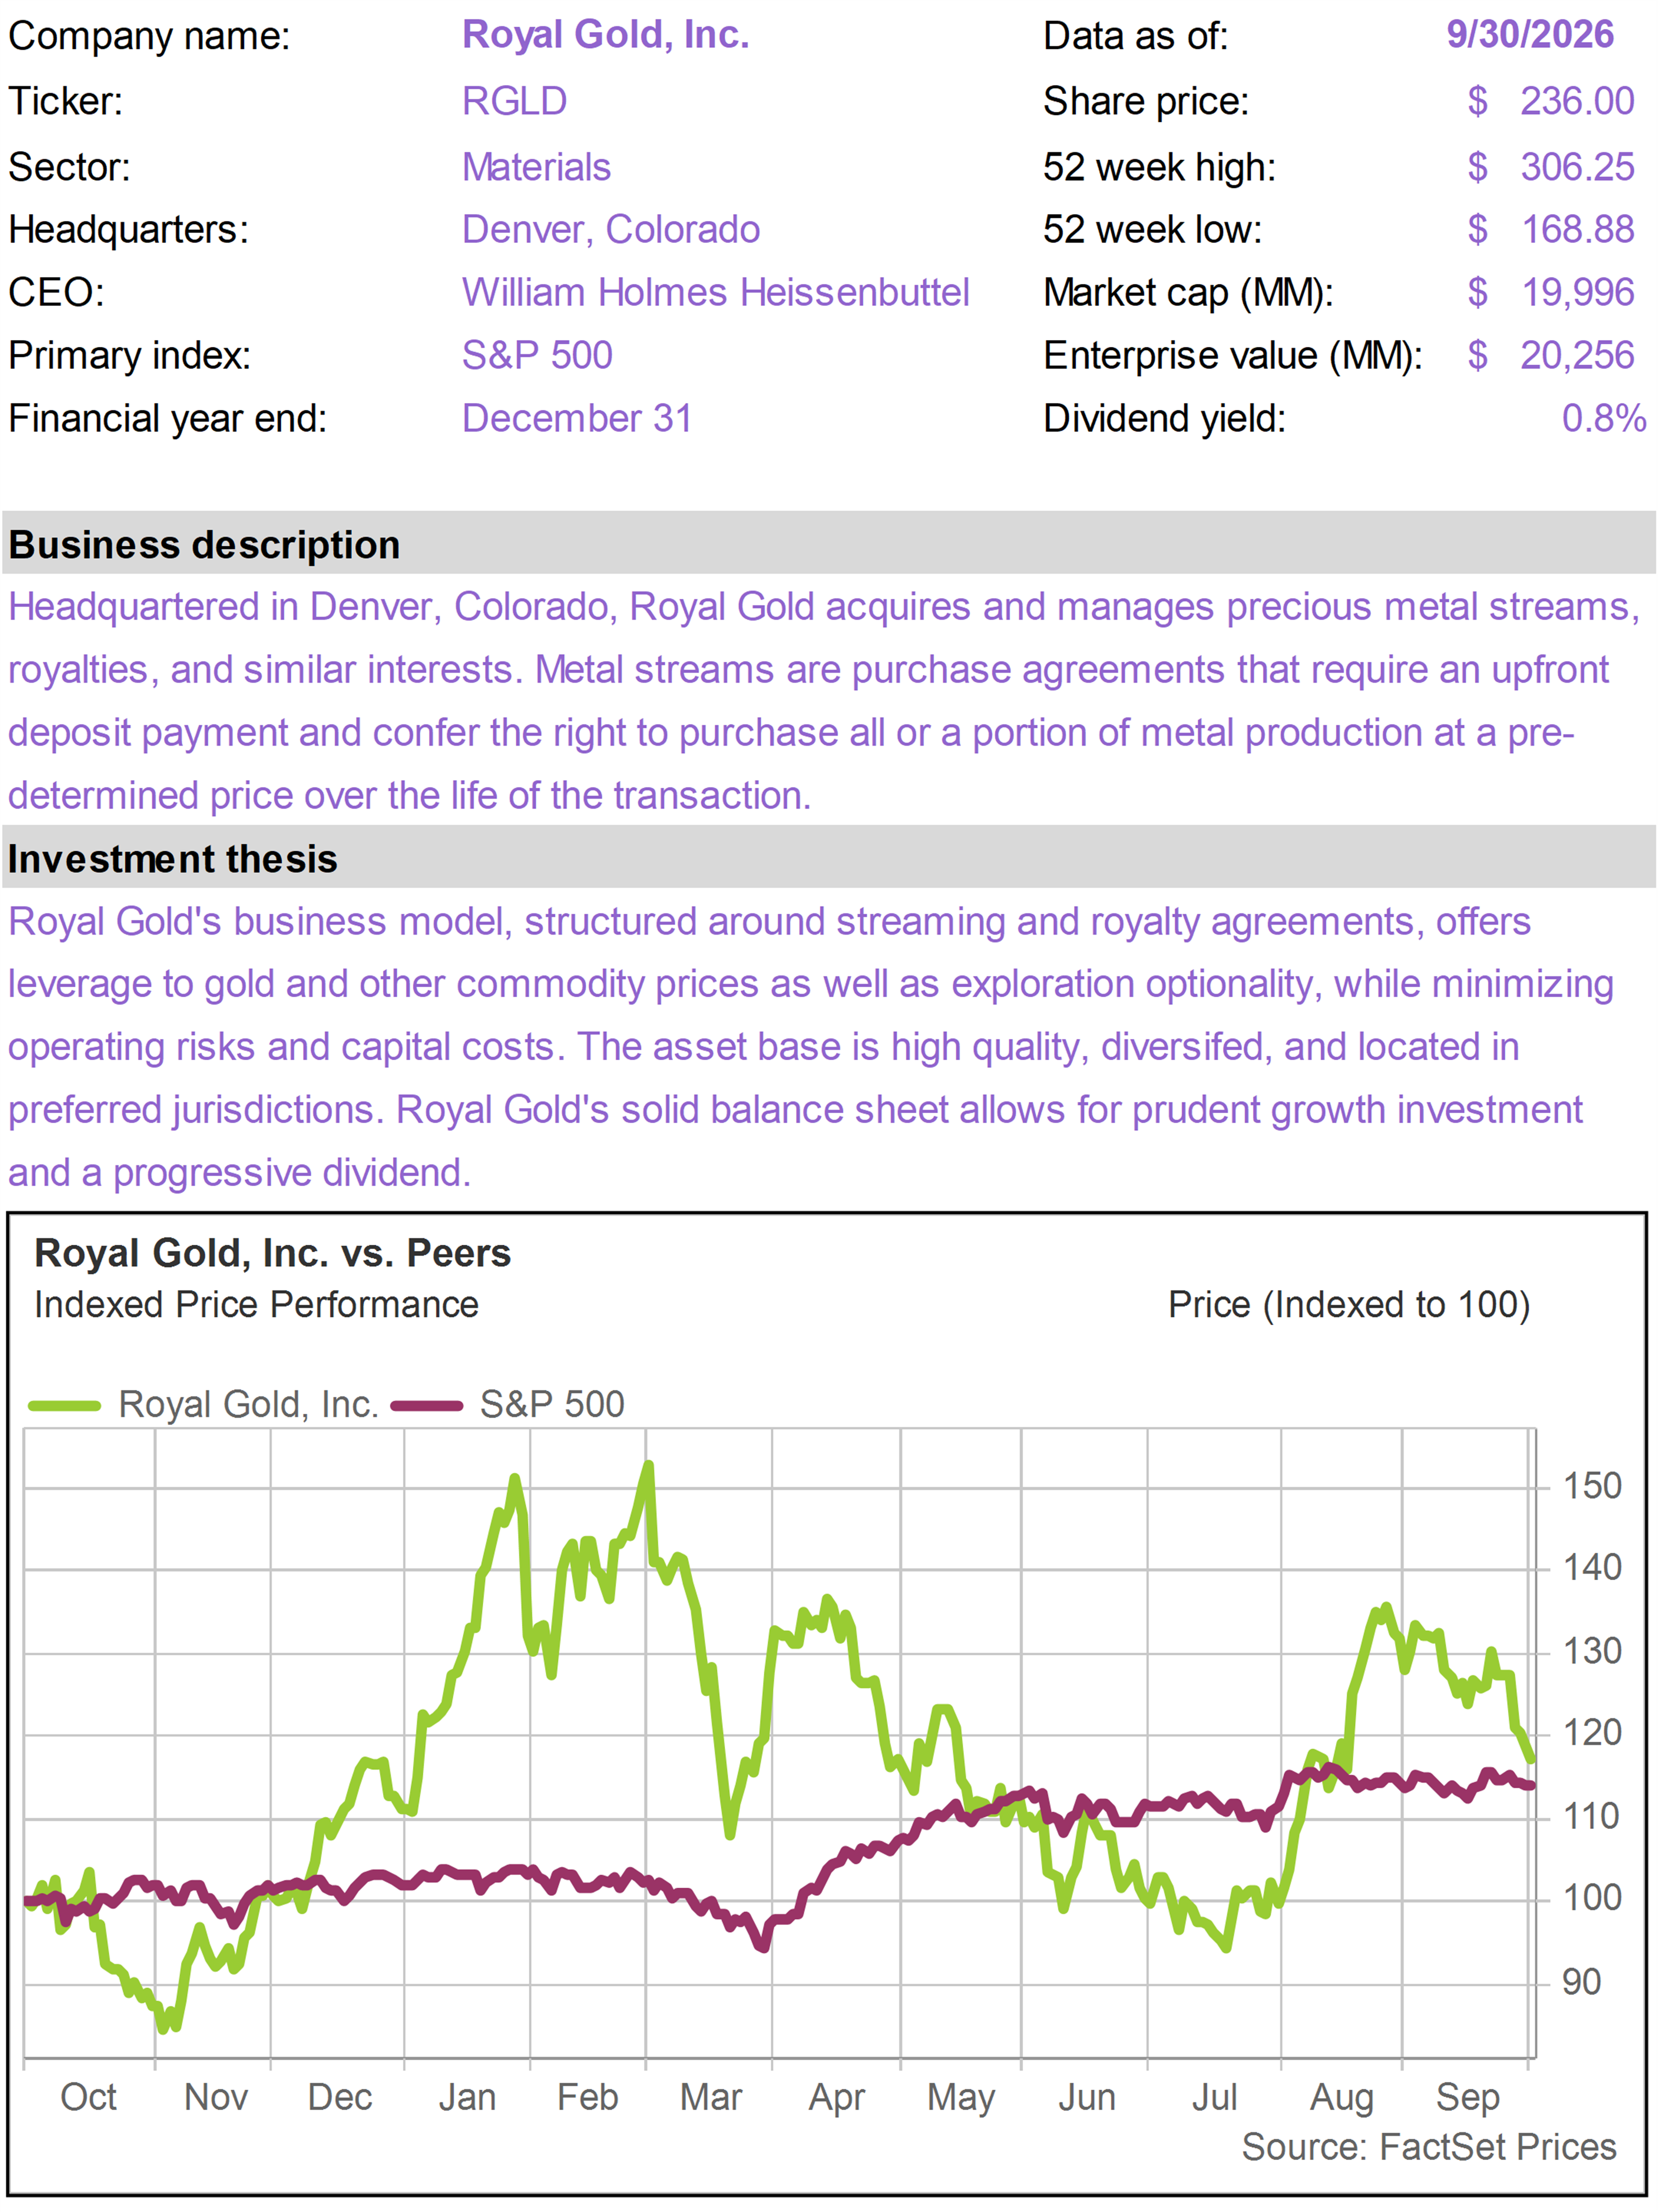
The largest portfolio detractors were Circle Internet Group (CRCL), which returned -14%; Wheaton Precious Metals (WPM), which returned -11%; and Royal Gold (RGLD), which returned -10%. |
|
|
A tale of two markets
September was an unusually divided month for financial markets.
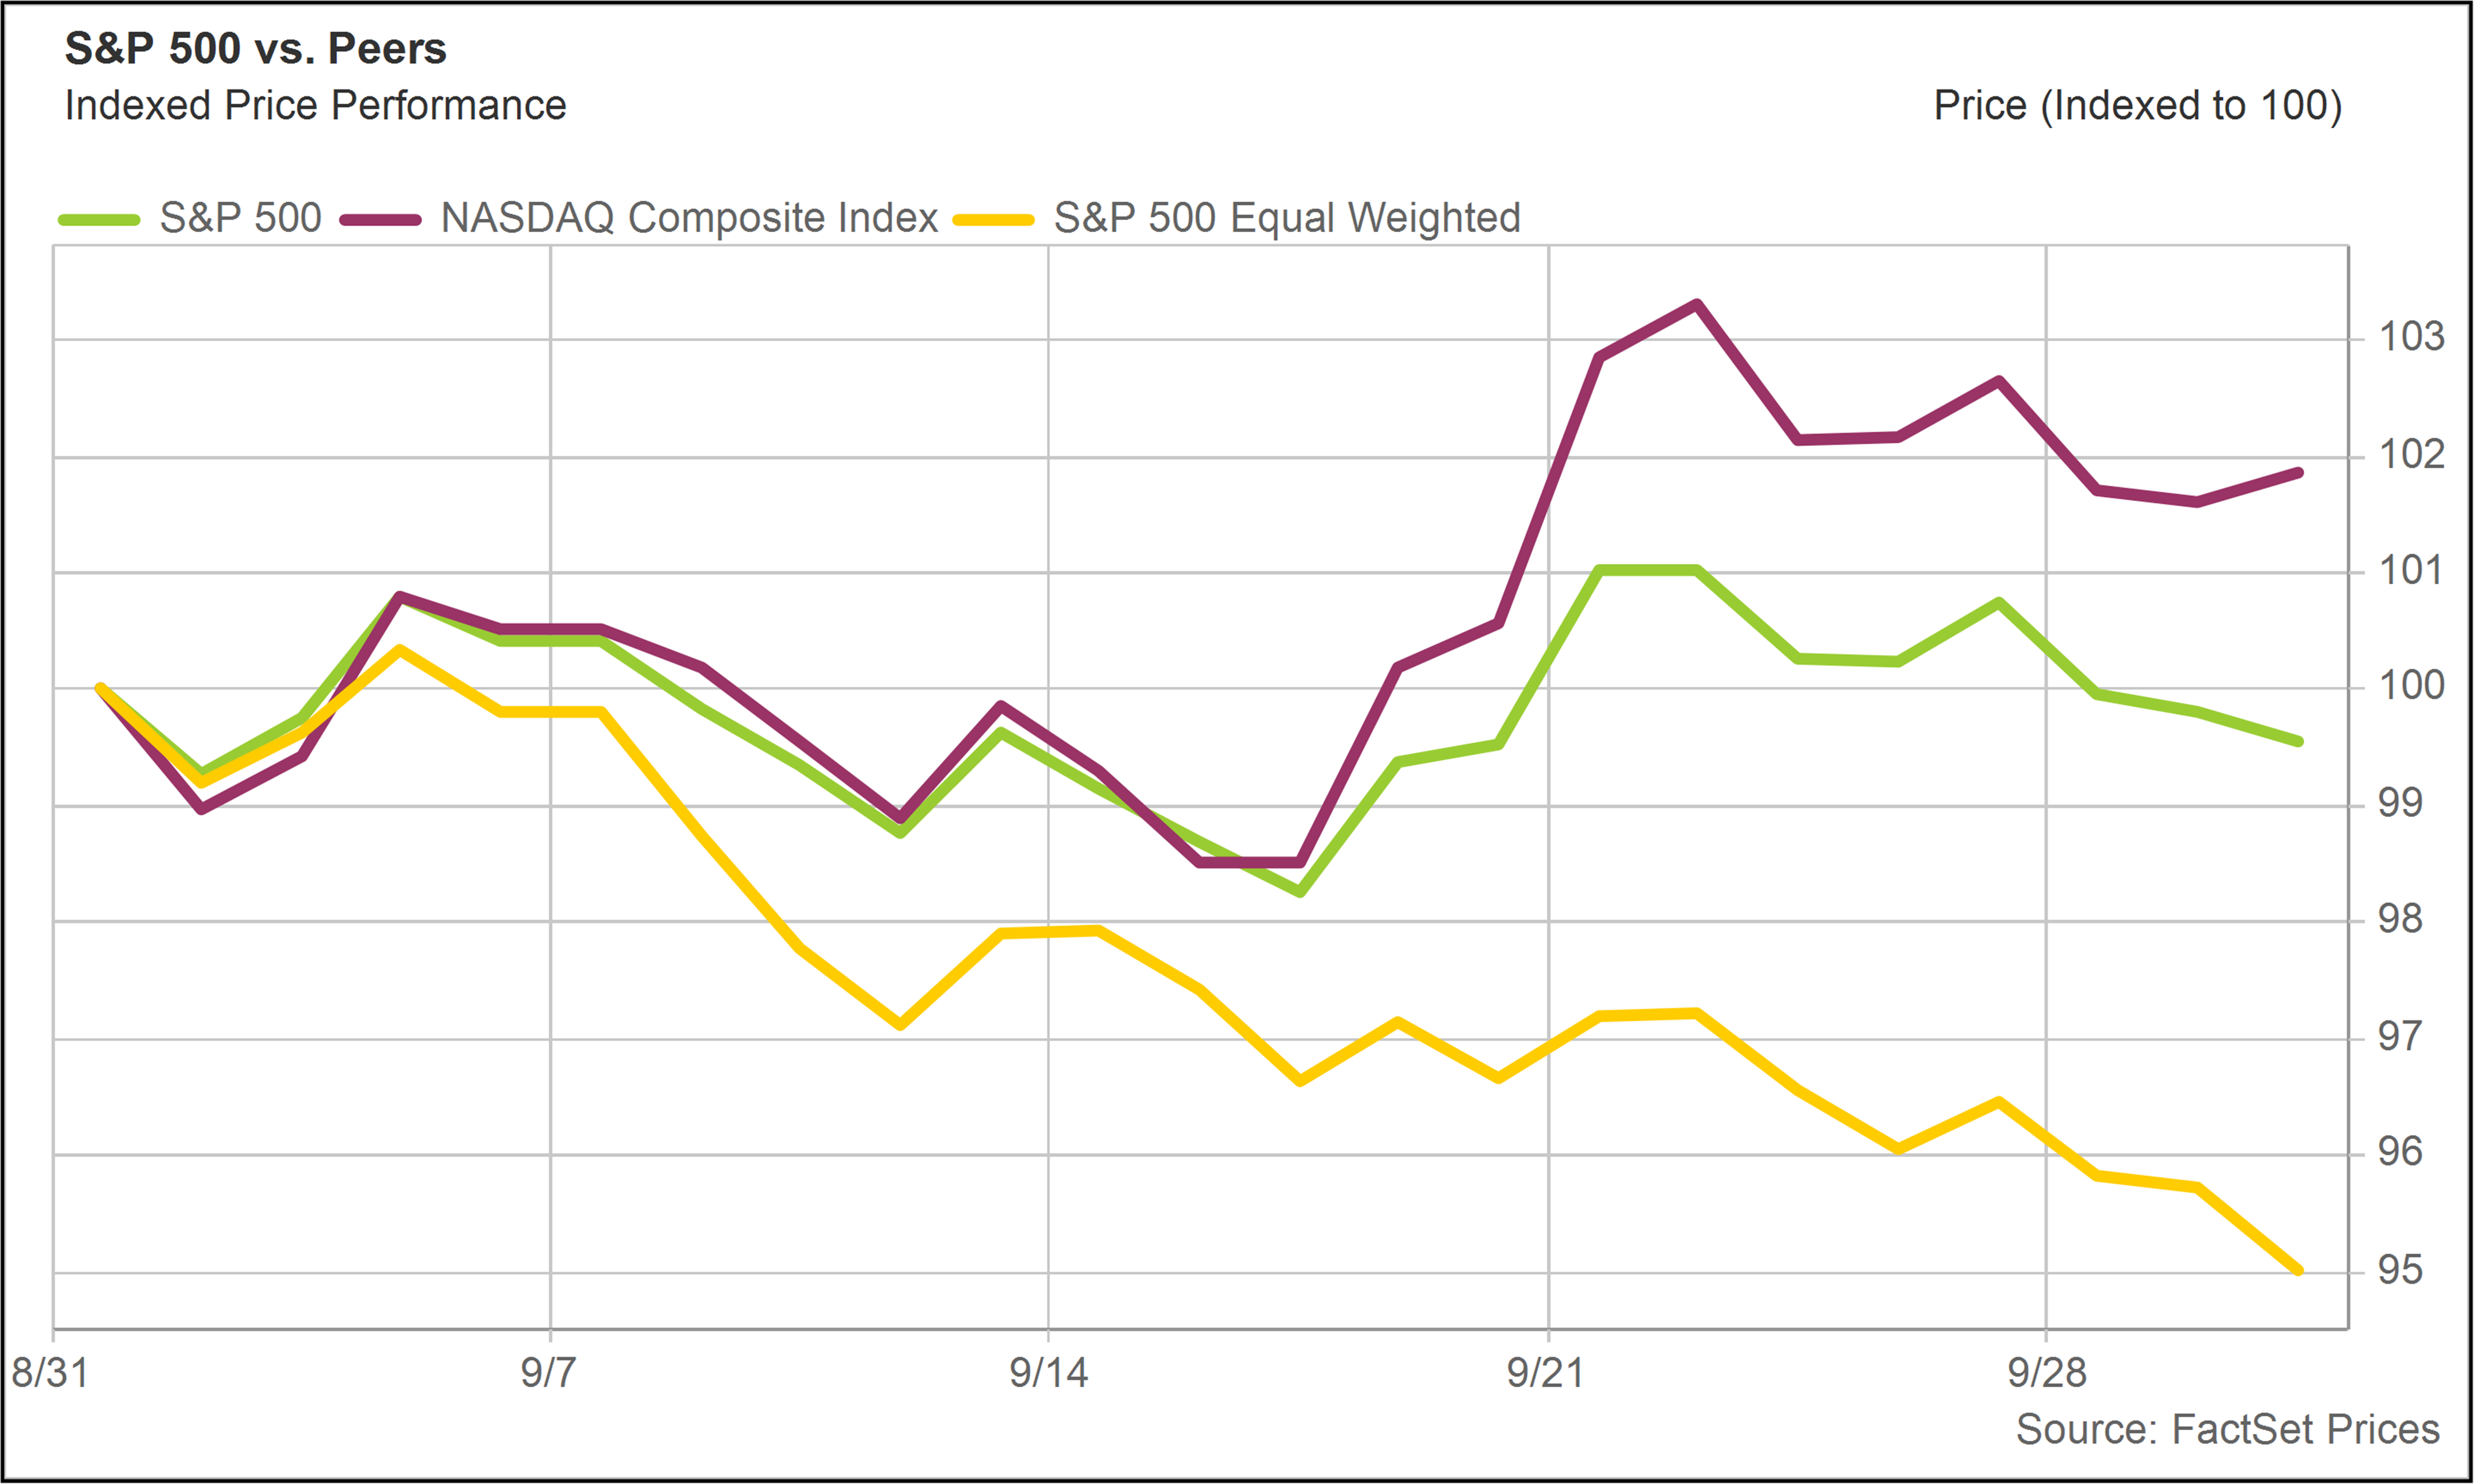
The S&P 500 finished slightly down, giving the appearance of relative stability. The Nasdaq Composite gained 1.9%, supported by continued strength among the largest AI-related stocks.
But those headline indexes concealed much greater weakness beneath the surface.
One of the clearest ways to see this is through the S&P 500 Equal Weight Index. Unlike the S&P 500, which assigns the largest weights to the most valuable companies, the equal-weight index gives the same importance to every constituent.
In that sense, it provides a much better indication of what was happening to the typical S&P 500 stock. In September, the S&P 500 Equal Weight Index generated a total return of -4.8%. |
|
|
|
S&P 500 vs. NASDAQ, S&P 500 Equal Weight(Total Return - September 2026) |
|
|
The deterioration in market breadth tells a similar story.
By the end of September, approximately 83% of S&P 500 constituents were more than 10% below their 52-week highs, while roughly 42% were down more than 20%—even though the capitalization-weighted index itself remained relatively close to its record.
Businesses perceived to be direct beneficiaries of the AI investment cycle continued to attract capital, whereas almost everything else struggled.
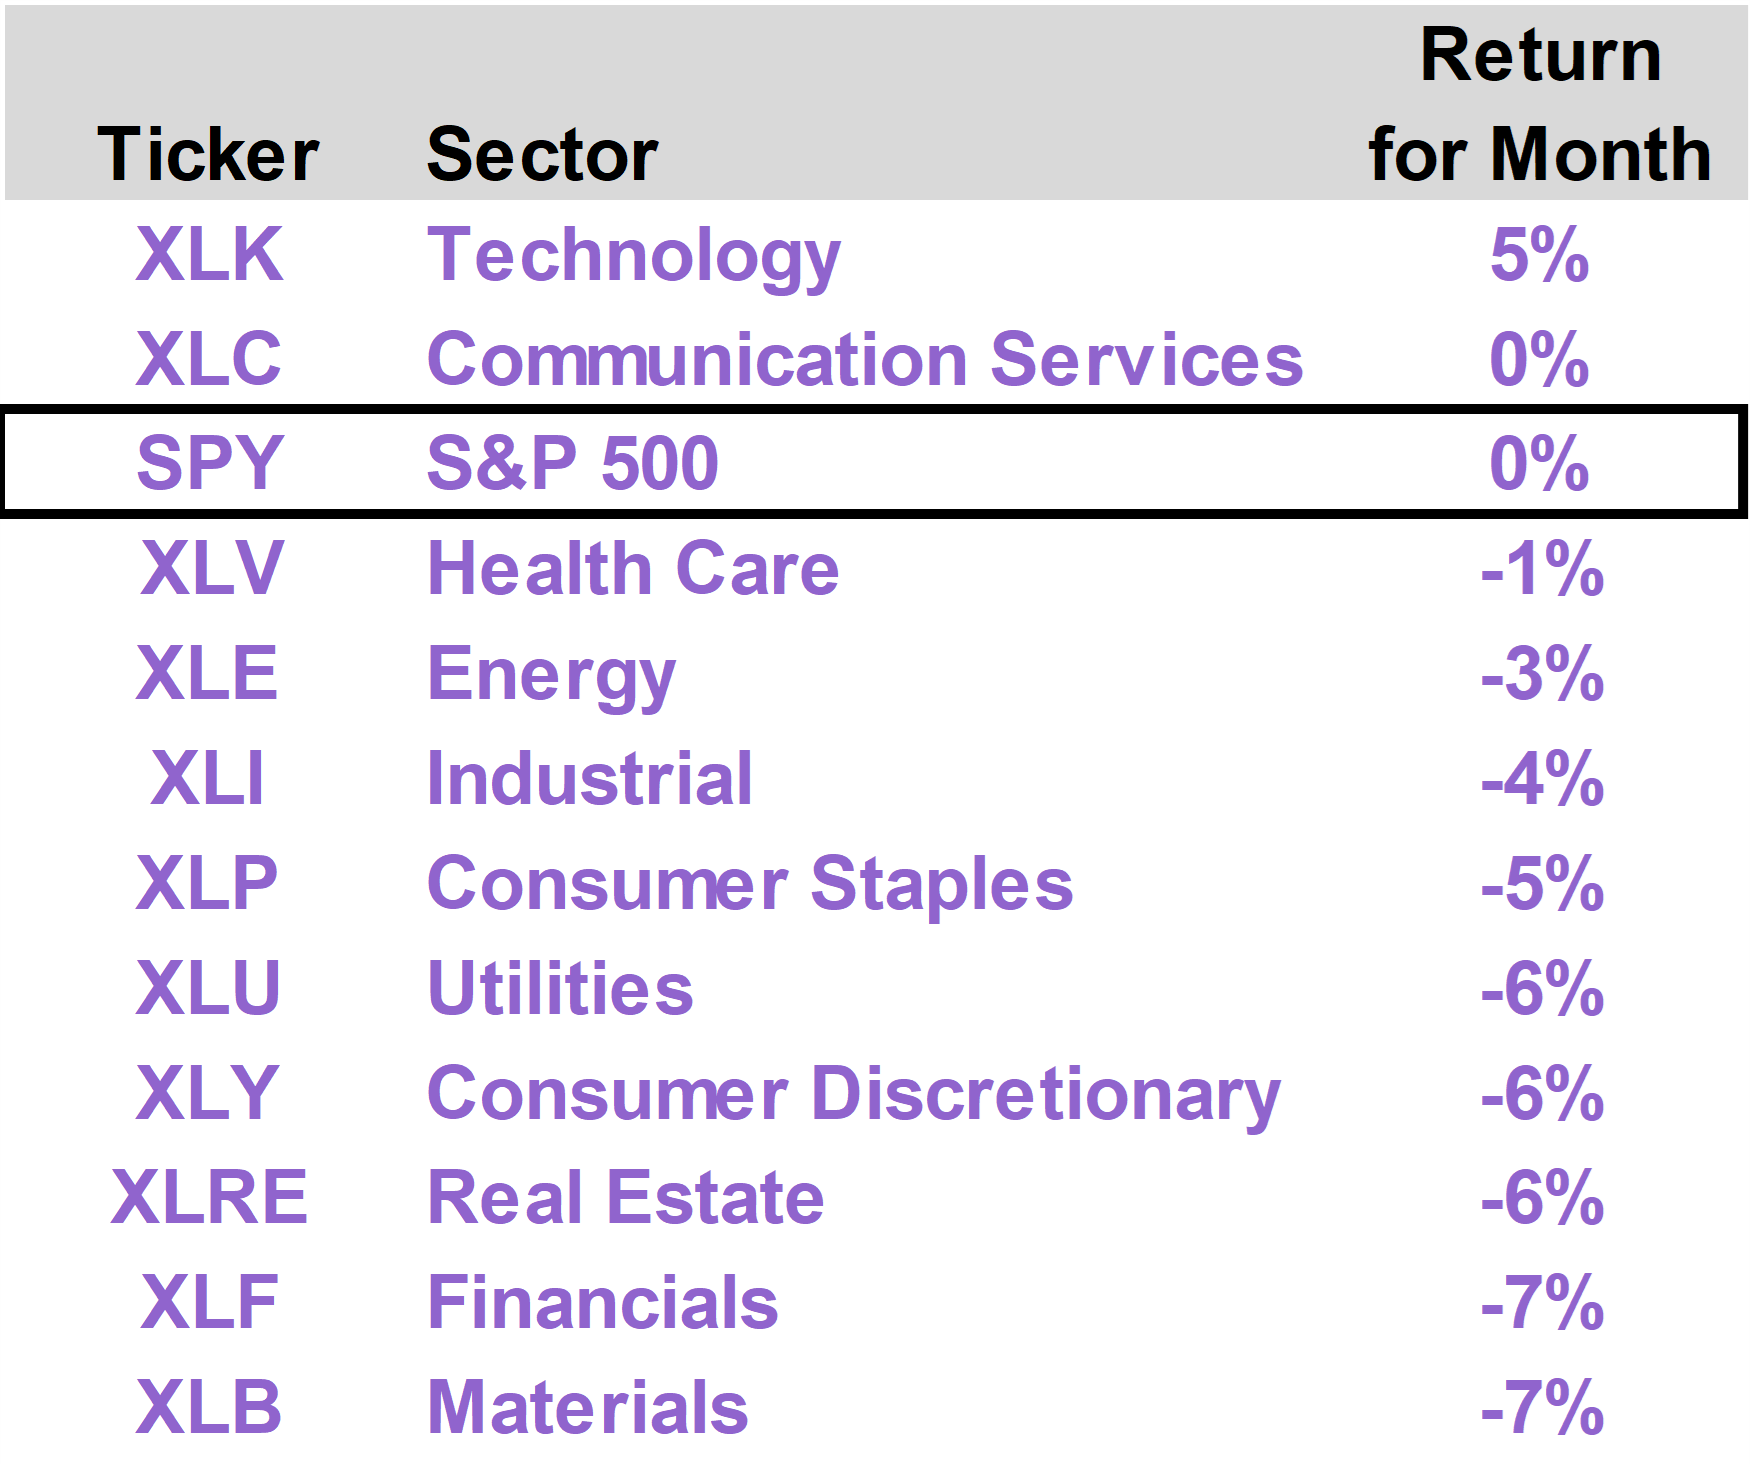
At the sector level, Technology stocks within the S&P 500 led the way and advanced 5%.
The Communication Services sector was marginally positive—but only because Meta Platforms (META), which gained 27% in September on enthusiasm around its launch of the Muse agentic AI service, has a weighting within that sector that exceeds 20%.
Excluding META, Communication Services would have delivered a negative result, along with the remaining nine other industry sectors. |
|
|
|
Bond yields spike
The main reason most stocks performed so poorly in September was the dramatic move higher in Treasury yields.
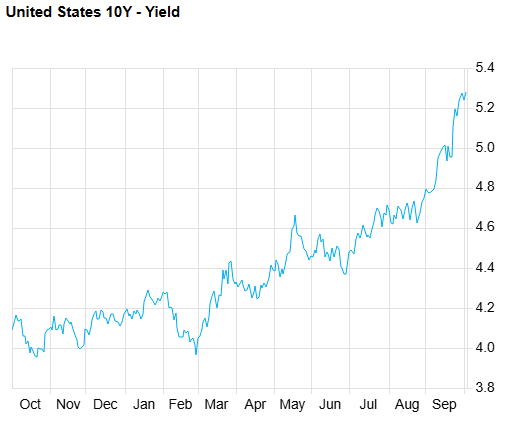
The 10-Year Treasury yield rose more than 50 basis points during September to approximately 5.3%, while the 30-Year Treasury yield climbed above 5.6%. |
|
|
|
10-Year Treasury Yields—Last 12 Months(Source: FactSet) |
|
|
Several factors have contributed to rising long-term bond yields this year. Economic growth has been resilient. Inflation has proven sticky. Oil prices have moved higher.
Meanwhile, the federal government continues to issue enormous quantities of debt, as the AI infrastructure boom simultaneously creates vast private sector demand for capital. In effect, the federal government and some of the world's largest corporations are competing for the same pool of long-term savings.
Some of the increase in rates therefore reflects relatively positive forces. As we discussed last month, higher real interest rates can accompany stronger expectations for long-term economic growth and productivity.
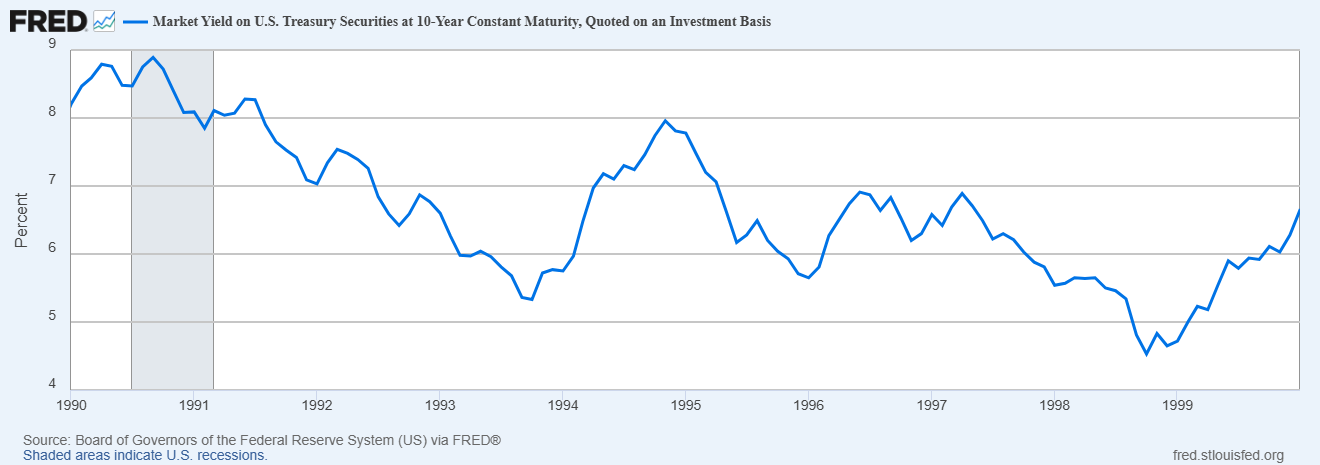
It is worth remembering that in the 1990s (a technology-driven growth era), yields on 10-Year Treasuries generally fluctuated between 5% and 8%. And the S&P 500 compounded at a remarkable 18.2% over the course of the decade. |
|
|
|
10-Year Treasury Yields in the 1990s |
|
|
While periods of real economic growth tend to be associated with higher real interest rates, the speed of September's move had significant consequences.
Higher discount rates reduce the present value investors assign to future corporate earnings. Financing becomes more expensive. Treasury securities become more competitive with stocks.
September's extraordinary market dispersion therefore makes more sense when viewed through the lens of interest rates.
Companies capable of producing explosive earnings growth could overcome the valuation pressure created by higher rates. Most other stocks could not.
The Fed adds to the pressure
While independent market forces have been pushing yields higher, the Federal Reserve significantly contributed to that dynamic in September.
At Kevin Warsh's first FOMC meeting as Chairman, the Fed unanimously raised the federal funds rate by 25 basis points to 3.75%-4.00%, its first increase in more than three years.
Warsh emphasized that inflation remained too high and that the economy remained strong enough to tolerate somewhat tighter monetary policy.
As we previously discussed in the 76report (The Rate Hike Trump Didn’t Want—But Why It Could Lead to Lower Rates Down the Road), there is a reasonable longer-term case for this approach. Establishing credibility on inflation today could ultimately give the Fed considerably more flexibility to reduce rates later.
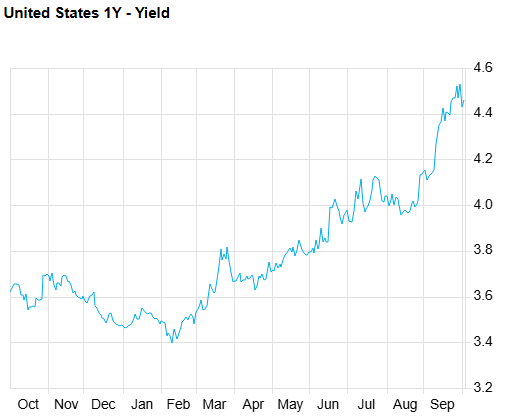
But as markets have priced in at least two incremental rate hikes in September, with 1-Year Treasury yields rising approximately a half-percent as well, the upward movement in rates has extended across the entire yield curve.
Long-term bond yields are rising in large part because they must compete with short-term bond yields. |
|
|
|
1-Year Treasury Yields—Last 12 Months(Source: FactSet) |
|
|
Oil complicates the picture
The other major macroeconomic complication remains oil.
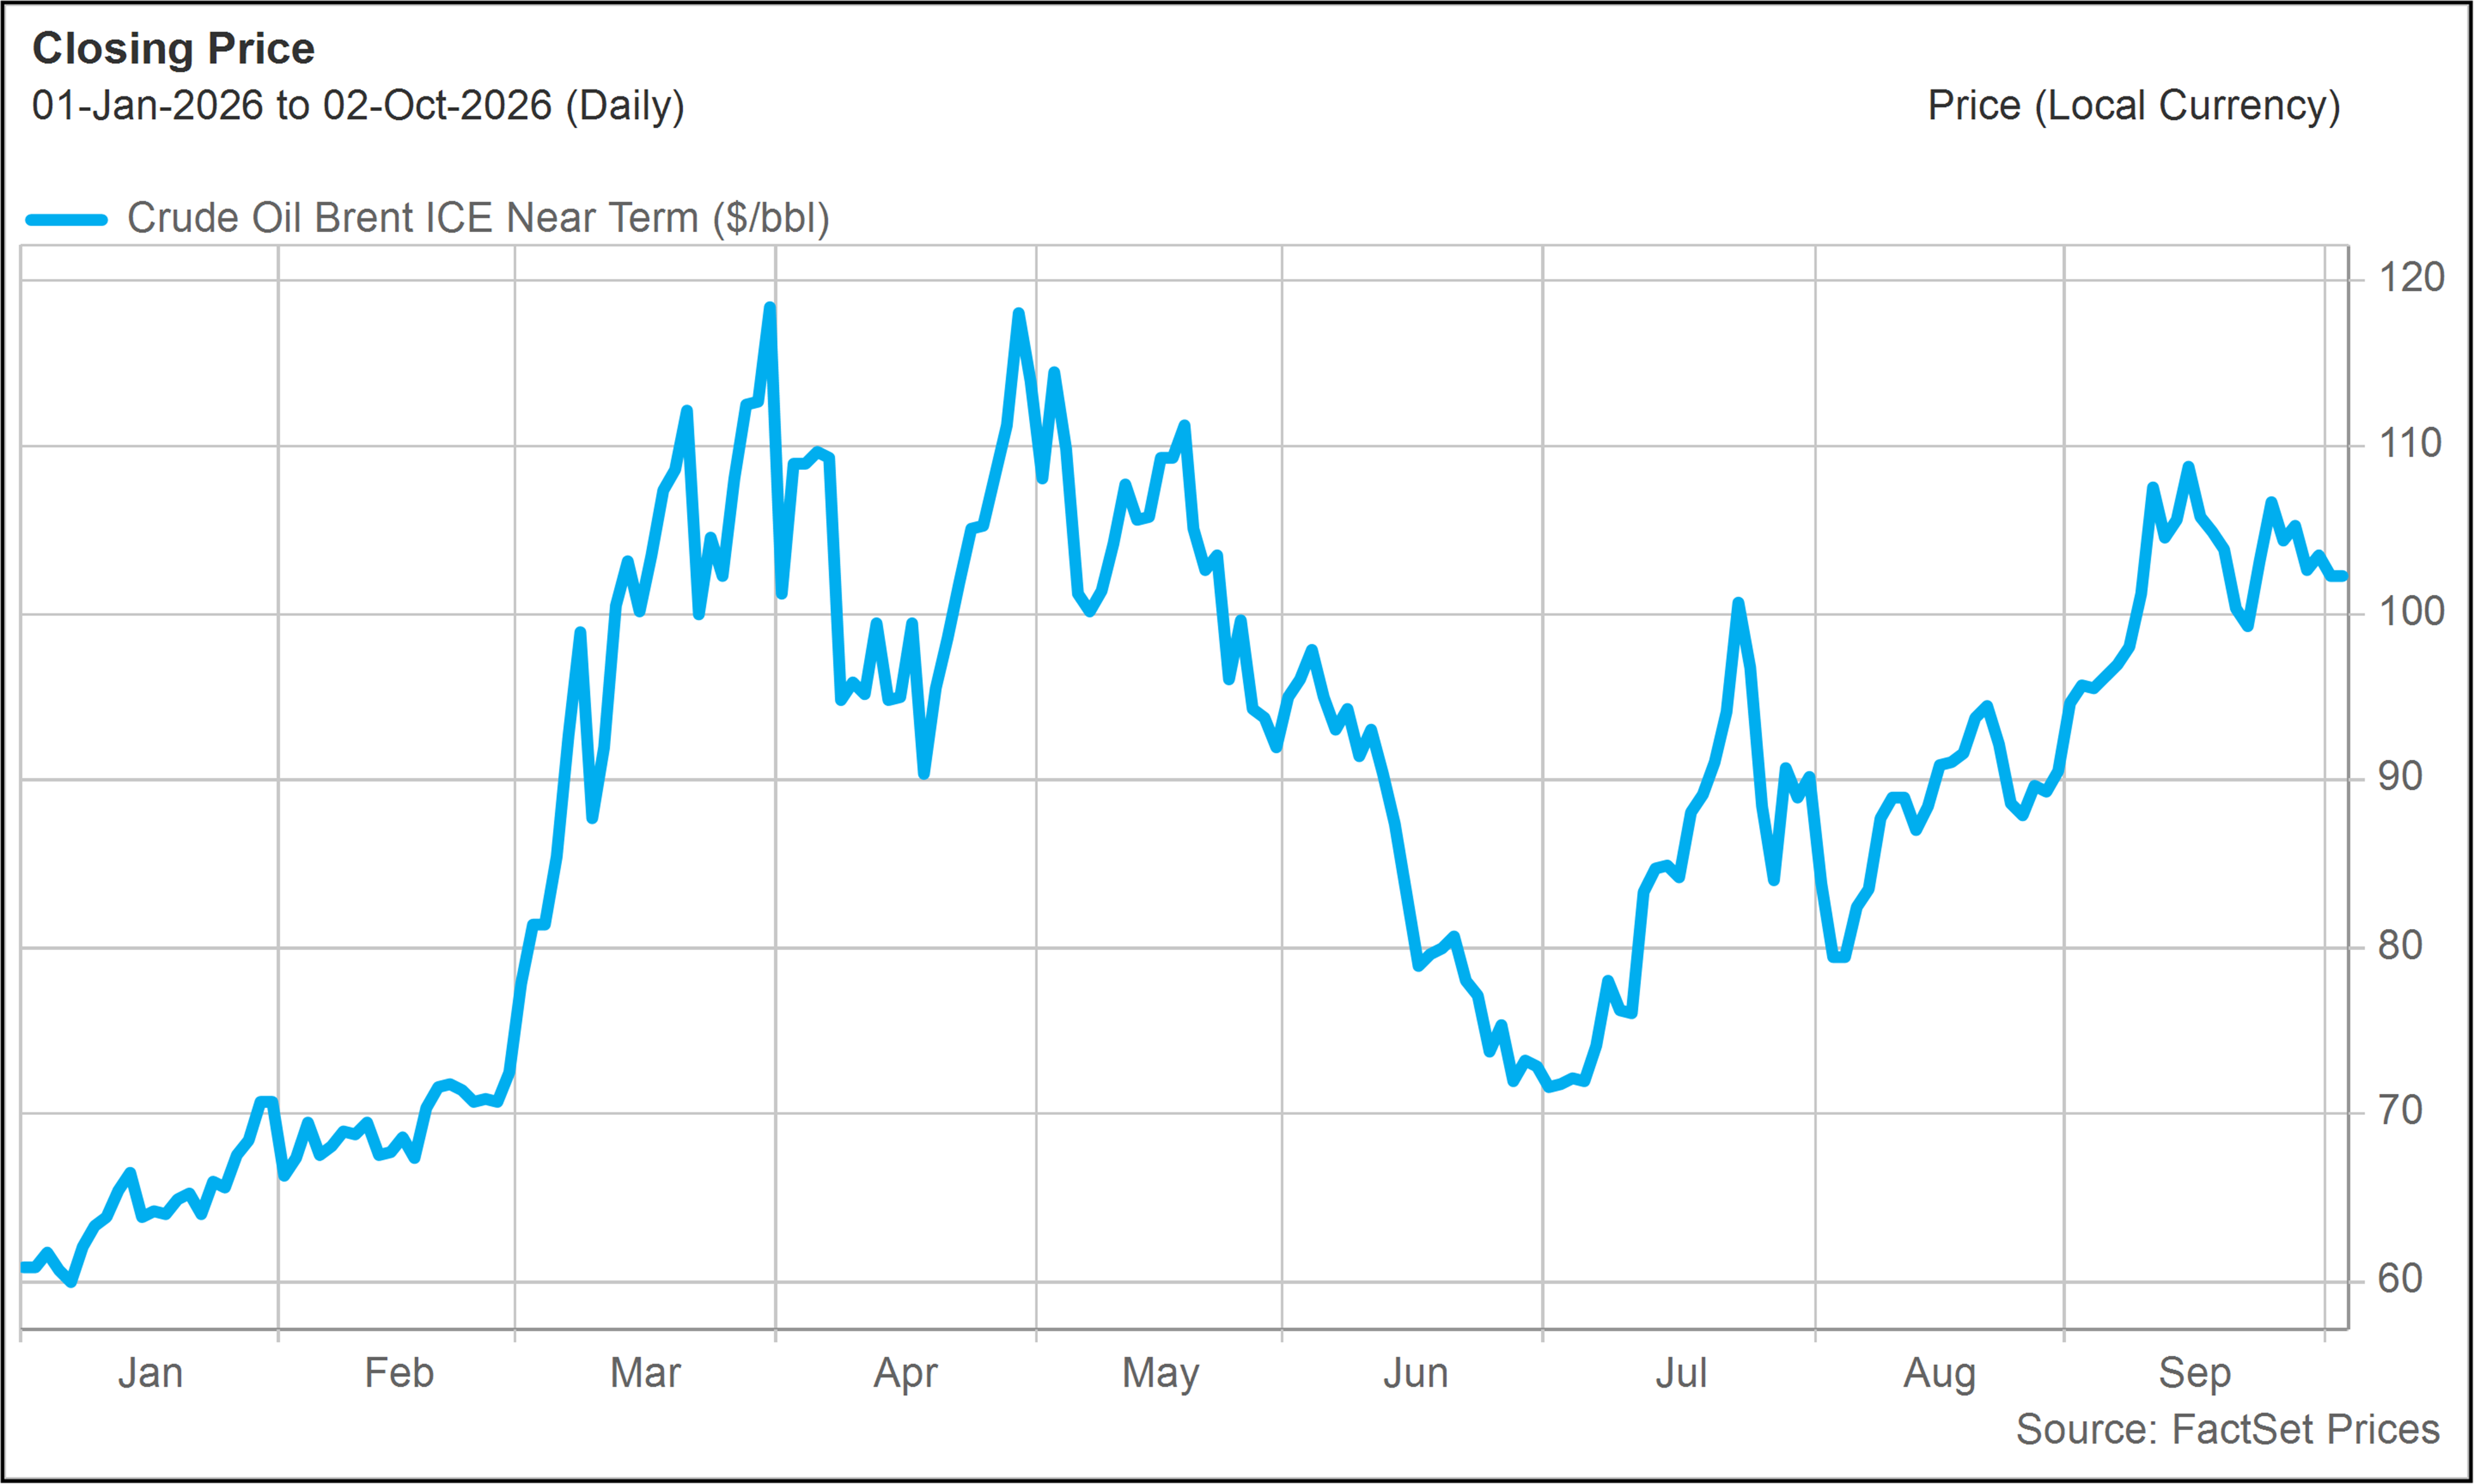
Energy prices moved higher again during September as the conflict with Iran continued to disrupt global petroleum flows and investors remained concerned about the reliability of shipments through the Strait of Hormuz. |
|
|
|
Crude Oil($/barrel - Last 12 Months) |
|
|
High oil prices make it more difficult for the Fed to declare victory over inflation and move toward easier monetary policy.
As we recently discussed (Iran Is Running Out of Financial Oxygen—Will Oil Prices Finally Break?), we are optimistic that oil prices could soon reverse, perhaps sharply. But the upward movement in oil made September particularly challenging: higher long-term rates, a Fed rate hike and rising energy prices all arrived at essentially the same time.
Gold takes a hit, as Bitcoin rallies
The surge in real interest rates also reversed part of the recent strength in precious metals.
Gold had rallied sharply in August as investors once again embraced the so-called debasement trade, but the environment became considerably less favorable in September.
Gold does not generate income. As government bond yields rise, the opportunity cost of holding it increases. A stronger dollar creates an additional headwind.
Gold consequently came under meaningful pressure during September, declining more than 6%, as real yields moved sharply higher and expectations for tighter Fed policy going forward increased.
While Bitcoin is often linked to gold as part of the debasement trade, it fared much better in September, advancing approximately 7%.
That strength largely reflects crypto-specific fundamentals, including continued institutional adoption and further regulatory progress despite the failure of the CLARITY Act to advance in the Senate.
The broader direction in Washington still appears to favor deeper integration of crypto into the traditional financial system, with growing momentum around tokenization and the link between crypto and agentic AI. This helped offset the macroeconomic headwinds that weighed on gold.
Has the rate move gone too far?
It is possible investors have become too carried away with the “higher for longer” narrative. The first meaningful evidence supporting that possibility arrived immediately after September ended.
The September employment report showed that the economy added only 29,000 jobs, well below expectations. The unemployment rate increased to 4.2%, wage growth moderated and previous months' employment gains were revised lower.
The report does not suggest the economy is falling into recession. Layoffs remain limited, and the labor market still resembles a relatively stable low-hire, low-fire environment.
But the softness in hiring reduces the urgency for additional Fed tightening, and both the stock and bond market responded positively to the weak jobs report.
If employment growth continues to moderate, inflation gradually recedes and the disruptions in oil markets eventually ease, investors may discover that September represented something close to a high-water mark for interest rate anxiety.
That could have important consequences for the areas of the market that suffered most.
A stabilization—or even modest decline—in long-term rates would relieve pressure on small-cap stocks, real estate, utilities, industrial companies, dividend-paying equities and many other businesses that have recently been overshadowed by the AI trade.
A difficult month—but potentially a healthier setup
September delivered an unusual combination.
The largest AI beneficiaries continued to perform well on underlying fundamental strength. On the other hand, long-term interest rates surged, the Fed tightened, oil remained expensive, and gold reversed.
Those pressures are now reflected much more aggressively in market prices.
Meanwhile, the underlying economy remains healthy. Corporate earnings remain solid. AI-related capital investment continues at an extraordinary pace. And the latest labor market data suggest the forces pushing rates relentlessly higher may finally be encountering some resistance.
If long-term yields begin to stabilize or retreat, the next phase of the market could look very different from September—and considerably more favorable for the broad range of high-quality businesses that were left behind during the month's unusually narrow AI-driven rally. |
|
| | |
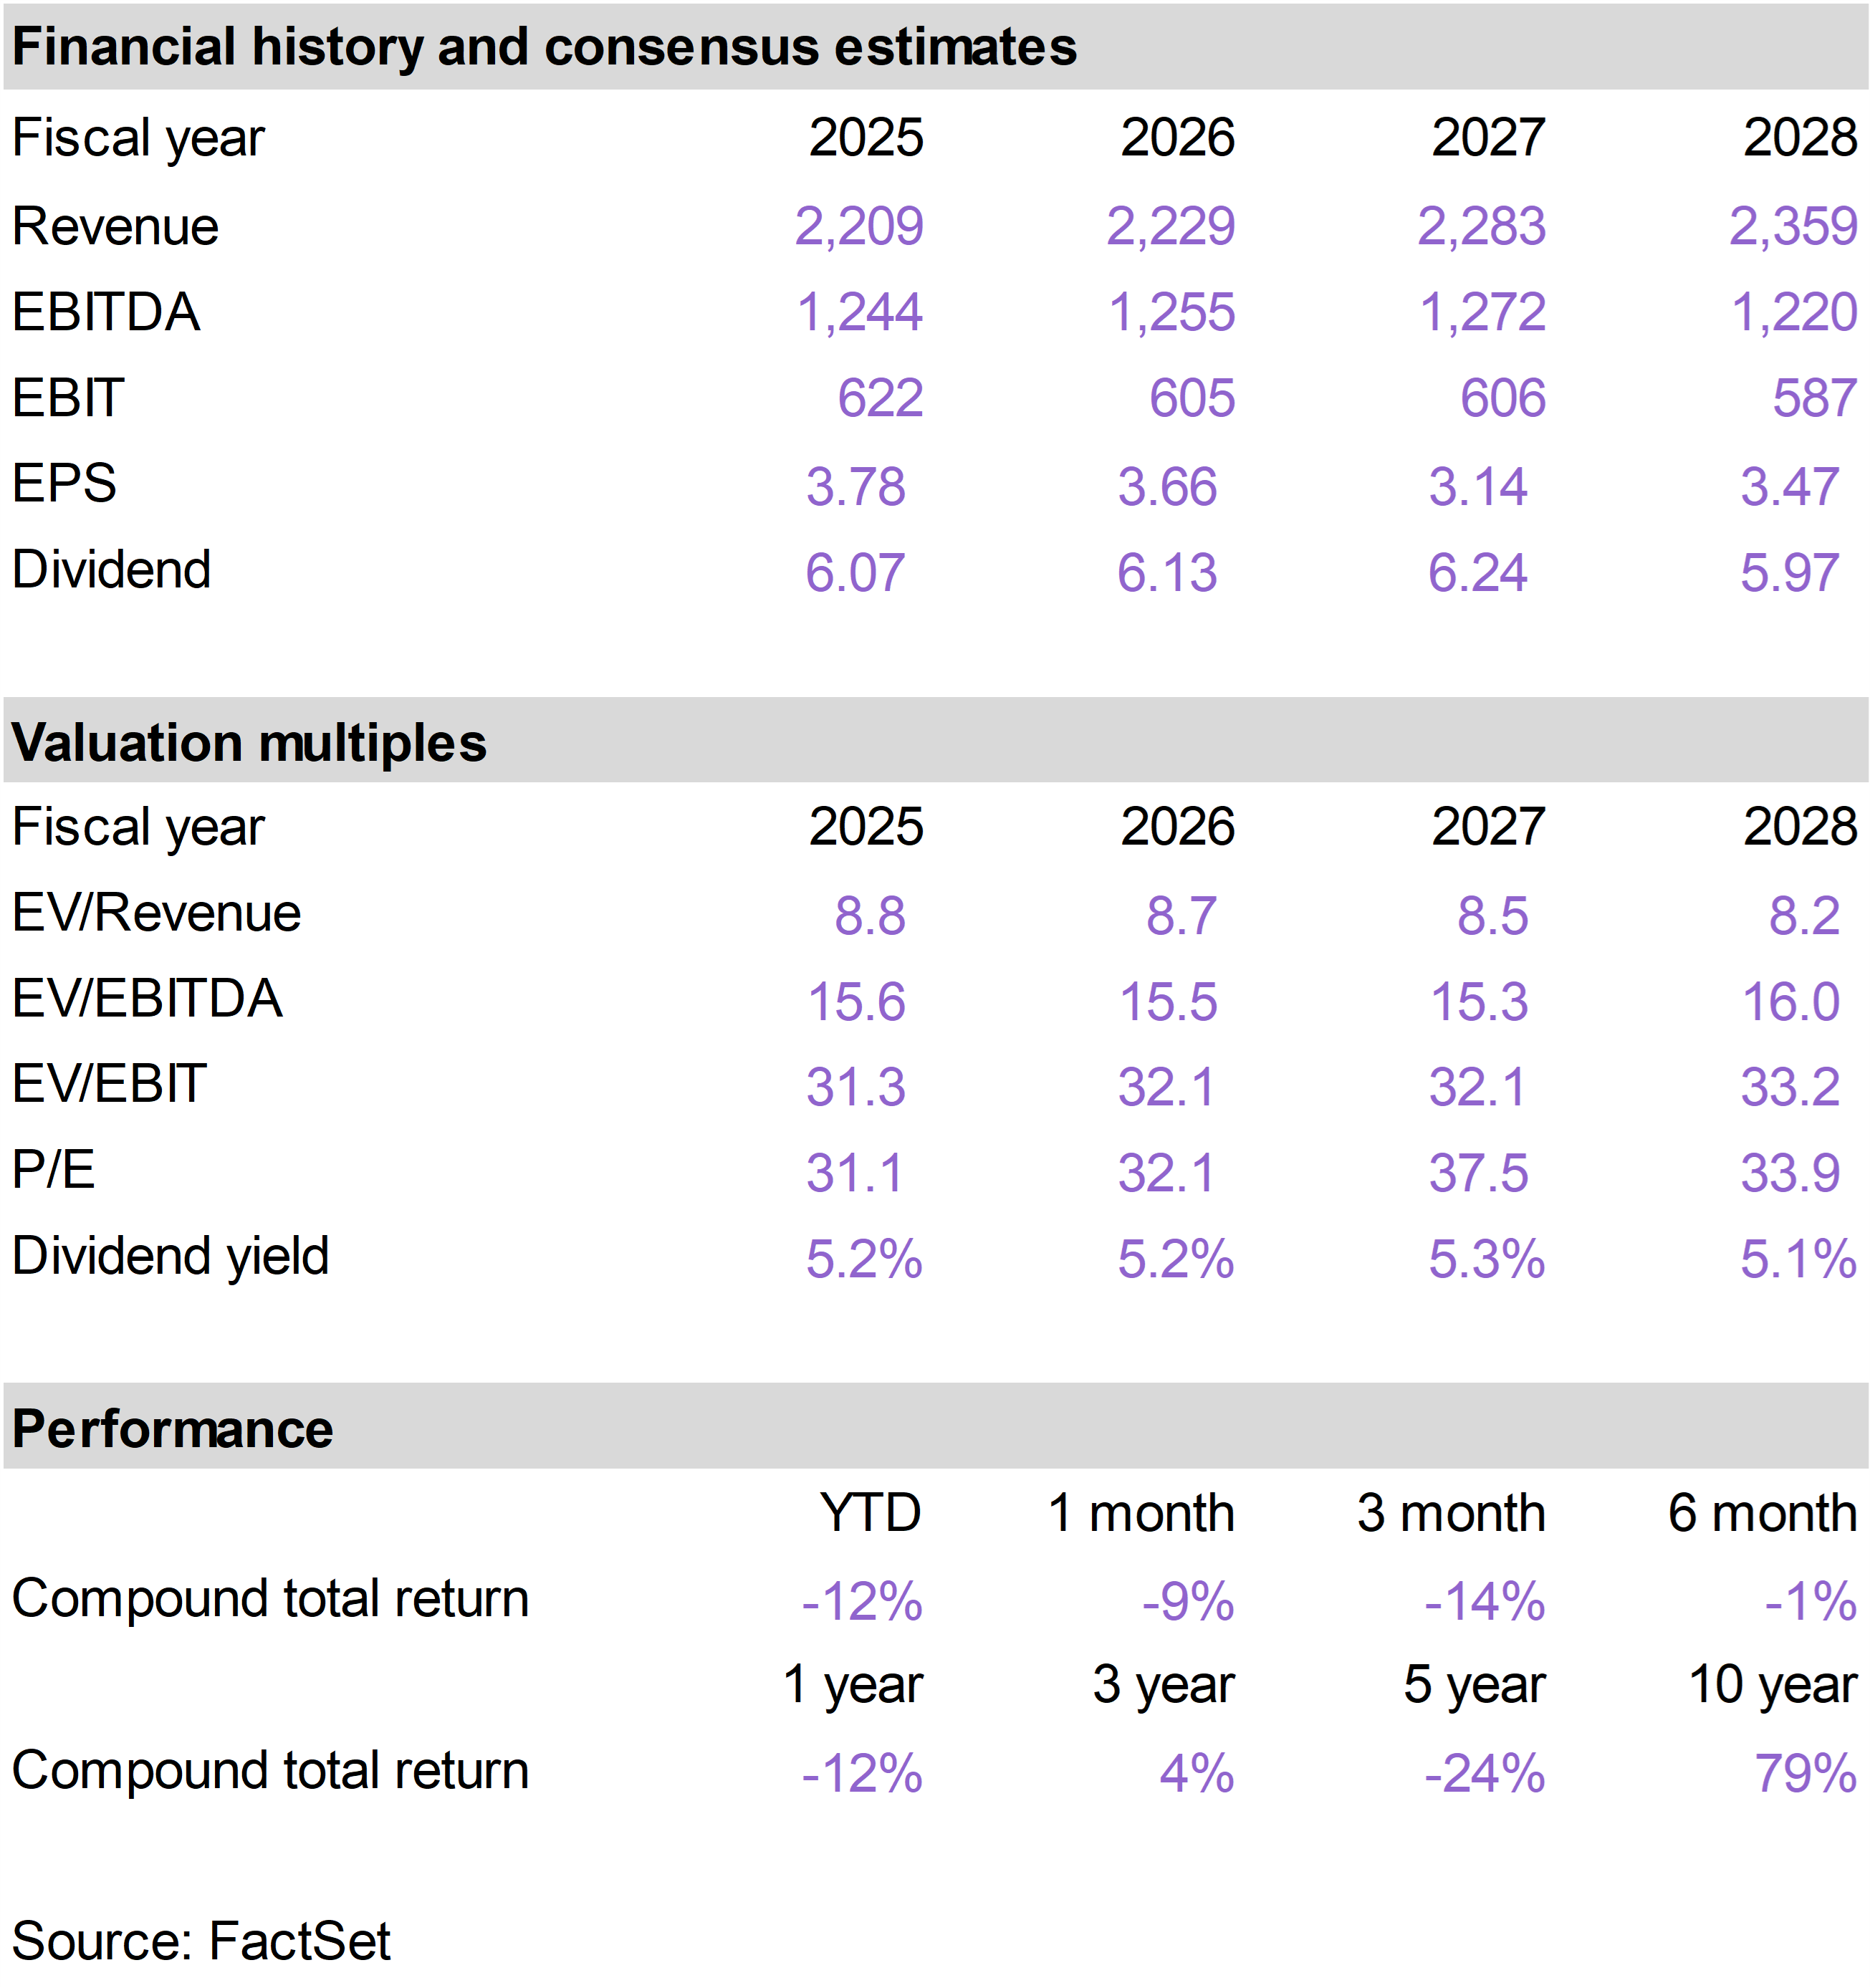
The top performing stocks in the Inflation Protection portfolio this month were WESCO International (WCC), which returned 6%; Costco (COST), which returned -4%; and Visa (V), which returned -5%.
The worst performing stocks in the portfolio in September were Circle Internet Group (CRCL), which returned -14%; Wheaton Precious Metals (WPM), which returned -11%; and Royal Gold (RGLD), which returned -10%. |
|
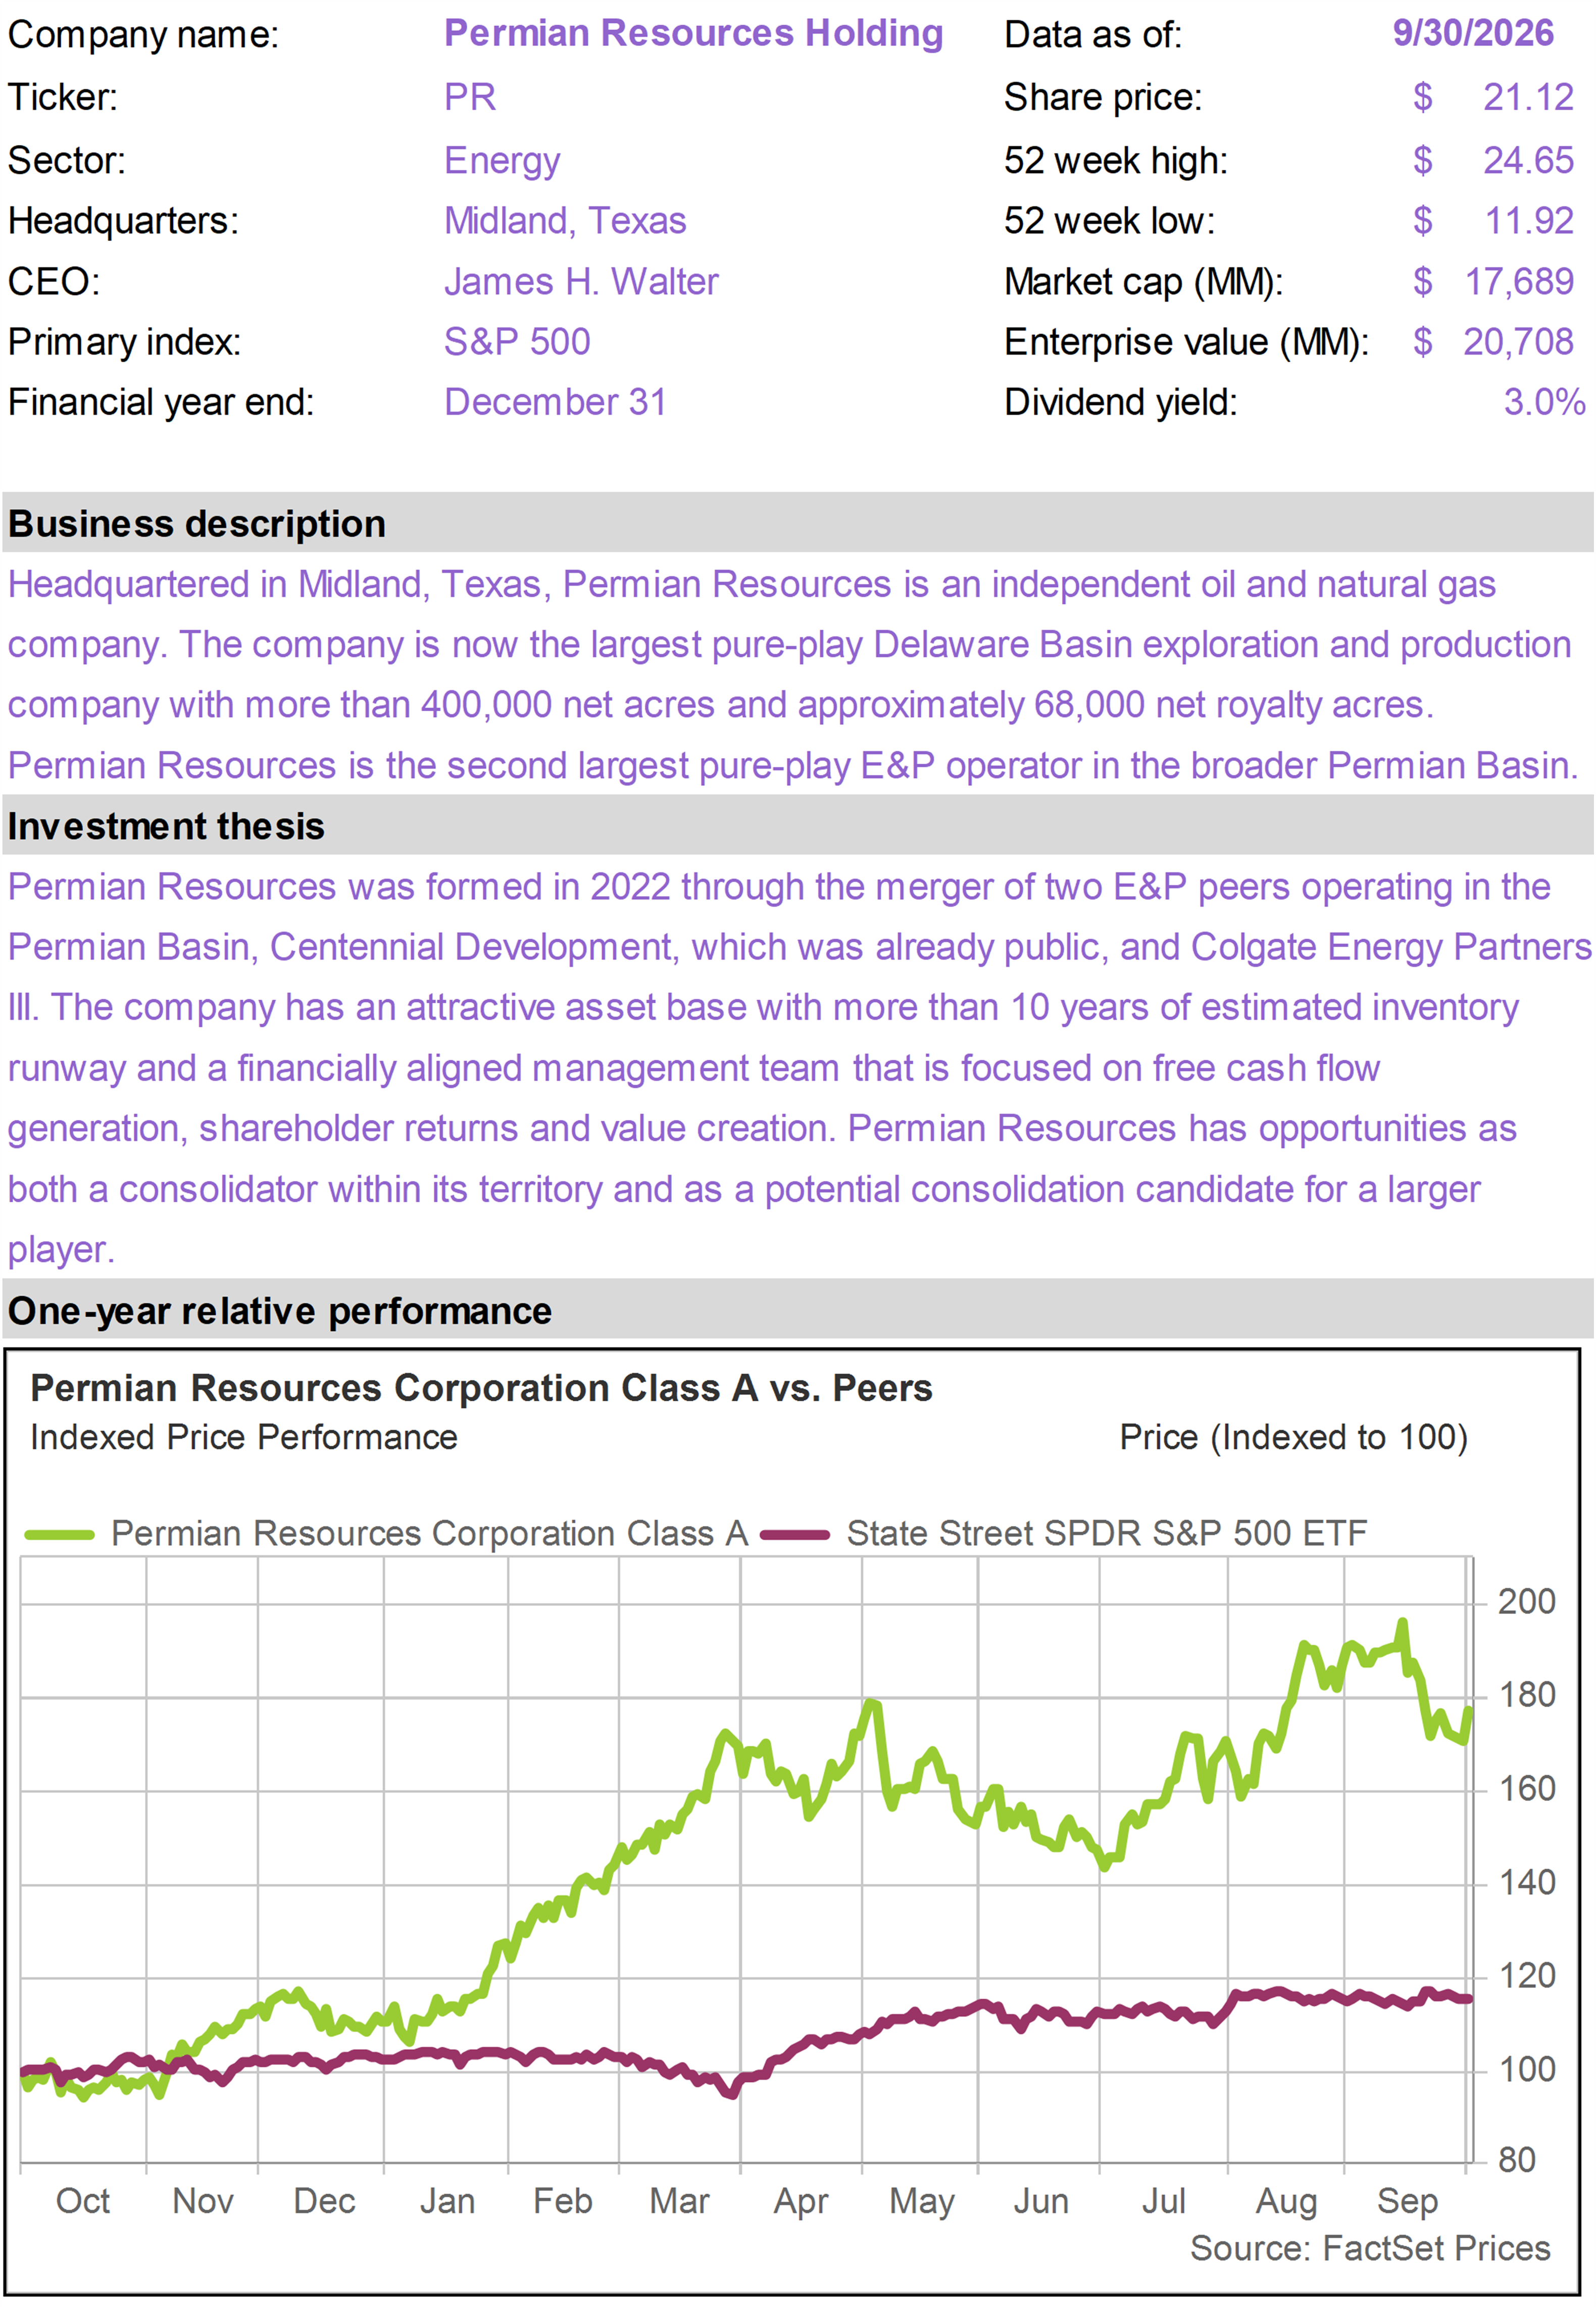
| | WCC performed well in September, supported by its alignment to the AI buildout and continued optimism around its exposure to data centers, electrical infrastructure and U.S. industrial investment.
Momentum continues to build after the company reported strong second quarter results. Sales increased 13% year over year to a record $6.7 billion, while adjusted EBITDA rose 24% and adjusted EPS increased 35%.
Importantly, growth was not confined to data centers: sales excluding data centers still increased at a mid-single-digit rate, reflecting strength across construction, industrial, utility and OEM markets.
Data centers nevertheless remain the most powerful growth engine. WCC generated approximately $1.5 billion of data center sales in the quarter, up roughly 45% year over year.
Management raised its full-year data center growth outlook to more than 30%, while total company backlog increased 60% to a record level.
A major multi-year Grid Services award from a hyperscale customer demonstrates WCC’s growing role in supplying power infrastructure, while the acquisition of Newark Engineering adds engineered cooling capabilities.
We continue to view WCC as an attractive way to participate in several overlapping investment cycles—AI infrastructure, electrification, grid modernization and U.S. reshoring—with improving profitability providing an additional earnings tailwind. |
|
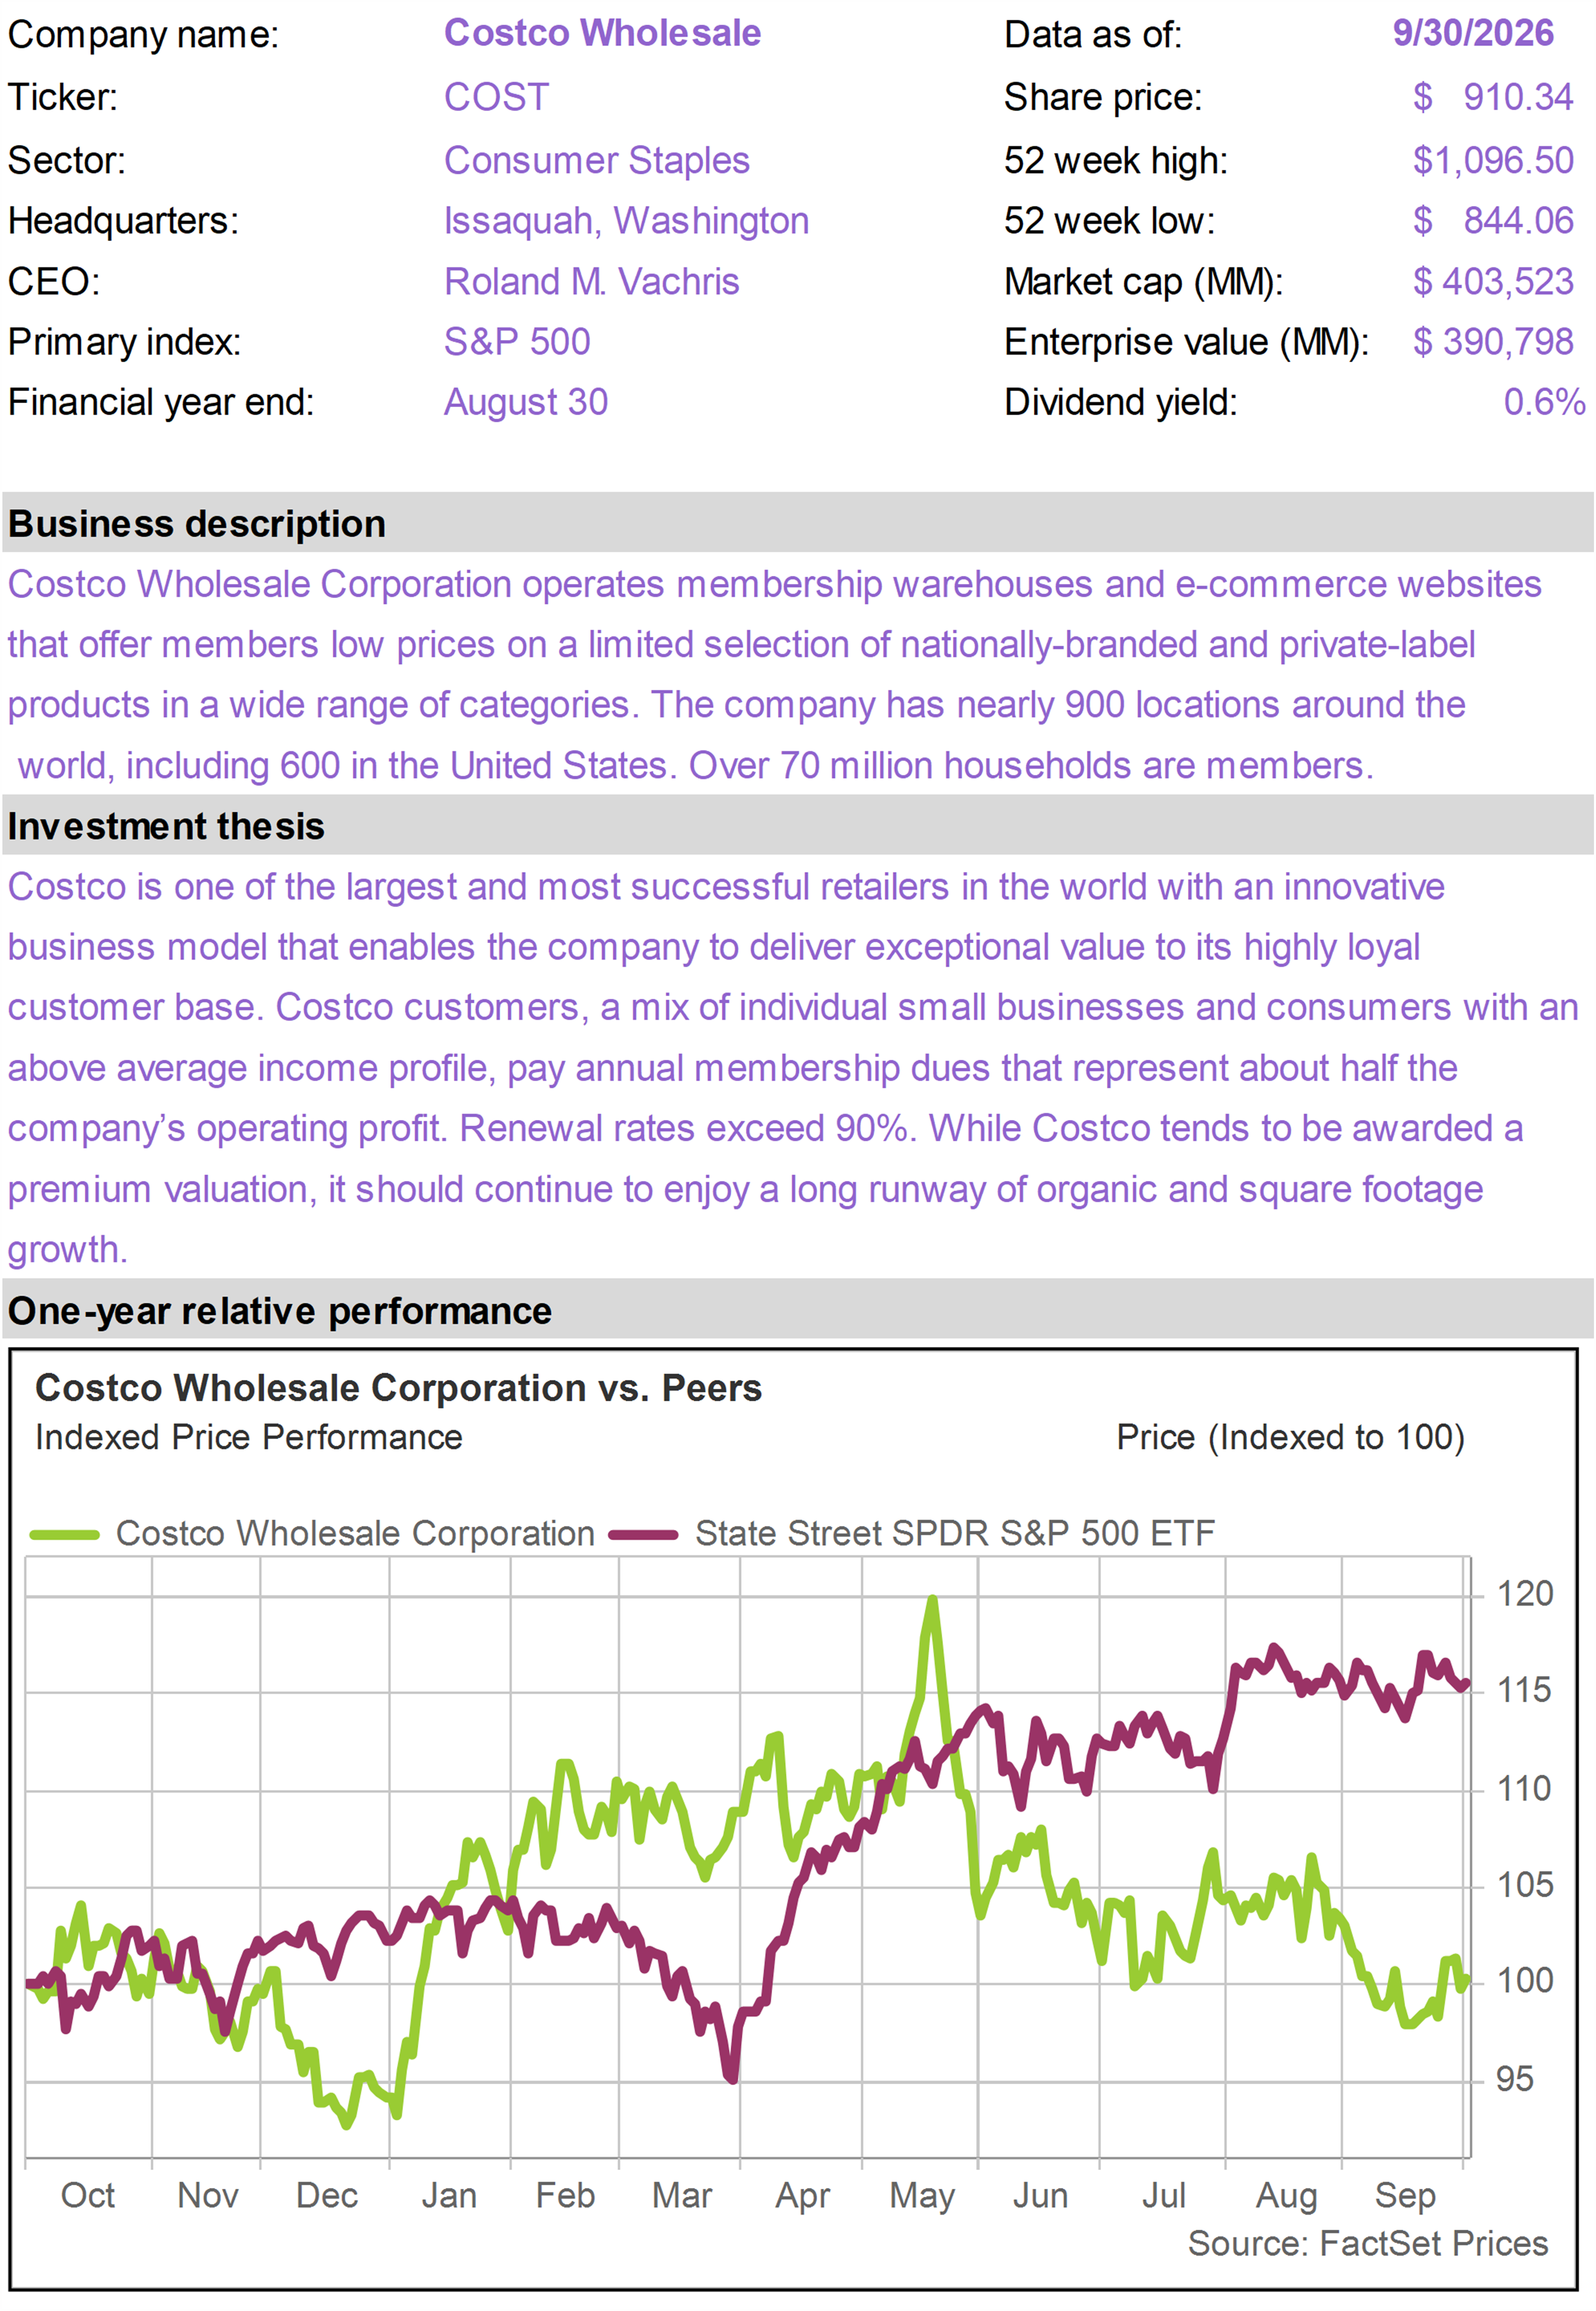
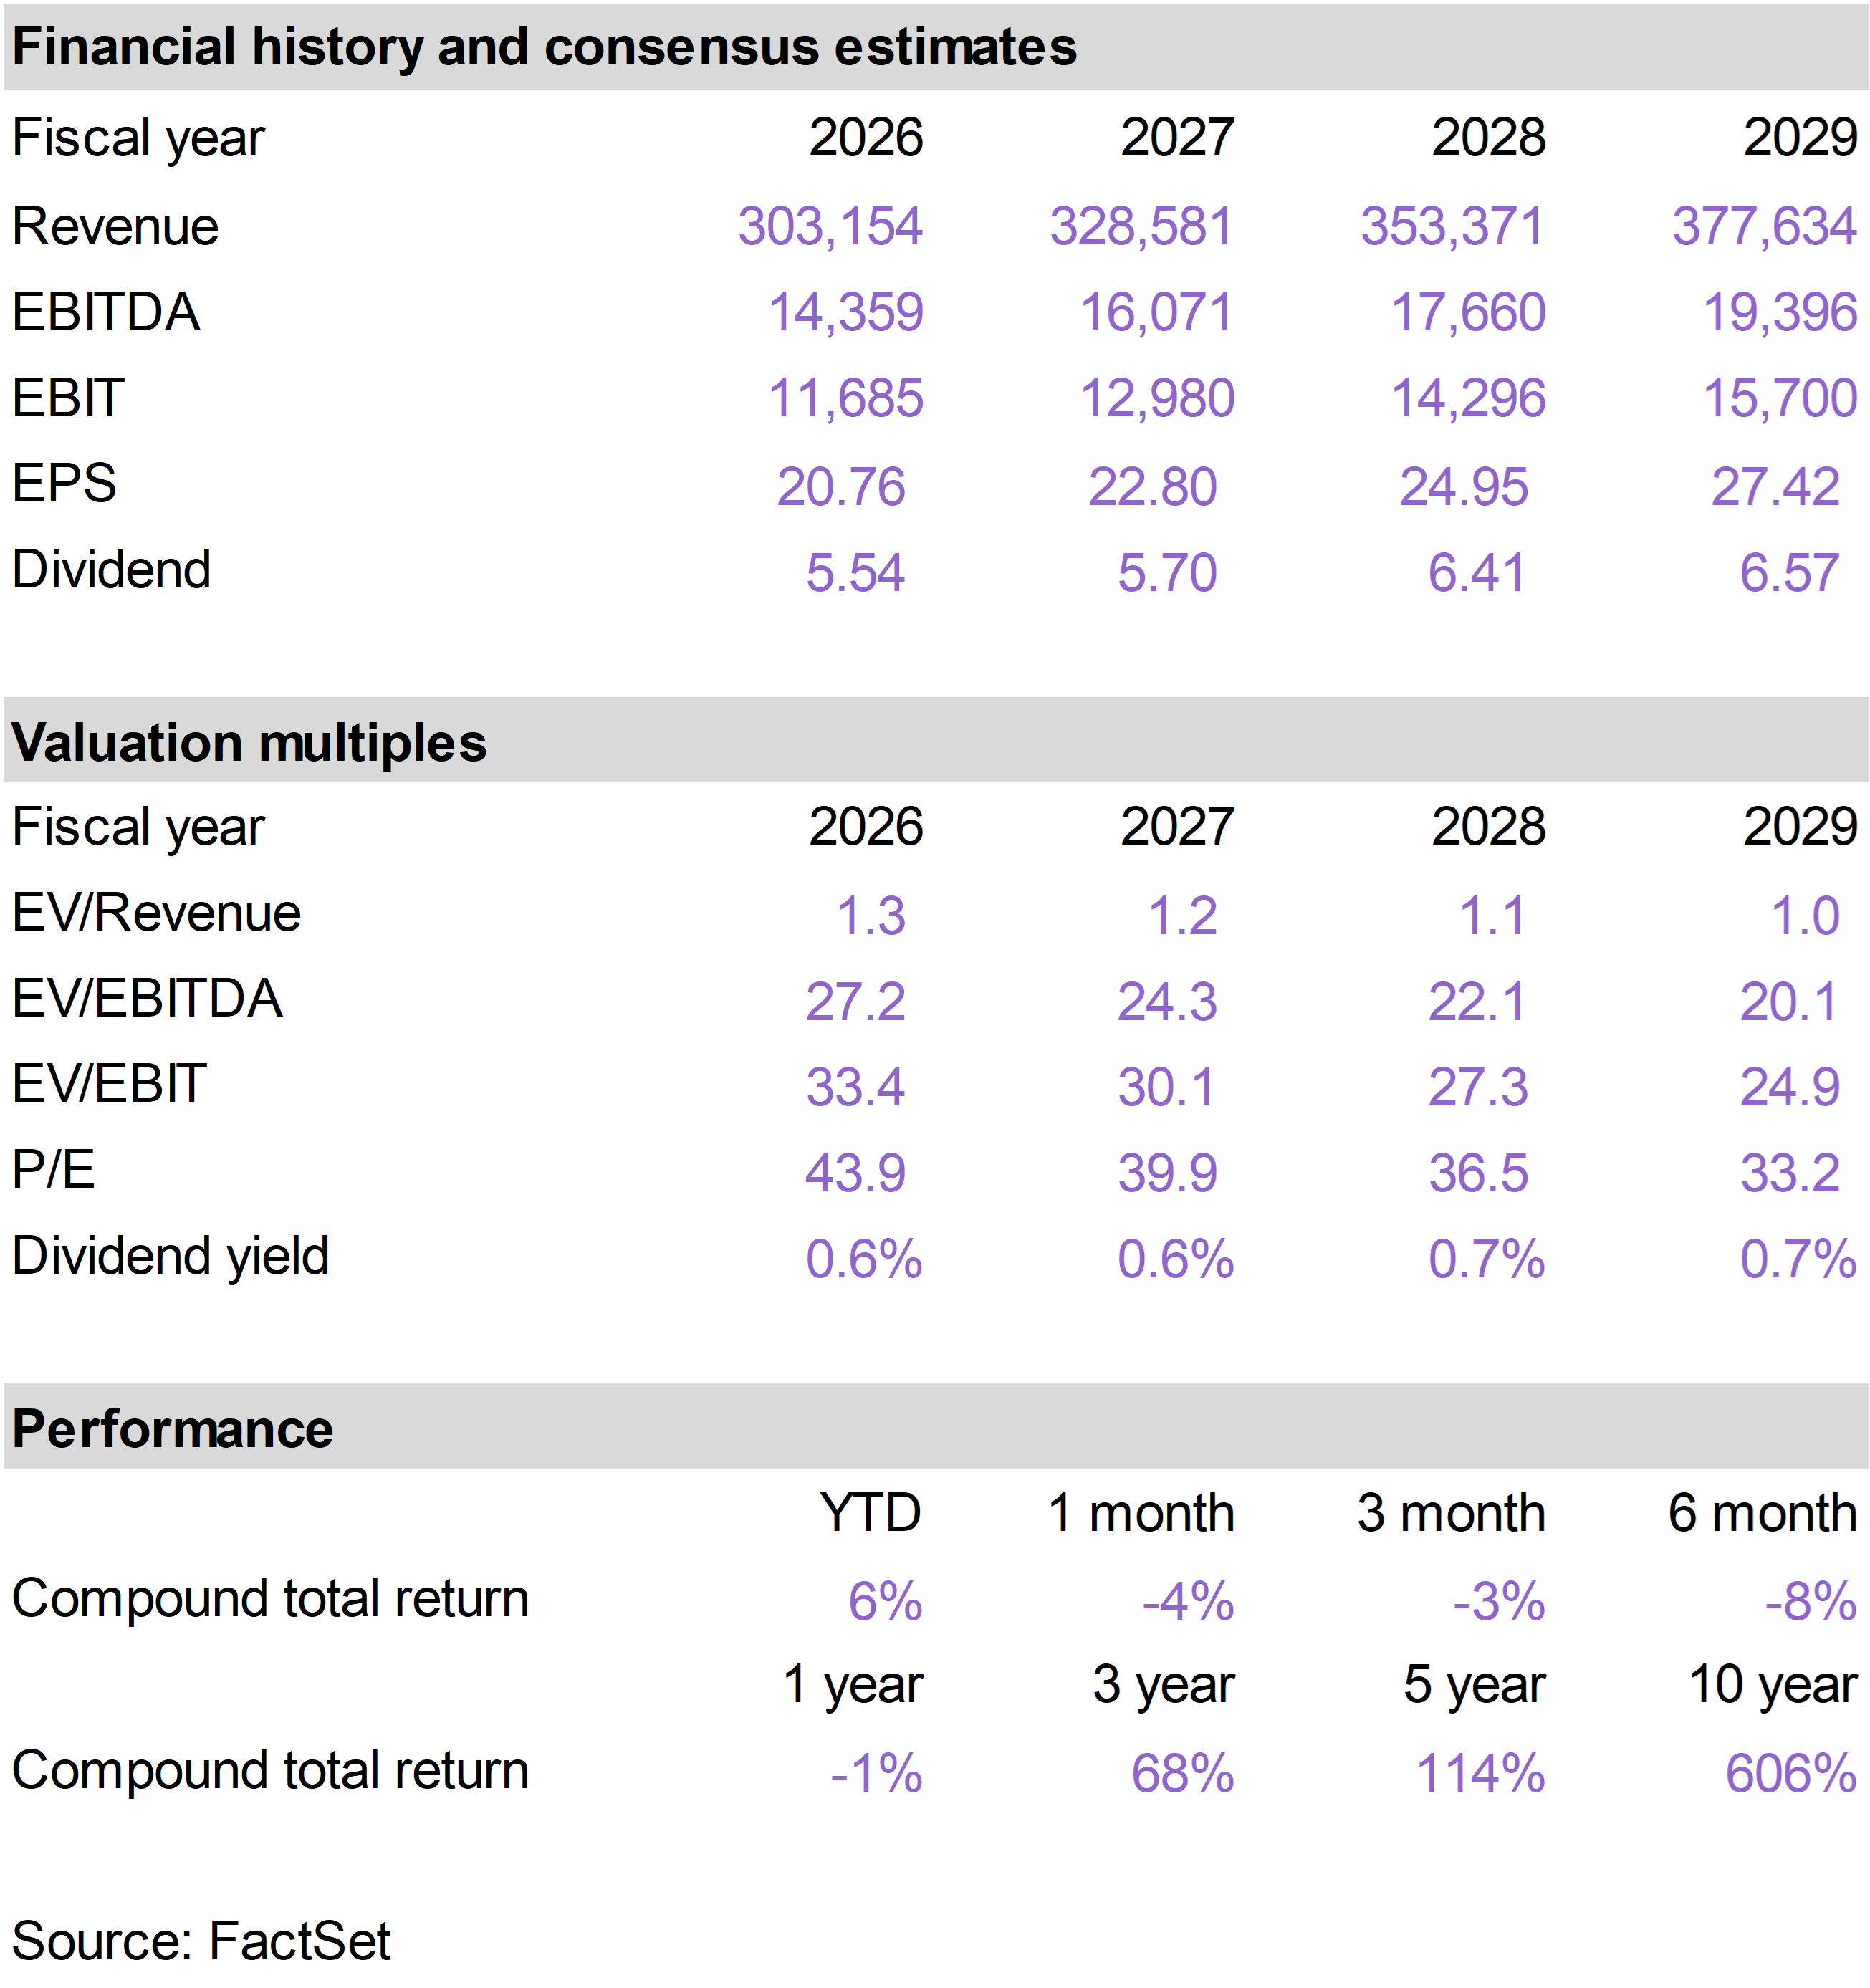
| | In a difficult month for consumer stocks, COST shares were resilient. Investors responded positively to another solid quarter and continued evidence that the company’s membership model remains exceptionally durable.
Fourth quarter net sales increased 11.2%, while comparable sales rose 6.7% excluding gasoline and foreign exchange. Traffic increased 3.3%, and digitally enabled comparable sales grew nearly 20%, demonstrating continued strength across both the warehouse and online channels.
Membership trends were also encouraging. Membership fee income increased 7.3%, Executive memberships grew more than 9%, and renewal rates improved sequentially.
COST is also making meaningful progress digitally. Digitally enabled sales exceeded $33 billion for the year, while the company expanded Uber Eats nationwide and broadened its DoorDash offering. Management noted that these channels are attracting younger customers and appear largely incremental rather than cannibalizing warehouse traffic.
The company continues to have a substantial runway for physical expansion as well, with 33 warehouse openings planned for fiscal 2027, including five relocations.
We continue to view COST as one of the highest-quality consumer franchises in the portfolio. Its combination of strong traffic, high renewal rates, growing digital engagement and continued unit expansion should support durable earnings growth, even in a more challenging consumer environment. |
|
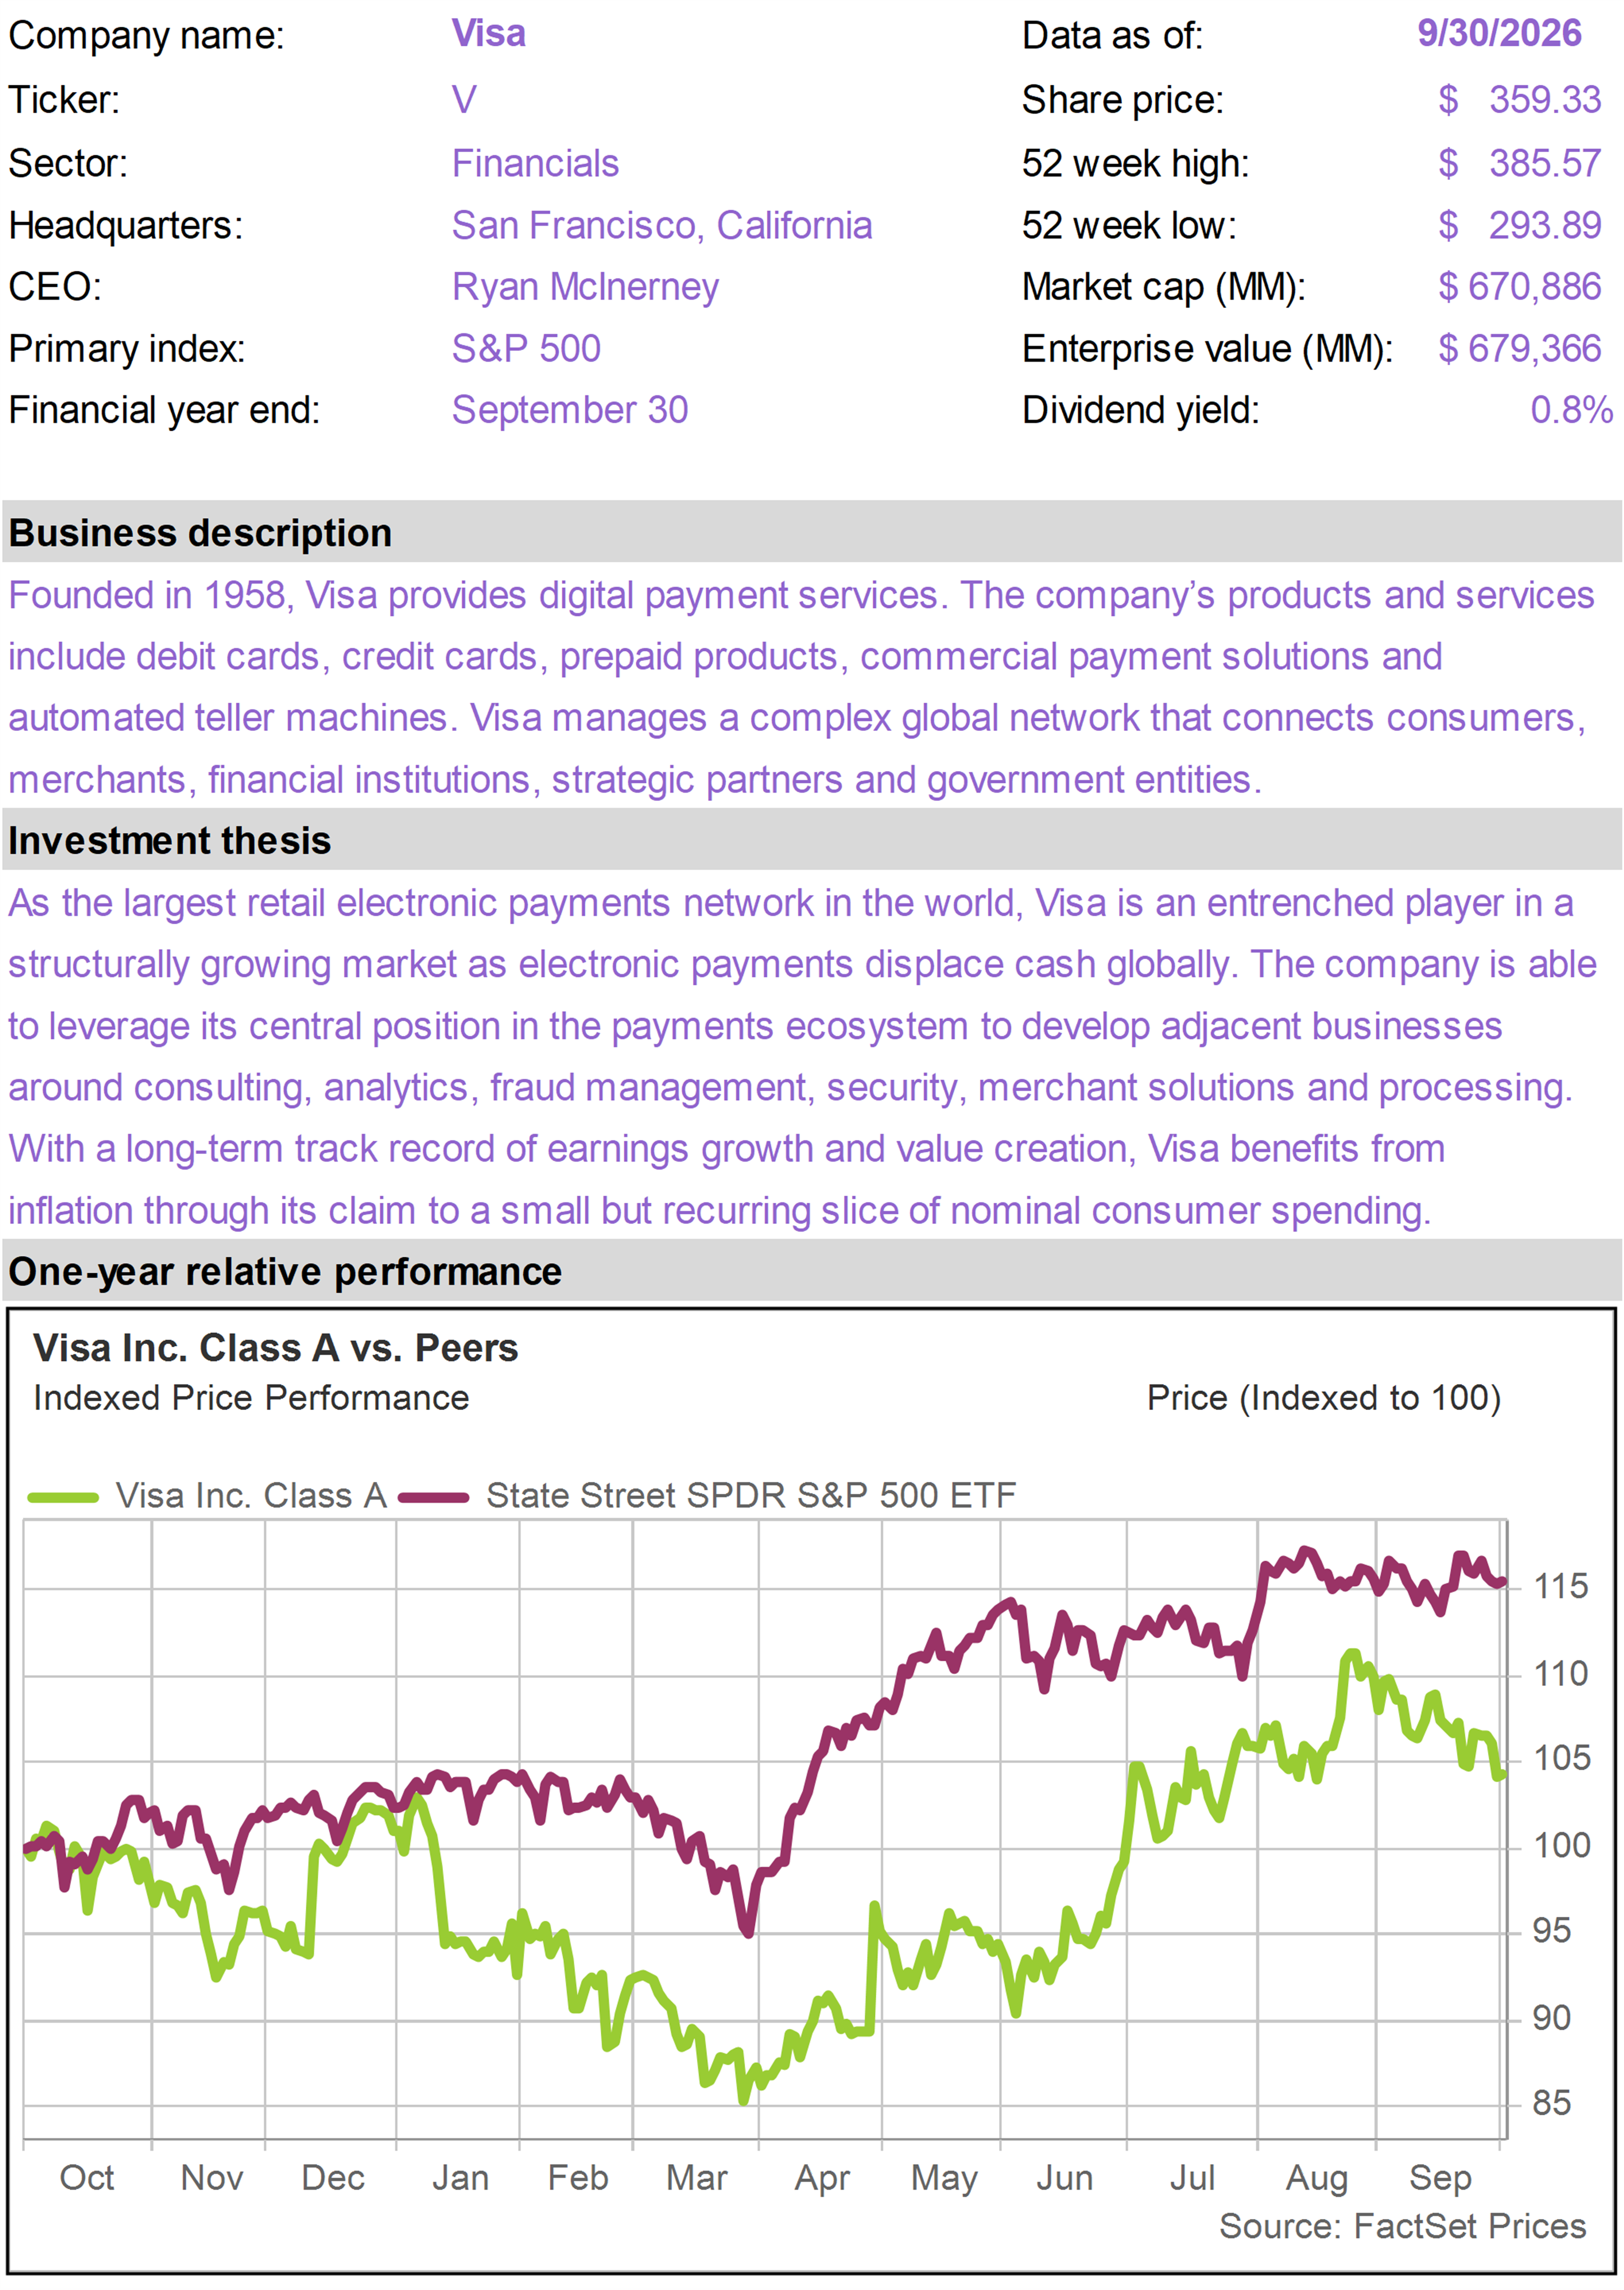
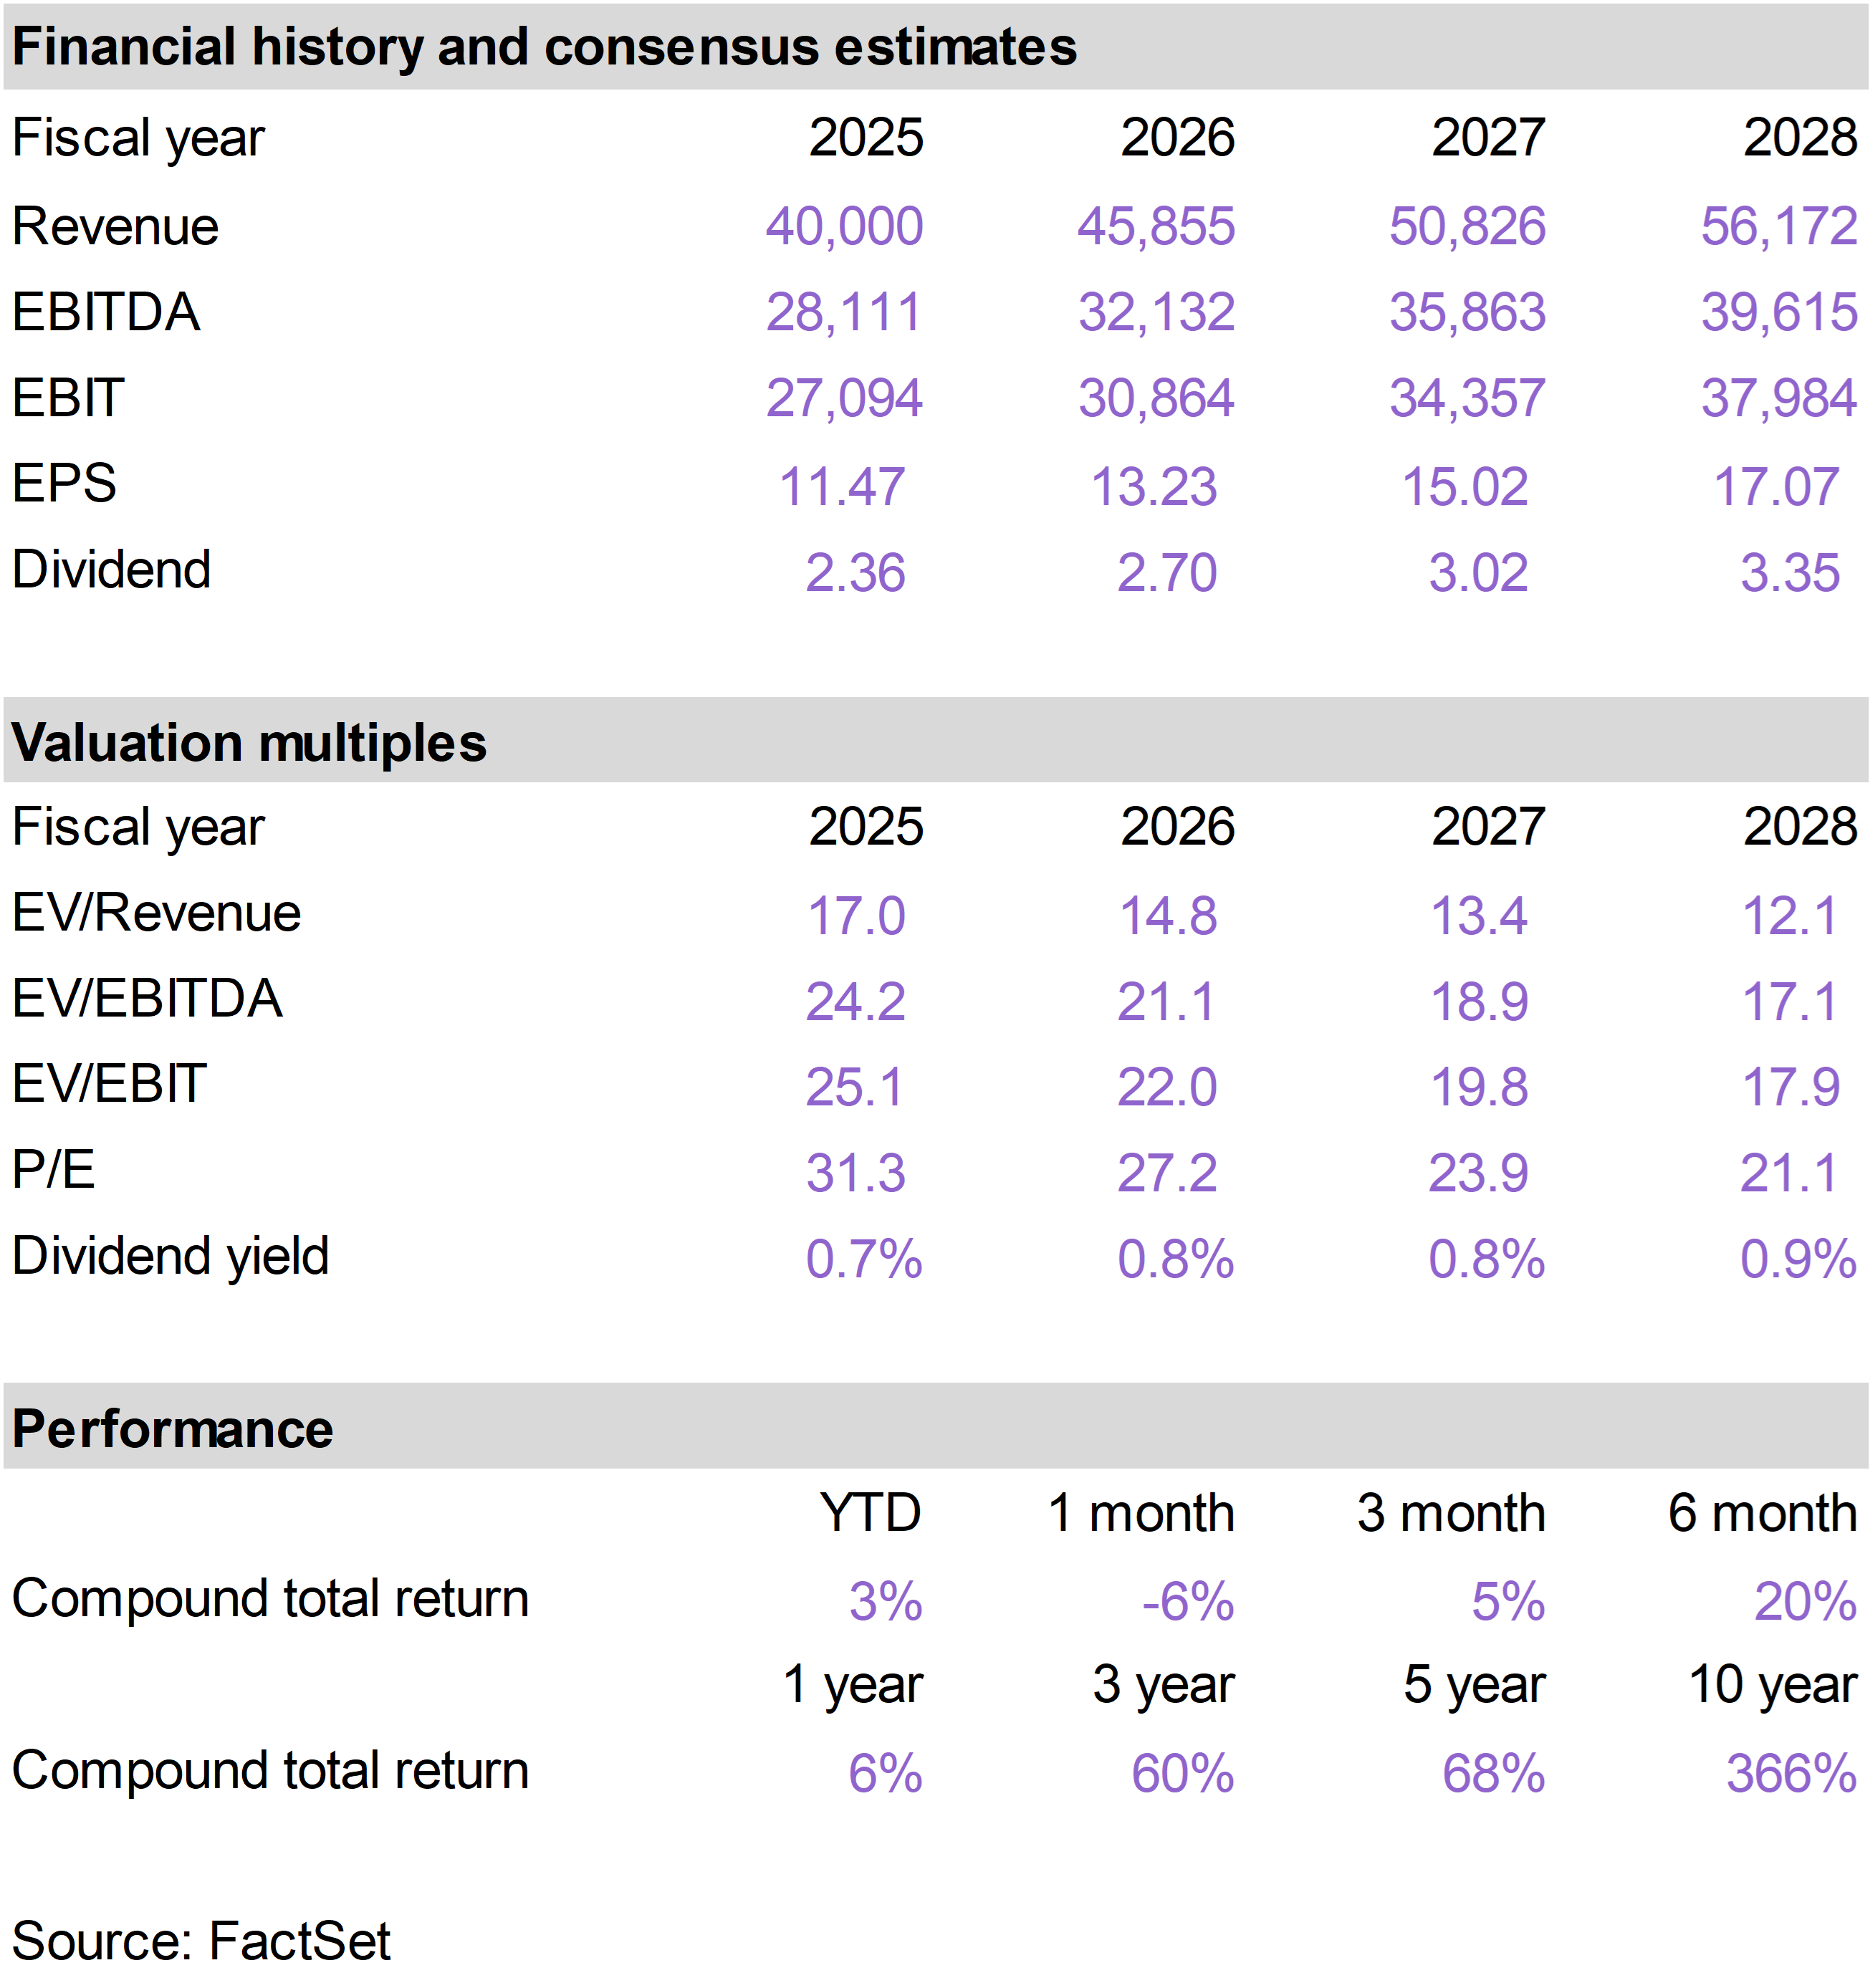
| | V declined modestly in September, despite continued evidence that the underlying business remains exceptionally strong.
Consumer spending trends remain healthy. At a September investor conference, management described U.S. spending as “strong and stable,” with V’s U.S. payments volume growing approximately 9% year over year through the end of August.
Global transaction growth remained around 10%, while cross-border volume accelerated to approximately 14%.
The more important long-term story is the continued expansion beyond traditional card payments. Value-added services now represent approximately 30% of revenue and grew 34% in the most recent quarter, with strong momentum across issuer services, fraud and identity, advisory and acceptance.
V is also positioning itself aggressively for the next generation of payments. Management remains optimistic about agentic commerce, where V can help establish trust between consumers, AI agents and merchants. It is also investing across the stablecoin ecosystem, including settlement infrastructure, wallets and cross-border payments.
Meanwhile, AI is already delivering significant internal productivity gains, including faster product development and materially higher software output.
We continue to view V as one of the portfolio’s highest-quality compounders. The core business remains strong, while new opportunities in value-added services, AI, stablecoins and next-generation commerce continue to expand the company’s addressable market. |
|
| |
CRCL retreated in September as investors reacted to renewed competitive concerns and the failure of the CLARITY Act to advance in Congress.
The legislative setback initially weighed on the broader crypto complex, but we do not view it as a reversal of the longer-term regulatory trend. Agencies such as the SEC and CFTC continue to move ahead with rulemaking that should gradually provide greater clarity for digital assets.
Competitive concerns have also resurfaced around potential rival stablecoins and new reserve-sharing models. We continue to believe those fears miss the larger opportunity.
CRCL’s USDC remains the second-largest stablecoin globally, with deep liquidity, regulatory credibility and broad integration across exchanges, wallets and payment platforms.
CRCL continues to build infrastructure around USDC rather than simply earning interest on the reserves that back it.
The recent launch of the Arc mainnet reinforces that strategy. Over time, transaction revenue from payments, settlement and cross-border money movement could become much more important than reserve income.
Near term, CRCL also remains highly sensitive to the broader crypto cycle. A continued recovery in Bitcoin should support USDC circulation, while higher interest rates remain favorable for reserve income.
We therefore view the September weakness as more reflective of regulatory and competitive noise than a deterioration in CRCL’s long-term position within digital financial infrastructure, which remains excellent. |
|
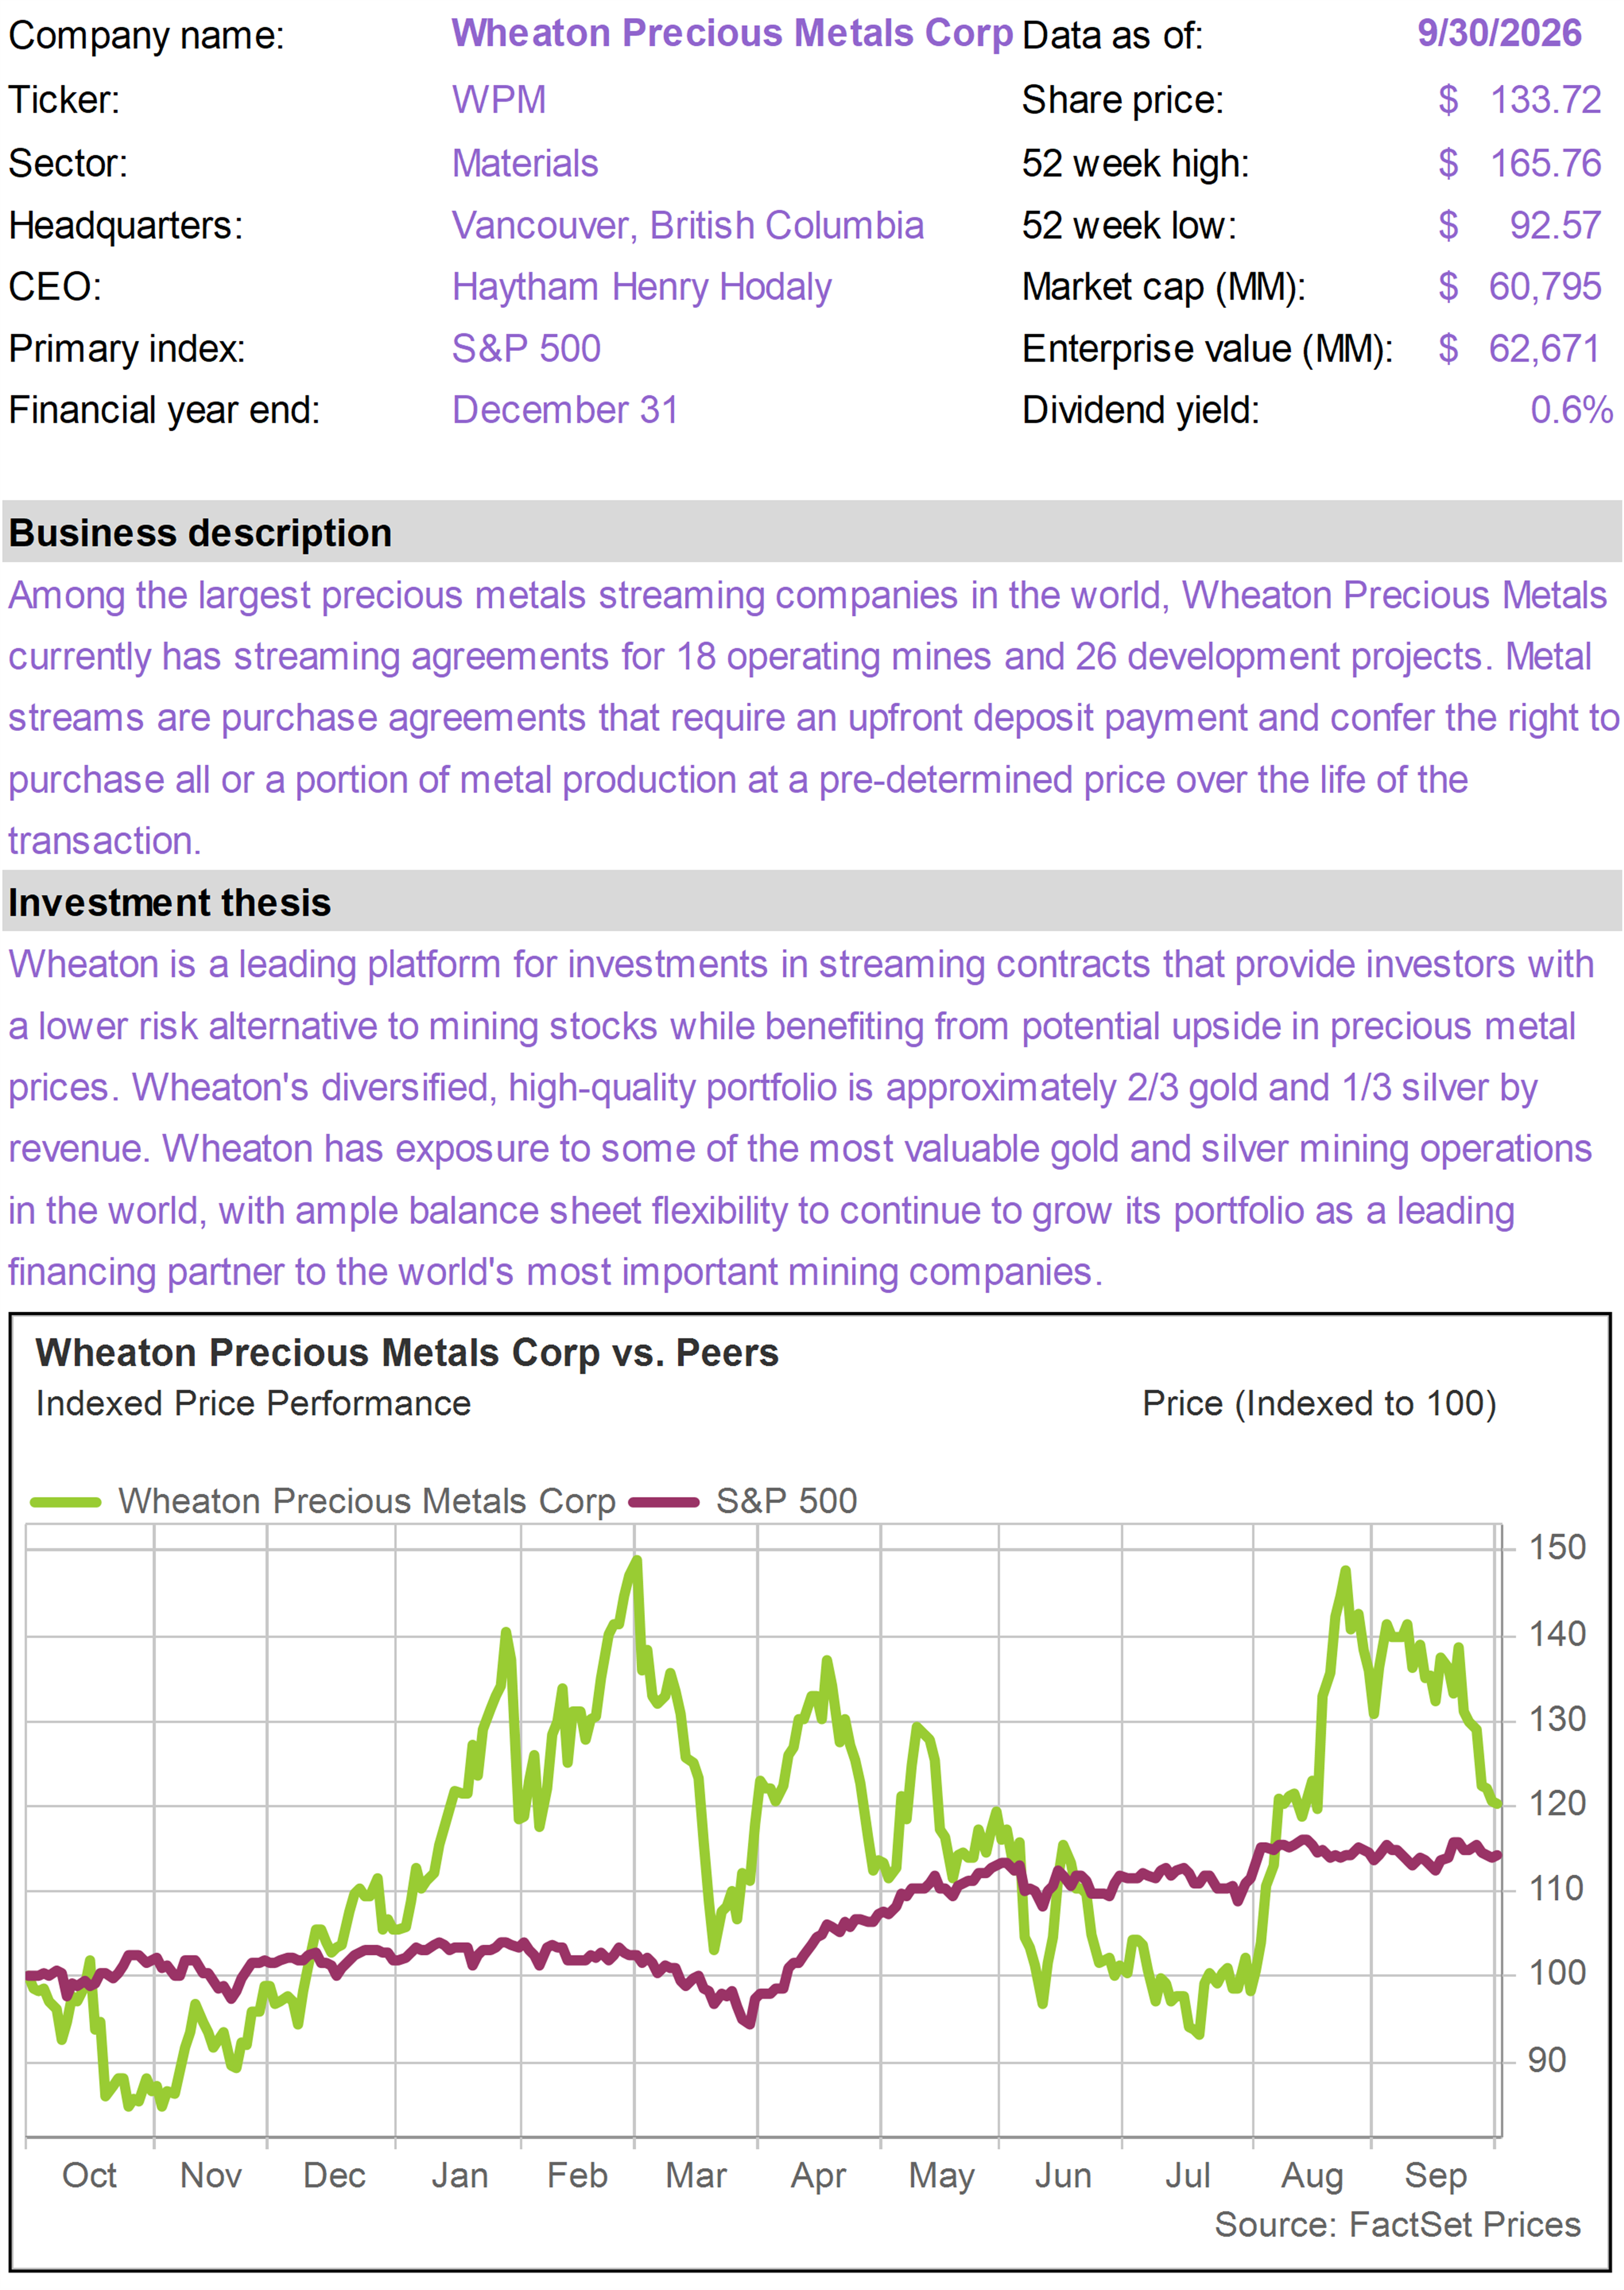
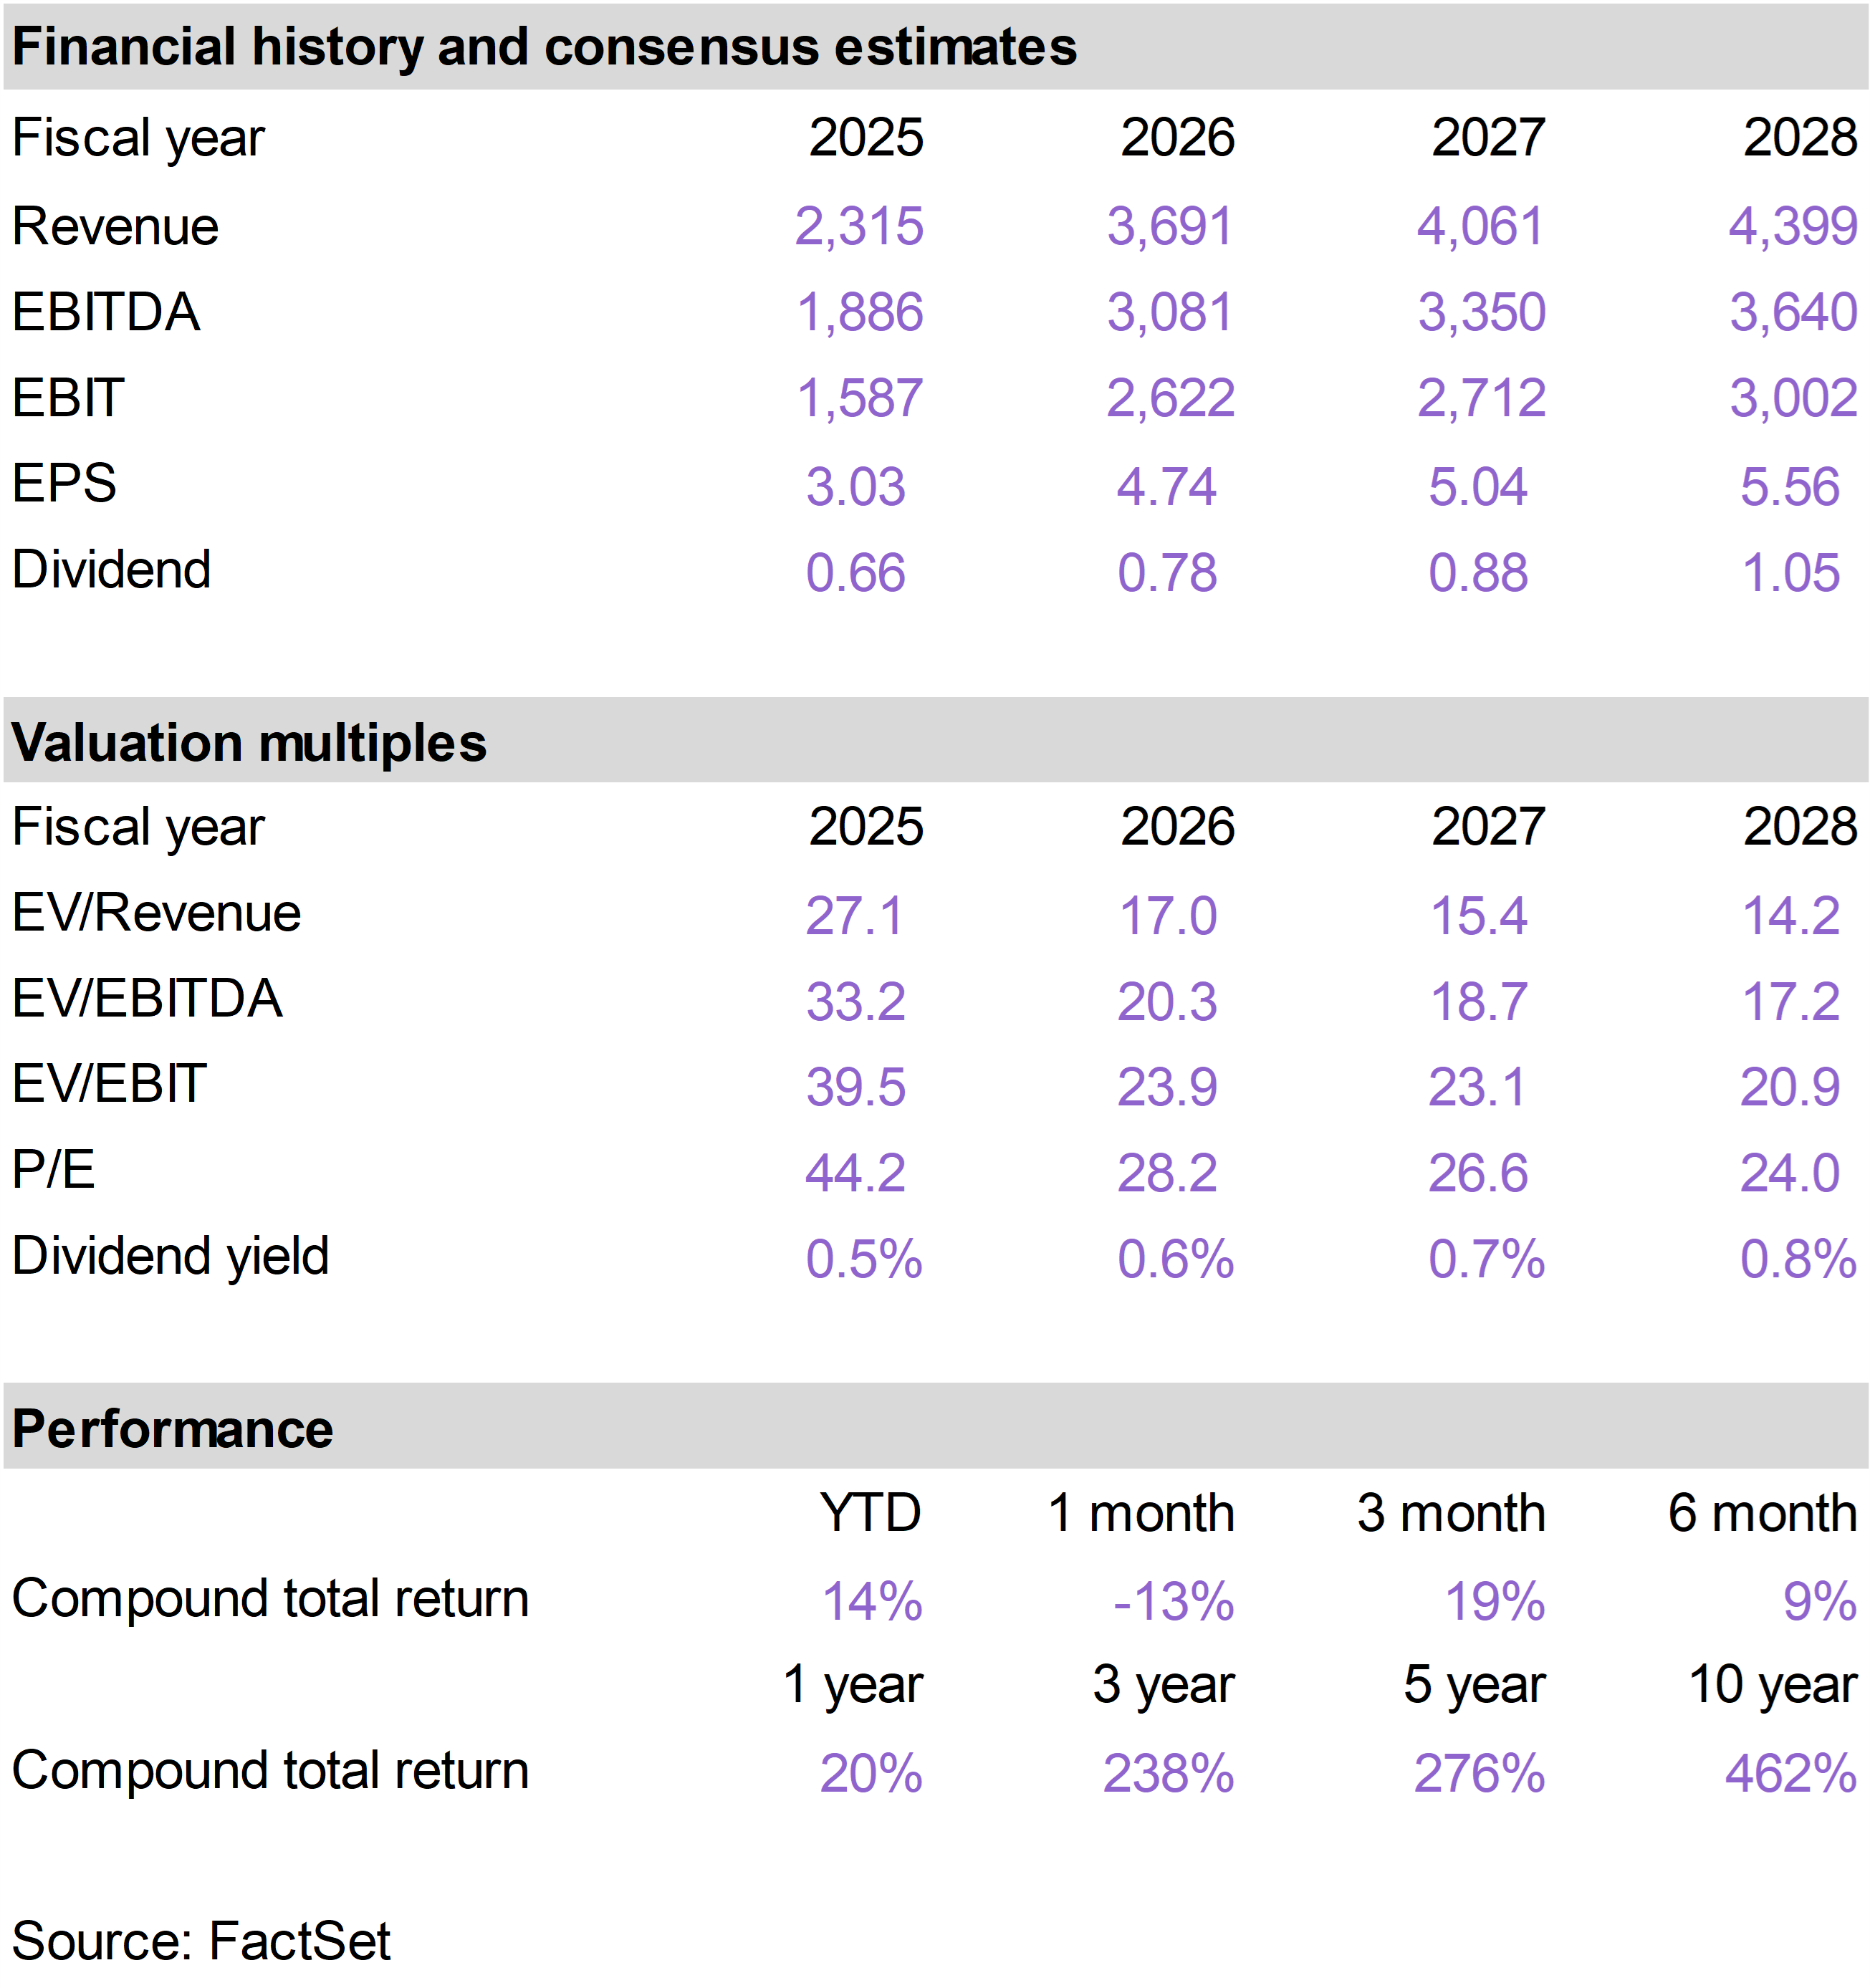
| | WPM came under pressure as higher real interest rates weighed on gold and other precious metals, but the company’s Investor Day reinforced our confidence in the longer-term growth story.
Management reiterated its target of roughly 1.2 million gold-equivalent ounces of annual production by 2030, up substantially from current levels.
Importantly, that growth is already embedded in the existing portfolio: six of nine major development projects are under construction, and management believes the 1.2 million-ounce target is conservative because it excludes a number of potential expansions.
The growth pipeline is also becoming more diversified. New projects are expected to contribute meaningfully over the next several years, reducing reliance on WPM’s largest existing mines. The contribution from its three largest assets is expected to decline from roughly 65% of production today to about 50% by 2030.
WPM also remains financially very well positioned. The company estimates approximately $3 billion of annual operating cash flow at current spot prices through 2030 and retains substantial liquidity even after a record period of new stream investment.
WPM’s streaming model provides direct upside to gold and silver prices without the same operating and capital-cost risks faced by traditional miners, while its already-funded production pipeline offers a significant source of growth even if commodity prices simply remain near current levels. |
|
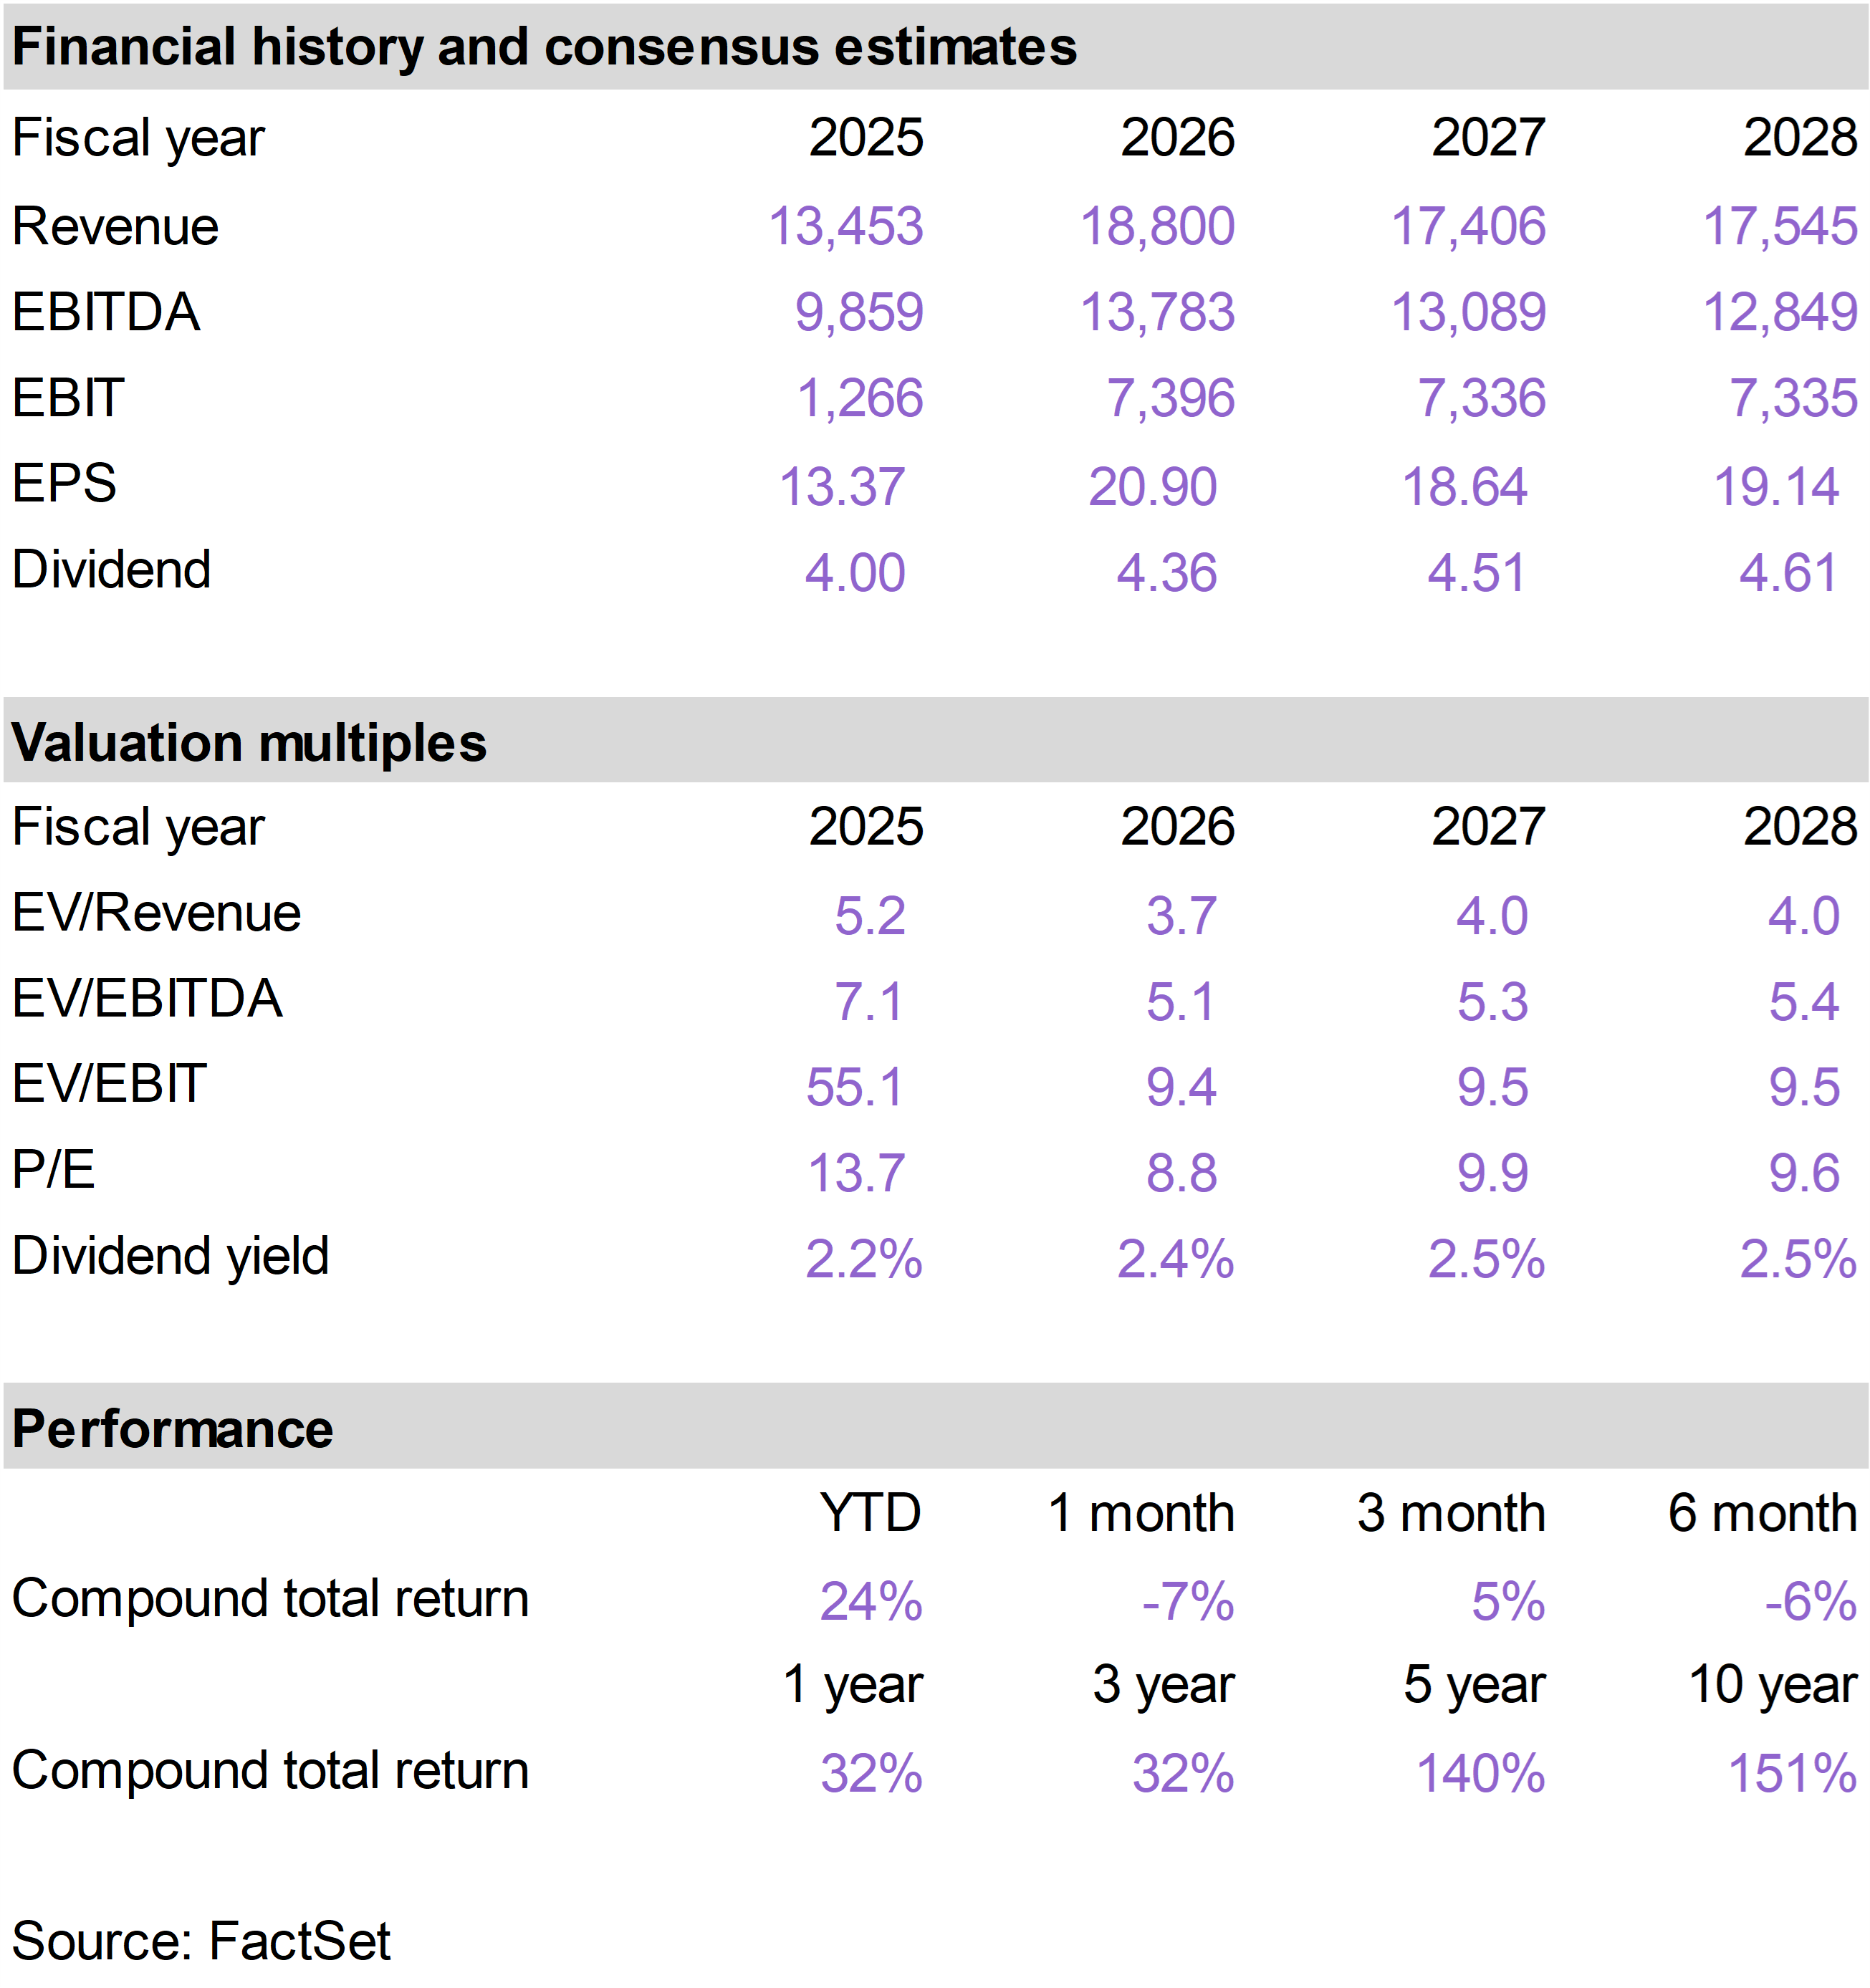
| | RGLD declined this month along with the broader precious-metals complex, but recent management commentary reinforced the strength of the company’s increasingly diversified royalty and streaming portfolio.
The Sandstorm and Kansanshi transactions have materially changed Royal Gold’s profile. The company now has only two assets contributing more than 10% of revenue, with the largest at roughly 12.5%.
Management believes this significantly reduces the portfolio concentration and event risk that historically surrounded such assets.
The growth profile has also improved. Sandstorm brought a deep pipeline of development assets, including Platreef and Hod Maden, while Kansanshi and other existing interests provide additional near-term upside.
RGLD has also been simplifying the portfolio following the Sandstorm acquisition, selling or restructuring several non-core equity and debt interests and using more than $200 million of proceeds to reduce debt.
We continue to view RGLD as an attractive precious metals holding. Its royalty and streaming model provides exposure to higher gold prices with limited direct operating-cost inflation, while the enlarged portfolio offers better diversification, longer asset lives and a stronger pipeline of future cash flow growth. |
|
| | |
| | |
| | |
| | | |
|
| | |
|
| | Mid-America Apartment (MAA) |
|
|
|
| | |
|
| | |
|
| | |
|
| | Circle Internet Group (CRCL) |
|
|
|
| | Diamondback Energy (FANG) |
|
|
|
| | Floor & Decor Holdings (FND) |
|
|
|
| | |
|
| | |
|
| | |
|
| | WESCO International (WCC) |
|
|
|
| | Wheaton Precious Metals (WPM) |
|
|
|
| | The 76research Inflation Protection Model Portfolio emphasizes business models that benefit from inflationary pressure. Holdings are typically selected from industries based on supply constrained real assets, including commodity and energy businesses, or companies that otherwise demonstrate superior pricing power. Drawing from an investable universe of expected inflation beneficiaries, specific holdings are chosen based on valuation and general business quality, growth and risk considerations. |
|
| | FOR SUBSCRIBER USE ONLY. DO NOT FORWARD OR SHARE. |
|
| | | |
|
|
|
|
|